Kadant's Capital Recovery Story Faces A Bookings Test After A 21% Stock Slide
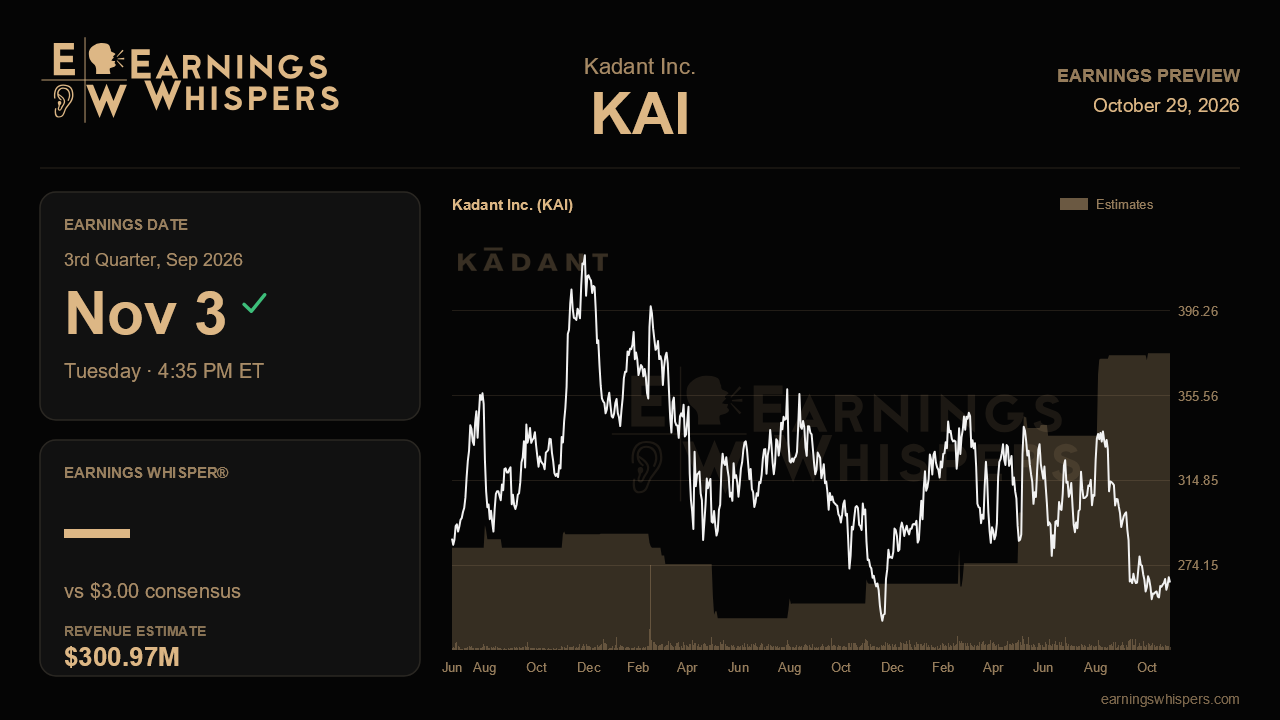
Kadant heads into its third-quarter report with an unusual disconnect. Last quarter management delivered record revenue and earnings, raised its full-year outlook and spoke with more confidence about a capital equipment recovery than at any point in more than two years. The stock has since fallen about 21% while the S&P 500 was essentially flat. The November 3 release, due after the close, needs to show whether that recovery is real or whether the market's skepticism is justified.
The bar itself is not high. Consensus calls for EPS of $3.00 on revenue of $301.0 million, which would mean growth of roughly 16% in earnings and 11% in sales from a year ago. Both figures are below the second quarter's $3.42 and $312.9 million, because management guided to a flattish to softer third quarter of $2.90 to $3.00 per share on revenue of $297 million to $307 million. Analysts have moved down from earlier, loftier estimates. They now sit at the top of the EPS range and near the middle of the revenue range. Kadant has topped the high end of its own EPS guidance by $0.36 to $0.44 in each of its last several beats. Simply matching $3.00 would therefore break that pattern, and another beat of similar size would push results well above the Street.
The more important evidence will come from orders. Bookings rose 16% to $312 million last quarter, following gains of 25% and 12% in the two quarters before. Organic capital revenue jumped 23%. Management said several large projects were in advanced stages and that some releases could come soon, including packaging conversions worth $10 million to $25 million each. It also booked an $8 million aerospace order and described demand as improving across nearly every end market. If some of those large conversion orders show up in third-quarter bookings, the narrative of stronger second-half capital spending heading into 2027 gets real support. Flat or declining bookings, or another round of projects slipping because of tariff and geopolitical uncertainty, would suggest the cautious tone of earlier quarters was closer to the truth.
Margins are the second swing factor. Gross margin fell to 43.8% from 45.9% a year earlier. That reflects a heavier mix of capital equipment plus an inventory profit deferral tied to the Cadent Profile acquisition, which management expects to last through year-end. The full-year gross margin assumption was already cut to 44% to 44.5%. Gross margin below that band would raise questions about how much of the record EBITDA margin of 21.8% can hold. The pace of Cadent Profile, whose run-rate was already lowered to about $55 million, and continued weakness in European flow control are additional sources of pressure. With net debt up to $373 million and leverage at 1.72 times after the acquisition borrowing, steady free cash flow would also help reassure investors.
Sentiment has clearly cooled. Readings have moved further into bearish territory than before the last report, and the shares, at $265.80, sit well below the 200-day moving average of $306.80. They are only about 5% above the post-earnings low of $253.41, after peaking above $345 following the second-quarter report. In other words, the market is pricing in disappointment, even though management raised the full-year range to $12.43 to $12.68 per share and $1.19 billion to $1.21 billion in revenue.
That sets up a straightforward test. Kadant does not need a blowout quarter, but it does need to show that the large projects it talked about are turning into orders, and that the acquisition-related squeeze on margins is holding steady rather than getting worse. If it can show both while reaffirming or tightening its full-year outlook upward, the recovery story stays intact and the recent selloff may look overdone. If orders stall, the market's doubts will gain weight.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-19 | |
| Sep-10 | |
| Sep-10 | |
| Sep-08 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| May-21 | |
| May-21 | |
| May-05 | |
| May-05 | |
| Apr-30 |
