Kadant Crushes Q3 Estimates And Raises Its Outlook, But A Shrinking Capital Backlog And Softer Q4 Guide Temper The Beat
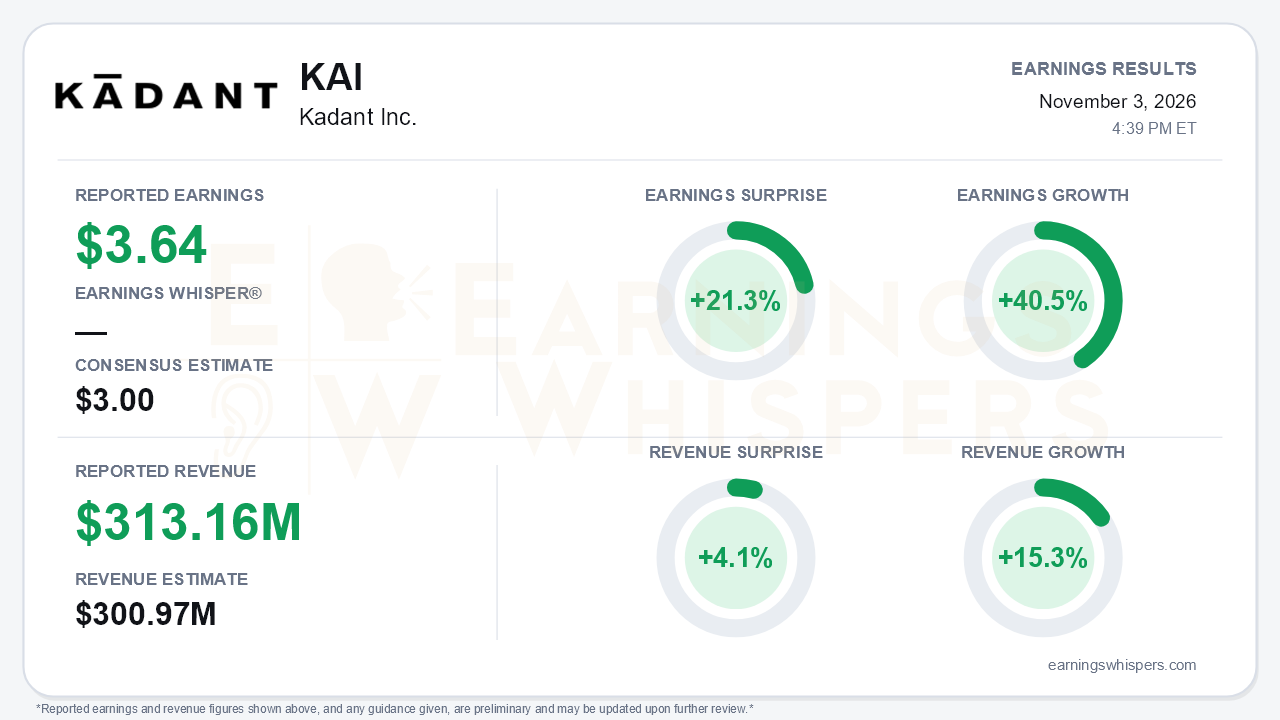
Kadant delivered the kind of quarter that usually ends a debate, but this one may simply reframe it. The company reported adjusted earnings of $3.64 per share, 21.3% above the $3.00 consensus. Revenue rose 15.3% to a record $313.16 million, beating the $300.97 million estimate by 4.1%. Earnings Whispers measures year-over-year earnings growth at 40.5%. The company's own comparison under its new methodology, which excludes intangible amortization, shows adjusted EPS up 21% from a restated $3.01, and GAAP EPS rose 26% to $2.96. That is the third straight record quarter, and adjusted EPS cleared the top of management's own guidance by $0.64, a wider margin than the $0.44 and $0.43 beats in the prior two quarters. The central tension is that the forward indicators are moving the other way. Organic growth slowed, the capital backlog shrank again, and Earnings Whispers flagged the outlook as below estimates.
The quality of the beat deserves scrutiny. Acquisitions contributed 11 points of the 15% revenue increase, leaving organic growth at just 4%, half of the 8% pace in Q2. Organic capital revenue grew 5%, down from 23% in the prior quarter. Profitability still improved meaningfully. Adjusted EBITDA reached a record $71.7 million, and its margin climbed to 22.9%, up from 21.8% in Q2 and 20.2% in Q1. Flow Control posted a record 30.7% EBITDA margin. Free cash flow hit a record $58.1 million. Gross margin is the weaker spot. It slipped 50 basis points year over year to 44.7% on capital mix, even with tariff refunds acting as a tailwind. Management acknowledged limited pricing power, so the EBITDA gains are coming largely from cost control rather than price.
The segment detail shows where momentum is concentrated. Industrial Processing revenue jumped 35%, mostly from acquisitions. Material Handling revenue fell 4% as capital shipments weakened, and its EBITDA margin dropped to 22.1% from 23.3%. Demand signals were better than the revenue line suggested. Bookings rose 22% to $291.1 million, with 10% organic growth and gains in all three segments. Aftermarket parts revenue reached a record, and parts and consumables were 70% of revenue, a stabilizing base. Capital orders are not converting fast enough, however. Capital backlog fell from $193 million in Q1 to $182 million in Q2 and $167 million in Q3. Large $5-25 million Industrial Processing projects still face extended quote-to-order cycles, and some Material Handling projects could slip into 2027. That stretches the second-half capital recovery narrative management has leaned on all year.
Guidance captures the same split. Full-year adjusted EPS guidance rose to $12.58-$12.73 from $12.43-$12.68. The 15-cent increase at the midpoint, however, is far smaller than the Q3 upside. Q4 guidance calls for revenue of $287-$302 million and adjusted EPS of $2.67-$2.82, a clear sequential step-down. Gross margin guidance was trimmed again to 44-44.3%, down from 45.2-45.7% at the start of the year. Lower SG&A, tax, and interest assumptions are doing some of the work in the raised EPS outlook.
There are real catalysts beyond the quarter:
- **Inventory drag unwinding:** Management expects an intercompany inventory overhang, worth roughly $0.20 of 2026 EPS, to turn in Q4 and be largely gone by Q1 2027. That should lift Industrial Processing margins.
- **Newer end markets:** Defense, aerospace, and factory automation are seeing faster investment, including an approximately $8 million aerospace order.
- **Faster deleveraging:** The company repaid $51 million of debt, cutting leverage to 1.49x from 1.72x.
The offsets:
- **Leadership change:** Jeff Powell will become executive chairman, and Michael Colwell takes over as CEO at the start of 2027.
- **Fewer acquisitions:** The M&A pipeline has softened.
- **Weak international demand:** Industrial demand remains weak in Europe and Asia.
- **Noncommittal macro view:** Management was guarded on the broader economy.
The market had already been leaning skeptical. Shares at $282.79 were down 15.8% from the open after the August report and sat 7.6% below the 200-day moving average of $305.99. Investor sentiment remained negative and weakened notably, falling from -0.16 to -0.39. Price and AVWAP trend readings are negative, while momentum reads positive. Investors were not positioned for a beat of this size, but the backlog and guidance details give bears legitimate ammunition.
The bottom line is that Kadant is executing exceptionally on margins, cash flow, and aftermarket demand, and the full-year outlook keeps moving higher. The headline, however, masks decelerating organic growth, a capital backlog that has fallen for two straight quarters, and a recurring pattern of capital orders slipping right. Until large project orders convert and gross margin stabilizes, the record results may earn credibility without fully resolving investor doubts.
Read our earnings preview for Kadant Inc.: https://www.earningswhispers.com/article/KAI/22510
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-19 | |
| Sep-10 | |
| Sep-10 | |
| Sep-08 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| May-21 | |
| May-21 |
