Monolithic Power Breaks $1 Billion As AI Demand Accelerates, But A Stock Down 19% Shows The Market Is Weighing More Than The Beat
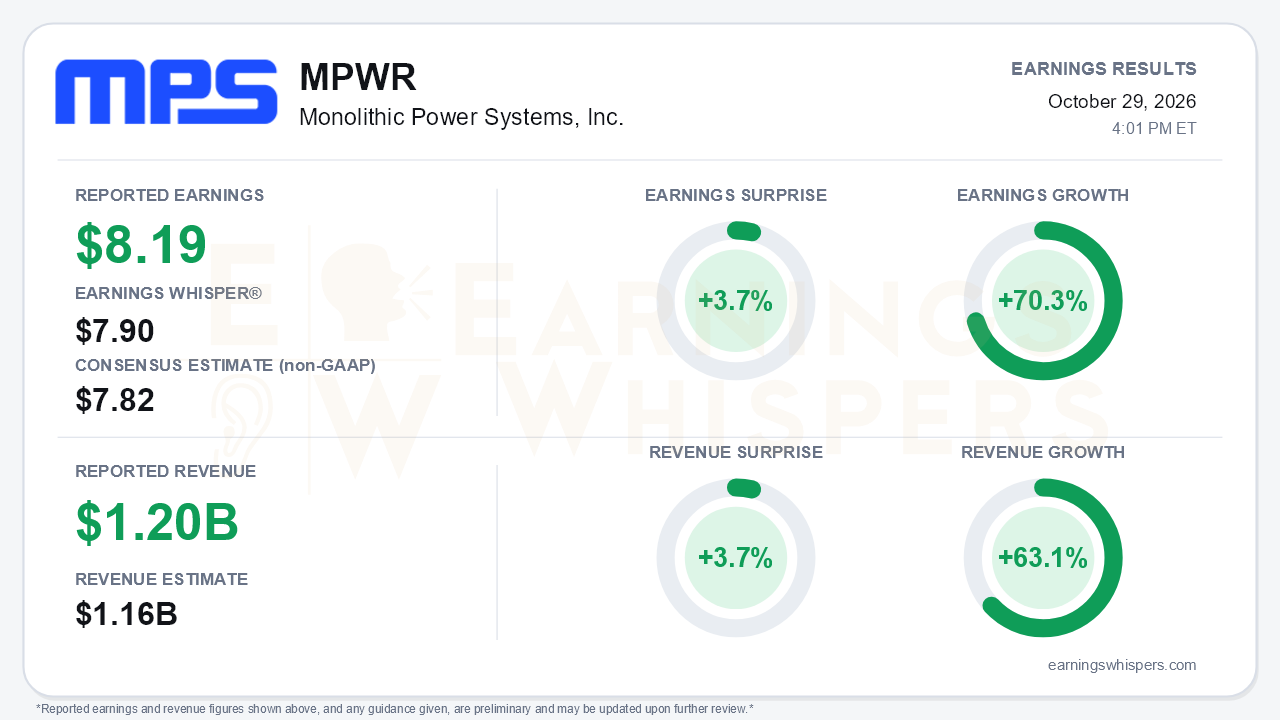
Monolithic Power Systems crossed a milestone that would have seemed ambitious a year ago. Third-quarter revenue reached $1.202 billion, the company's first quarter above $1 billion. Non-GAAP earnings of $8.19 per share beat the $7.82 consensus and the $7.90 Earnings Whisper number by 3.7%. Revenue topped the $1.16 billion consensus by the same 3.7%. Earnings grew 70.3% year over year and revenue rose 63.1%, and the growth is still accelerating. Year-over-year revenue growth has climbed from 26% in Q1 to 48% in Q2 to 63% now. The Q4 outlook of $1.315 billion to $1.385 billion came in above estimates. The central tension is that the fundamentals have rarely looked stronger, yet the stock entered the report down 19.2% since the open after the July release, and investor sentiment had turned negative.
The quality of the beat is high on revenue and operations, though the GAAP picture deserves scrutiny. AI and server power drove Enterprise Data up 33.2% sequentially and 164.6% year over year to $506.7 million, now 42.1% of sales. Communications was the other standout, up 42.5% sequentially on optical module and switch demand. Non-GAAP operating margin expanded to 38.6% from 37.5%. GAAP results tell a less flattering story. Stock-based compensation roughly doubled to $106.3 million from $53.5 million, GAAP operating margin slipped 1.3 points sequentially to 29.7%, and GAAP EPS rose a more modest 47.3% year over year to $5.51. Q4 guidance calls for stock compensation to climb again to $121 million to $125 million, so the gap between the two earnings measures is widening rather than closing.
The call reinforced the acceleration story. Management raised its fiscal 2026 Enterprise Data growth floor to 150%, the fourth consecutive increase, up from 130% last quarter and 50% at the start of the year. Capacity now exceeds $6 billion in annual revenue support, with $8 billion targeted by the second half of 2027 and a path to $10 billion. That is an unusually explicit signal of how much demand MPS expects to serve. Gross margin is now moving about 10 basis points per quarter after sitting near 55.5% earlier in the year. Operating expenses are running below the company's model. Management's tone shifted to describing an "explosive growth period" with "no signs of slowdown."
The diversification narrative also gained substance:
- **Automotive:** first orders for 48V power solutions, with 48V and zonal design wins expected to drive 2027 growth.
- **Robotics:** sensor and motor control products began ramping.
- **Data converters:** the first large design win landed, with a ramp expected in 2027.
- **800V data centers:** in-house GaN solutions began sampling alongside SiC.
Bears still have legitimate ammunition. Storage and Computing fell 3.8% sequentially as memory shortages constrain notebooks, and management guided that segment only flattish to slightly up year over year. Rising foundry and wafer costs are being partly absorbed rather than passed through, which helps explain why gross margin gains are incremental rather than meaningful. Analog Devices' mPower acquisition raises a competitive question in integrated voltage regulators. 800V revenue is not expected until late 2027 or 2028. The growth mix is also concentrating: Enterprise Data and Communications together now exceed 57% of revenue. Inventory days on next-quarter revenue rose slightly to 117, and the channel is lean as the ramp continues.
The market setup is more complicated than the surprise implies. Shares peaked at $1,568.21 the day after the July report, then slid to an inter-earnings low of $1,126.57 on October 23. The stock closed at $1,211.22 before this release, 22.8% below that high and 7.5% below its 200-day moving average. Investor sentiment fell from modestly positive (0.09) to modestly negative (-0.09), a meaningful shift in expectations without being extreme. The internal trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative, which reflects a stock that has been sold despite improving numbers. Capital allocation offered some support. MPS repurchased $453.4 million of stock in Q3, which drew cash down to $1.09 billion from $1.41 billion, and the board added another $500 million authorization.
The Q4 guide midpoint of $1.35 billion implies sequential growth of roughly 12%. That is still strong but slower than Q3's 22.6% jump, so investors focused on the rate of change will notice the step down even as year-over-year growth continues to climb.
The bottom line is that MPS delivered an accelerating quarter, raised its key Enterprise Data target again, and laid out a capacity roadmap that signals confidence well into 2027. The skepticism priced into the stock appears tied to AI concentration, rising stock compensation, cost absorption, and competition, not to anything in the current results. For investors, the debate has shifted away from whether demand is real and toward how durable and profitable the AI-driven mix will prove as the company scales toward $10 billion of capacity.
Read our earnings preview for Monolithic Power Systems, Inc.: https://www.earningswhispers.com/article/MPWR/21220
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
Monolithic Power Systems Stock Passes Early Entry Amid High Demand For AI Tech
MPWR
Investor's Business Daily
|
