Intel's Data Center Surge Powers A Clean Q3 Beat, But A PC Collapse And Fab Shutdown Drive A Sharp Q4 Guide-Down
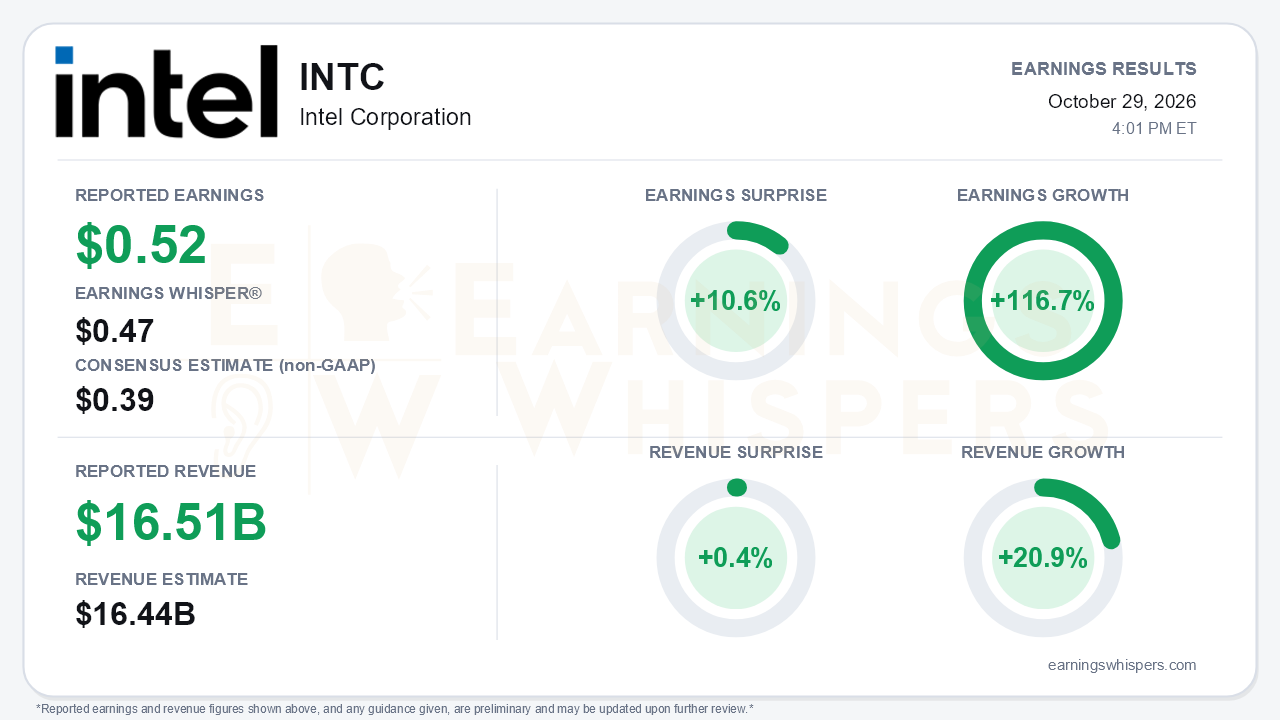
Intel delivered the beat investors expected and then guided to a quarter few were positioned for. Third-quarter non-GAAP EPS of $0.52 topped the $0.39 consensus and the $0.47 Earnings Whisper number, a 10.6% surprise. Earnings grew 116.7% year over year on revenue of $16.513 billion, which edged past the $16.44 billion consensus by 0.4% and rose 20.9%. Revenue, gross margin and EPS all exceeded Intel's own guidance. The central tension is the fourth-quarter outlook. Intel guided to $15.0 to $16.0 billion in revenue, a 38.0% non-GAAP gross margin and $0.25 in non-GAAP EPS, roughly half of what it just earned and below Street estimates. Data center is accelerating faster than at any point in 15 years, while the PC business and near-term margins are deteriorating faster than management signaled only a quarter ago.
The composition of the quarter deserves scrutiny because the segments diverged sharply. Data Center and AI revenue jumped 78% to $7.3 billion, up 17% sequentially. Its operating income more than tripled to about $3.0 billion, a segment margin near 42%. Intel Foundry revenue rose 58% to $6.7 billion, and its operating loss narrowed to $1.85 billion from $2.32 billion. Client Computing and Physical AI revenue fell 5% to $8.1 billion and dropped 9% sequentially, which management said was below plan. Non-GAAP gross margin expanded 4.1 points to 44.1%, against a 42% guide. GAAP EPS of $0.60 fell from $0.90, but the year-ago figure carried a $1.20 per-share Altera divestiture gain. This quarter's GAAP figure includes a $0.17 mark-to-market gain on escrowed shares tied to the U.S. government agreement. Per-share comparisons also absorb dilution: diluted shares rose to 5.31 billion from 4.53 billion after the $23 billion equity offering.
The call made the bull case on servers more expansive. Management raised its industry server CPU unit growth outlook to more than 30% for both 2026 and 2027, from "strong double-digit" last quarter. It framed the server CPU market as growing from roughly $40 billion to more than $200 billion over five years. Intel said DCAI revenue is now running about $10 billion above its start-of-year expectations, and it guided Q4 DCAI up mid-teens sequentially. Granite Rapids is now gross-margin accretive and Intel's largest server family. Clearwater Forest on 18A is shipping for revenue, and purpose-built silicon rose 50% sequentially with a goal of tripling again. Management now expects supply constraints to last through 2027 into 2028. That is a demand signal, but it also means server share depends on supply as much as on product strength against AMD and Arm.
The risks, however, all moved the wrong way at once. The PC outlook worsened to a roughly 12% market decline in 2026, with the second half down more than 20%, and a planned 10% decline in 2027. Management tied the slump to memory pricing and availability and does not expect memory relief in 2027. CCPG is guided down more than 20% sequentially. An accident and shutdown at Fab 28 in Israel will cost about $300 million in Q4 revenue and about 200 basis points of gross margin, with a similar revenue hit expected in Q1. The 38% margin guide breaks the "comfortably in the 40s" goal management set in Q2. Underutilized client and 18A factories, along with a dilutive purpose-built silicon mix, add further pressure. Free cash flow framing also slipped. Q3 adjusted free cash flow was $1.6 billion, but 2027 is now expected to be negative as capital spending rises "strongly." Equipment purchase orders were already up about 40% sequentially. Lip-Bu Tan's tone was noticeably more cautious, and he described himself as "disappointed."
Investors entered the report with tempered expectations. Earnings Whispers sentiment remained positive but weakened modestly, slipping to 0.19 from 0.25. Shares closed at $95.53 ahead of the release, down 4.8% from the open after the July report. They were also 25% below the September 24 inter-earnings high of $127.44, having already given back much of that rally. The stock still sits 10.6% above its 200-day moving average and well above the late-July low of $81.79. Earnings Whispers trend signals are mixed: sequential growth and momentum readings remain positive, while AVWAP is negative.
The bottom line is that Intel's data center turnaround looks more credible than ever, but it is not yet large enough to offset a collapsing PC market, a fab disruption and an investment cycle that will consume cash. The Q3 beat was genuine and the server narrative strengthened. The next two quarters, however, now carry lower revenue, sub-40% gross margins and diluted per-share earnings. Bears have legitimate ammunition in the guidance, and bulls now depend on Intel converting server demand into supply faster than PC weakness erodes profits.
Read our earnings preview for Intel Corporation: https://www.earningswhispers.com/article/INTC/21208
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours |
