PennyMac Mortgage Investment Trust Beats On Adjusted EPS, But A GAAP Loss, Book Value Erosion And A Planned Dividend Cut Define The Quarter
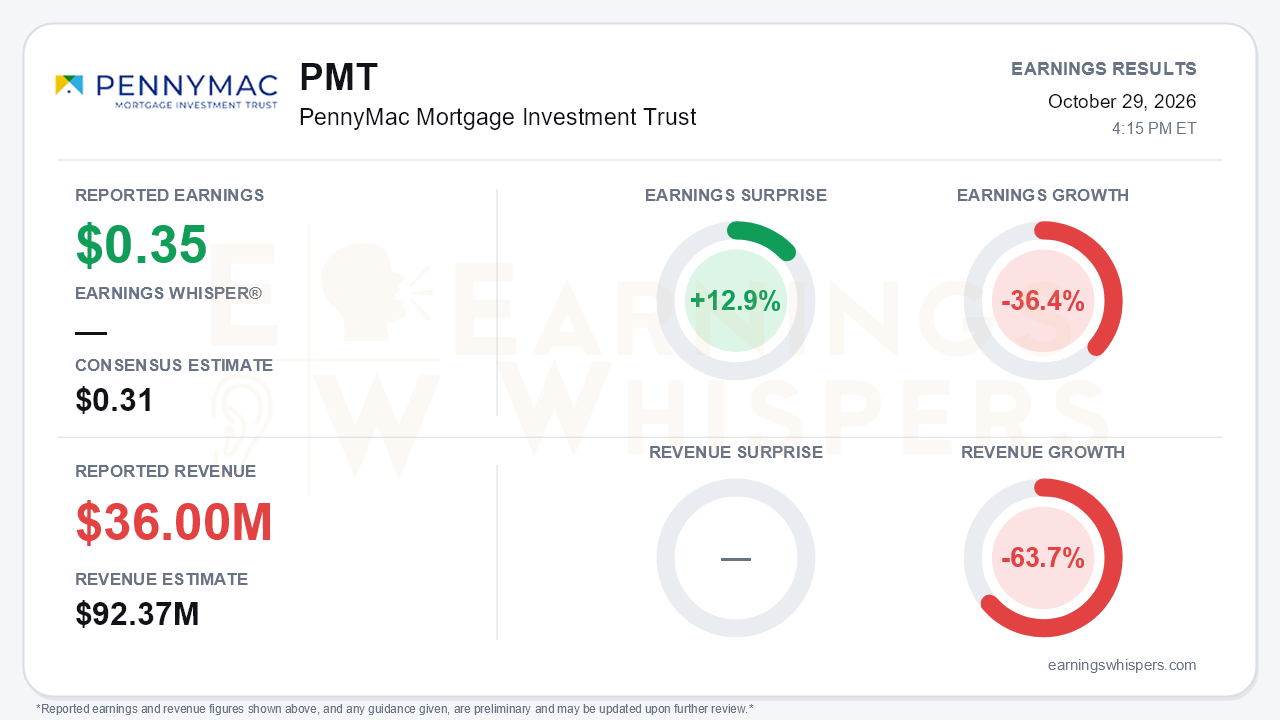
PennyMac Mortgage Investment Trust (NYSE: PMT) delivered a headline beat that tells only part of the story. Adjusted EPS of $0.35 topped the $0.31 consensus by 12.9%, but earnings still fell 36.4% year over year. Revenue, measured as net investment income, came in at $36.0 million, missing the $92.37 million consensus by 61.0% and falling 63.7% from a year ago. On a GAAP basis, PMT swung to a net loss of $36 million, or $(0.41) per share, from a $0.23 profit in the second quarter and $0.55 a year earlier. Book value per share fell about 5% to $14.03. The central tension is that core earnings power improved while the balance sheet absorbed another round of mark-to-market damage, and management responded by signaling a lower dividend.
The quality of the beat depends on which earnings stream investors trust. Wider mortgage spreads and sharply higher rates drove $54 million of pretax market-driven losses. Including tax effects, the gap between GAAP net loss and adjusted net income was $66 million, and the call attributed roughly 85% of that decline to spread widening. The damage was concentrated in the newer strategy. Subordinate bonds from PMT's own private-label securitizations lost $48 million, pushing the credit-sensitive segment to a $42 million pretax loss and a (41)% annualized ROE. The rate-sensitive segment moved the other way: income excluding market-driven changes climbed to $37 million from $20 million in the second quarter and $11 million in the first, as slower prepayments cut MSR cash-flow realization to $85 million from $100 million. Adjusted EPS has now improved for three straight quarters, from $0.13 in the fourth quarter of 2025 to $0.20, $0.25 and now $0.35. The adjusted ROE of 9%, however, still trails the 10% posted a year ago.
The strategic pivot accelerated. PMT has now sold or contracted to sell about $35 billion in UPB of agency MSRs, all at or near carrying value according to the call. That includes $13 billion closed in the quarter, a $10 billion agreement and another $12 billion signed after quarter end. Capital is being recycled into private-label securitization retained interests, which management expects to earn low-to-mid-teens ROEs. PMT completed eight securitizations totaling $2.9 billion in UPB, retained $167 million of investments (up from $120 million), and pushed retained PLS holdings above $1 billion. It also priced its inaugural non-QM DSCR deal after quarter end. Management raised its run-rate return potential to $0.38 per quarter (10.6% ROE) from $0.33 and reaffirmed full-year targets of about 30 securitizations and more than $600 million of retained investments.
Bears have legitimate ammunition, however. The quarter showed that the new portfolio is exposed to the same spread shocks that hurt the old one. The correspondent channel is shrinking quickly: acquisitions fell 53% sequentially to $1.2 billion, and conventional conforming volume nearly disappeared. Aggregation and securitization pretax income fell to $2 million from $11 million on lower volumes and jumbo/non-QM spread widening. Core leverage edged up to 6.5x from 6.2x, and consolidated debt-to-equity reached 13.9x as non-recourse securitization financing grew. Management said it expects to cut the dividend in favor of buybacks, and the call indicated a reduction to roughly $0.30 from $0.40. That is a reasonable alignment with $0.35 of adjusted EPS and a $0.38 run-rate, but it is still a cut. The board added $130 million to the repurchase authorization, lifting capacity above $200 million. Leadership is also changing: CFO Daniel Perotti hands off to Kevin Ryan on January 1, 2027, and President Doug Jones retires in mid-2027.
The market had largely priced in a difficult quarter. Shares closed at $7.27 ahead of the report, down 24.0% since the open after the July release. They sat 30.8% below the 200-day moving average and just 8.5% above the 52-week low of $6.70 set on October 19. At roughly half of book value, the buyback argument is mathematically compelling, which is exactly why management chose to redirect capital from the dividend. Investor sentiment remained firmly negative and was essentially unchanged, edging from -0.536 to -0.532. Price trend and AVWAP readings remain negative.
The bottom line is that PMT's core earnings engine is improving and the MSR-to-securitization rotation is moving faster than expected, but the quarter exposed how volatile book value remains in a widening-spread market. The adjusted beat and higher run-rate target give the story credibility. The GAAP loss, the planned dividend cut, rising leverage and management turnover explain why investors are not yet willing to pay up for that progress.
Read our earnings preview for PennyMac Mortgage Investment Trust: https://www.earningswhispers.com/article/PMT/21232
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-21 | |
| Oct-08 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-14 |
