The RealReal's Headline EPS Miss Obscures A Third Straight Beat-And-Raise As GMV Growth Accelerates To 23%
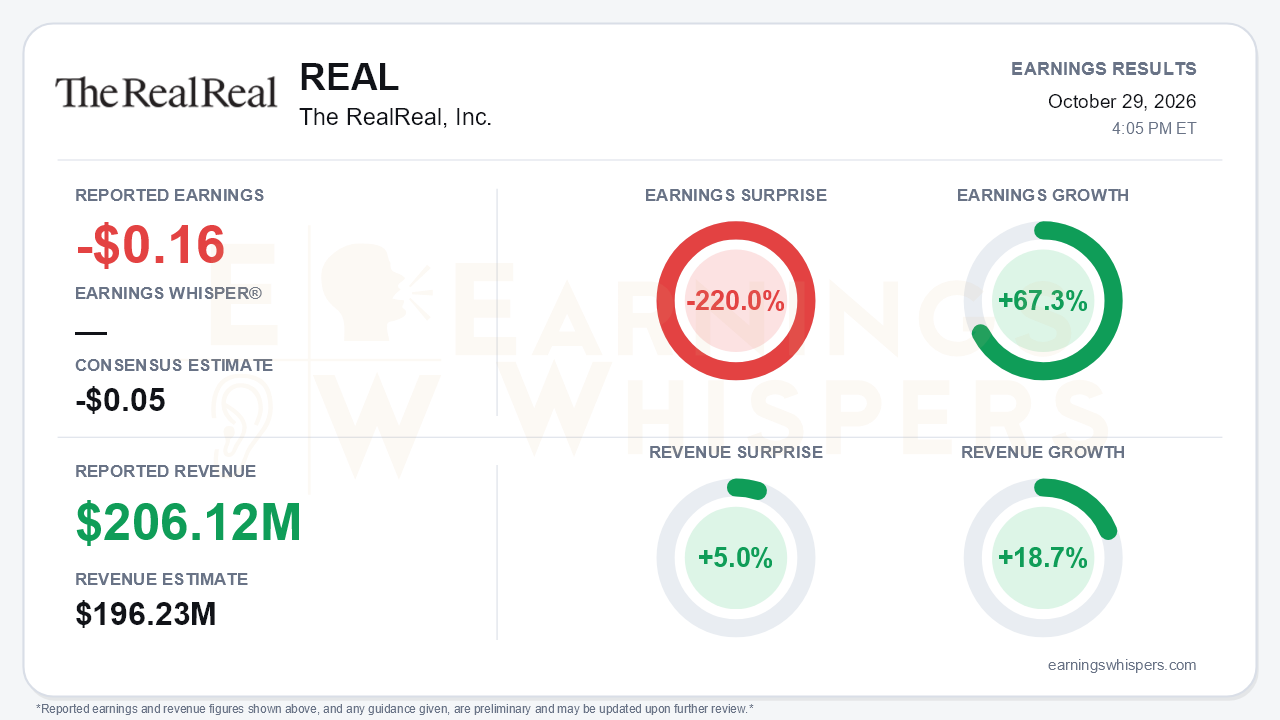
The RealReal (NASDAQ: REAL) posted a quarter where the headline earnings figure and the operating story point in opposite directions. Earnings Whispers recorded a loss of $0.16 per share against a consensus estimate of a $0.05 loss. That is a 220.0% miss, though earnings still improved 67.3% from a year ago. Revenue told a cleaner story. Sales of $206.12 million rose 18.7% and beat consensus of $196.23 million by 5.0%. They also cleared management's own $194-198 million guide. GMV of $642 million grew 23%, well ahead of the 17-19% the company had guided. Full-year targets were raised on every metric for the third consecutive quarter. That is the central tension: a per-share miss sitting on top of what was, operationally, one of the company's strongest quarters in years.
The per-share figures need careful handling because they diverge depending on presentation. The normalized $0.16 loss differs from each figure the company reported: GAAP basic EPS of $0.13, a GAAP diluted loss of $0.04, and non-GAAP EPS of $0.02. Reported net income of $16 million leaned heavily on a $21.2 million non-cash gain from remeasuring the warrant liability. Investors should not treat the GAAP profit as recurring. The more durable improvement sits higher in the income statement. Operating income turned positive at $1.5 million versus a $7.6 million operating loss a year earlier. Adjusted EBITDA nearly doubled to $17.0 million, an 8.3% margin, up 290 basis points and above the $13.5-14.5 million guide. Gross margin of 74.9% expanded 64 basis points. However, much of that came from shipping, where revenue rose about 21% while shipping costs were essentially flat. Management cautioned that this benefit was one-time and that gross margin should revert within a 73-75% range.
Beneath the headline, demand clearly accelerated. Orders rose 15%, up from 8% in the second quarter and the strongest growth since 2022. Trailing active buyers grew 13%, continuing a steady climb from 9%, 10% and 11% in the prior three quarters. New buyers grew more than 20%. On the supply side, consignors grew double digits, with 44% of new consignors coming from the buyer base. That flywheel underpins the company's pitch that it is becoming an 'operating system' for luxury ownership. The weaker thread is pricing and mix. AOV growth slowed to 8% ($629) from 13% in the second quarter and 15% in the first, as jewelry stopped over-indexing and mix shifted toward mid-value goods. Take rate recovered 90 basis points sequentially to 36.8% but remains about 110 basis points lower year over year. Marketing also deleveraged roughly 70 basis points, so some of the volume acceleration is being bought.
The forward catalysts are tangible:
- **Refinancing:** A new $150 million term loan and $25 million revolver maturing in 2033 should save roughly $4 million in annual interest. Management set a medium-term target of $150 million or less in total debt.
- **Automation:** The automated storage and retrieval system at Perth Amboy went live ahead of schedule and tripled units picked per hour.
- **AI and supply initiatives:** Ask TRR, the conversational shopping tool built with Google, is live, with early adopters spending 20% more per transaction. Japanese dropship vendors expanded from two to seven, adding more than $100 million of supply this year.
The risks are equally concrete:
- **Slowing fourth-quarter growth:** The guide implies GMV growth moderating to 17-19% and revenue growth to 12-14%.
- **Narrower margin gains:** EBITDA margin expansion implied for the fourth quarter is about 180 basis points, versus 290 basis points in each of the last two quarters.
- **Leverage:** The balance sheet still carries roughly $380 million of notes and a $354 million stockholders' deficit. Free cash flow of $11.3 million trailed the prior year's $13.7 million as capital spending more than doubled. No full-year free cash flow guidance was offered.
The market setup is more complicated than the beat-and-raise implies. Investor sentiment fell meaningfully into the report, from 0.20 after the August release to roughly neutral at -0.01, a notable cooling of expectations. Shares have slid 16.7% since opening at $13.62 after the prior report. At $11.35, the stock sits just 2.3% above its 200-day moving average of $11.09, having surrendered much of the enthusiasm that followed the last quarter. The Earnings Whispers AVWAP reading remains positive while price trend is neutral. That mix fits a stock that has cooled without breaking down.
The bottom line is that The RealReal delivered accelerating volume, a raised outlook and a de-risked debt maturity profile, but the quarter is not as clean as the revenue beat suggests. Bears have legitimate ammunition. The normalized EPS miss, reliance on a warrant gain for GAAP profit, one-time shipping benefits, slowing AOV and a guide that implies fourth-quarter deceleration all count against the story. Still, the call preserved a credible growth-and-deleveraging narrative, and with sentiment reset to neutral, expectations are considerably lower than the fundamentals alone would imply.
Read our earnings preview for The RealReal, Inc.: https://www.earningswhispers.com/article/REAL/21236
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Sep-19 | |
| Sep-16 | |
| Sep-09 | |
| Aug-25 |
