Tarsus Must Show Xtemvi Can Outrun Its Pricier Retina Ambitions In Q3
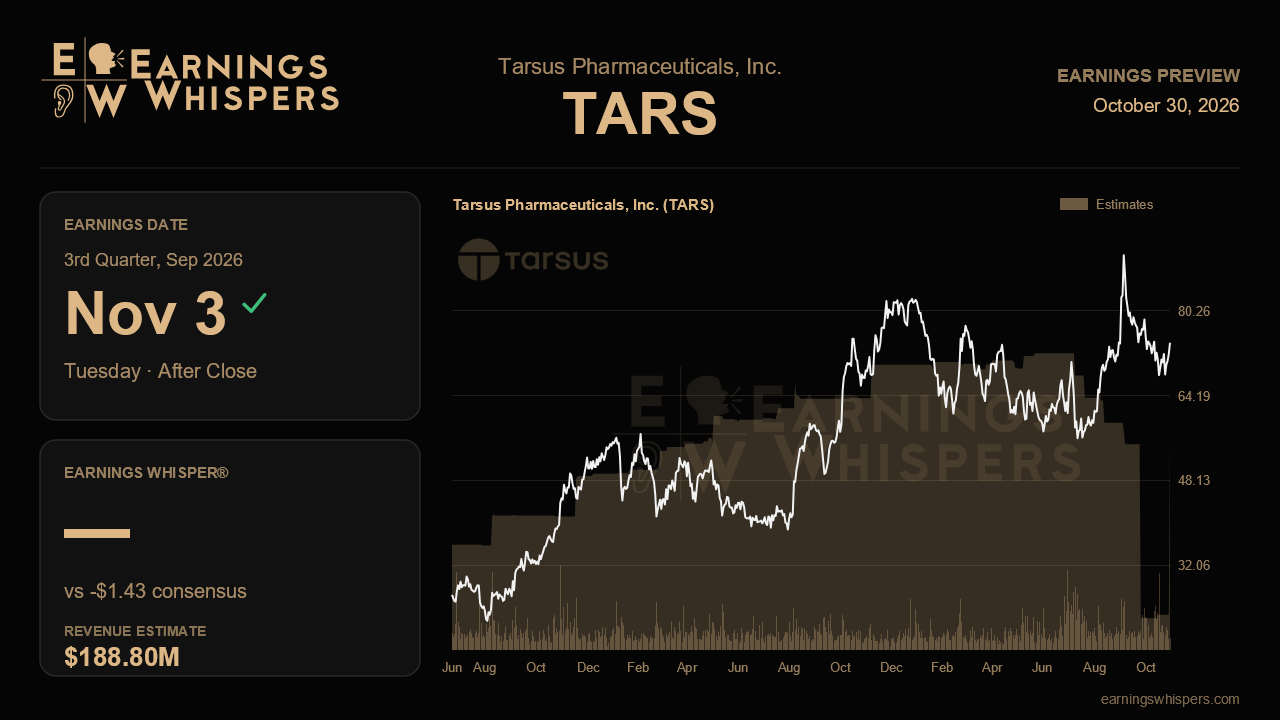
Tarsus Pharmaceuticals heads into its third-quarter report with two stories running at once. The commercial engine behind Xtemvi, its eyelid treatment for Demodex blepharitis, keeps gaining speed. Meanwhile, management has started spending that success on a retina pipeline whose payoff sits years away. This quarter tests whether the first story stays strong enough to carry the cost of the second.
Wall Street expects revenue of about $188.8 million, up roughly 59% from $118.7 million a year ago and about 9% above the record $173.9 million posted last quarter. That is still robust growth, though slower than the 69% pace of the second quarter. The bottom line looks far worse. Consensus calls for a loss of $1.43 per share, compared with a $0.30 loss a year earlier and a $0.43 loss last quarter. The likely cause is deal-related spending tied to the Alkeus and Irenix acquisitions rather than any weakness in the core business. Management had already lifted R&D guidance to $190 million to $210 million to absorb the $75 million Irenix upfront payment, and that range did not yet include the $450 million Alkeus deal. Investors should therefore read the headline loss with care and focus on what it reveals about the run rate of ongoing spending.
The more telling comparison is with sales guidance. Last quarter Tarsus raised its full-year Xtemvi target to about $685 million or more. It was the company's first increase since it began issuing annual guidance. First-half sales totaled roughly $319 million, so a third quarter in line with consensus would leave only about $177 million needed in the fourth quarter to reach the floor. That would be less than the third-quarter estimate itself. The guidance therefore looks conservative, and the Street is effectively positioned above it. A quarter near $189 million would keep the door open for another raise. A shortfall, especially one paired with an unchanged outlook, would suggest the second-quarter jump pulled demand forward rather than marking a new base.
The demand indicators management highlighted last quarter are the evidence to check. Retreatment rates rose from the low-to-mid teens to the high teens and are tracking toward a steady state of about 20%. Unaided awareness of the condition reached about 30%, and the number of near-daily prescribers doubled over the past year. Confirmation that retreatment is nearing 20% would show the franchise is building a recurring patient base rather than relying only on new patients. Gross margin has held near 93% for four straight calls and should stay there. Any slippage would raise questions about pricing or mix. The departure of the chief commercial officer, with an interim leader in place, adds another reason to look for steady execution in the field.
The retina pivot brings its own checklist. Investors will want updated R&D and operating expense guidance that includes Alkeus. They will also want clarity on whether profitability, which management targeted for around 2027, slips by only the quarter or two it flagged. The balance sheet matters too. Cash stood near $450 million before the $270 million cash portion of the Alkeus payment, partly offset by a $125 million private placement. Progress on hiring a 50- to 75-person retina sales force will show how quickly costs ramp ahead of a Stargardt readout not expected until the second half of 2029.
The market has clearly bought the expansion thesis. Shares have climbed nearly 29% since the last report while the S&P 500 was flat, and sentiment has swung from modestly bearish to fairly bullish. Still, at $74.20 the stock sits well below its post-earnings high of $91.53, though comfortably above its 200-day average near $67.82. That pattern suggests some of the early enthusiasm has already been tested. In the end, the report turns on whether Xtemvi growth is strong enough, and guidance confident enough, to make a long-dated and costly retina bet look affordable rather than distracting.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-15 | |
| Sep-29 | |
| Sep-04 | |
| Sep-01 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-13 |
