Tarsus Beats As XDEMVY Guidance Rises Again, But A $632 Million Pipeline Bet Reshapes The Balance Sheet
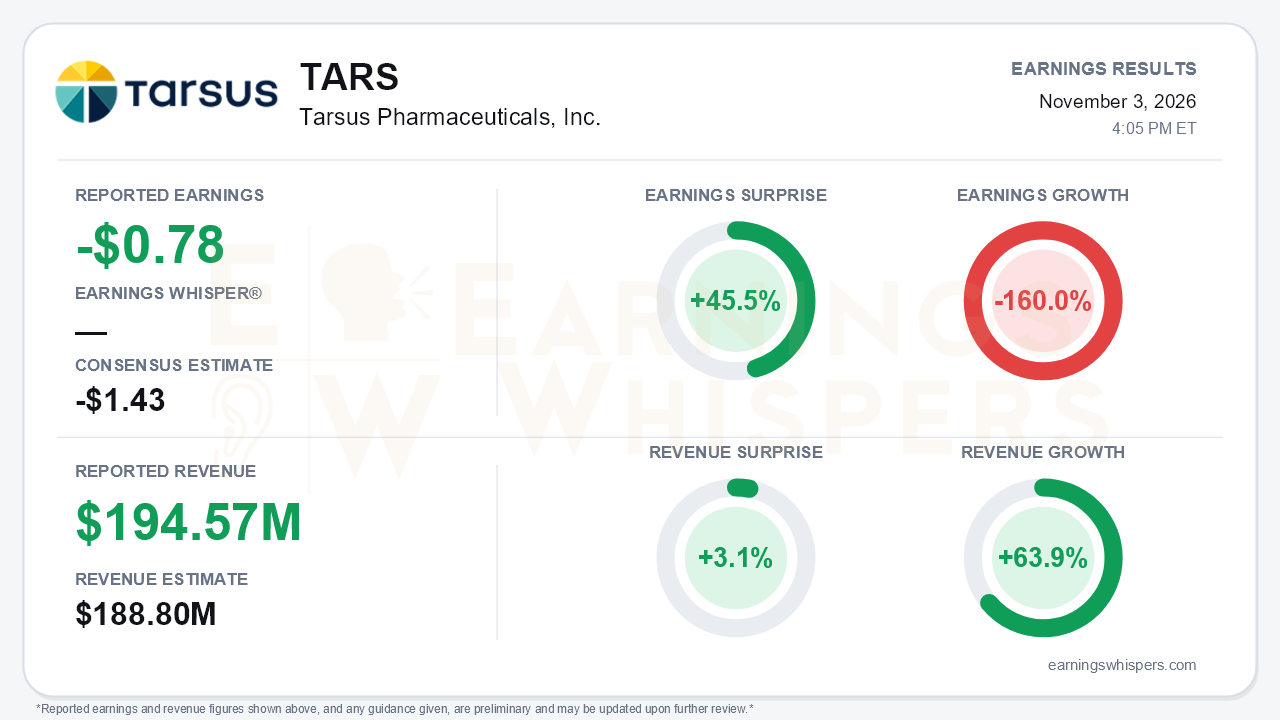
Tarsus Pharmaceuticals delivered the kind of commercial quarter that keeps the XDEMVY growth story intact. On Earnings Whispers' normalized basis, the company lost $0.78 per share, well ahead of the -$1.43 consensus, a 45.5% surprise. Revenue of $194.57 million beat the $188.8 million estimate by 3.1% and grew 63.9% year over year. The headline beat, however, is not the most important development. Tarsus raised full-year XDEMVY guidance for the second straight quarter while committing heavily to a retina pipeline through two acquisitions. That changed the cost structure, the cash position and the risk profile at the same time.
The GAAP picture looks nothing like the normalized one. Tarsus reported a GAAP net loss of $668.3 million, or $(14.40) per share, compared with $(0.30) a year ago. The difference is driven by $632.2 million of acquired in-process R&D expensed for iRenix ($81.0 million) and Alkeus ($551.2 million). Even the normalized loss widened from last year, which explains the 160.0% year-over-year earnings decline. Spending is outrunning gross profit:
- **R&D** rose to $44.2 million from $16.3 million.
- **SG&A** climbed to $168.0 million from $108.6 million. About $23.5 million of that was Alkeus transaction and integration cost, but $11.7 million reflected stepped-up commercial and direct-to-consumer (DTC) investment.
Gross margin held at roughly 93%, and revenue growth benefited from both volume and gross-to-net improvement. The franchise itself is not the problem.
Under the hood, demand trends were stronger than the seasonal backdrop suggested. Management had guided to more tempered third-quarter growth, yet sales rose about 12% sequentially from $173.9 million. Other demand indicators also improved:
- **Weekly scripts** reached all-time highs, with momentum carrying into the fourth quarter.
- **Daily prescribing eye care professionals** rose about 20% during the quarter.
- **DTC high-value actions** jumped 75%, versus 19% in the second quarter.
- **Retreatment** climbed to roughly 20% of prescriptions, up from high teens in Q2 and mid-teens in Q1. Management lifted its steady-state retreatment outlook to the low 20s, an important durability signal for a drug once viewed as a one-course therapy.
Fiscal 2026 guidance moved to $715-$730 million from roughly $685 million at the low end after the second quarter. With $513.9 million in product sales through September, the new range implies a fourth quarter of roughly $201-$216 million.
Growth is still decelerating, though. Year-over-year growth slowed from 85% in Q1 to 69% in Q2 to 64% in Q3. That is natural at this scale, but analysts on the call flagged that consensus already implies a sharp slowdown after 2027. Management is leaning harder on spending to sustain the curve:
- **DTC spend** is now expected at about $95 million versus $80 million originally planned.
- **SG&A guidance** jumped to $605-$620 million from $545-$565 million.
- **R&D** is guided to $140-$155 million.
The quality of the guidance raise deserves scrutiny in that light. Incremental revenue is being purchased with incremental expense, and the profitability path discussed in the second quarter looks pushed back.
The forward-looking ledger has real weight on both sides.
Catalysts:
- **TP-04 (ocular rosacea)** and **TP-05 (Lyme prevention)** Phase 2 readouts remain on track for the first half of 2027. TP-05 enrollment is complete.
- **IRX-101** is set to begin Phase 3 in the first half of 2027, with management estimating $20-$30 million to approval.
Risks:
- **Gildeuretinol** carries a $150-$200 million cost to approval and topline data not expected until 2029. The FDA may require a second Phase 3, a competitor is ahead, and protection rests on orphan exclusivity rather than composition-of-matter patents.
- **Ex-U.S. retreat:** Tarsus deferred TP-03 filings in Europe and Japan because of most-favored-nation pricing concerns, reversing an earlier plan for 2027 European approval.
- **Competition:** a rival topical eyelid cream for Demodex blepharitis is in Phase 2.
- **Balance sheet:** cash and investments fell to $309.6 million from $449.7 million at the end of the second quarter. Shares outstanding rose to 49.3 million from 42.6 million at year-end, and stockholders' equity shrank to $104 million.
Investor sentiment shifted meaningfully into the print, moving from modestly negative (-0.107) to modestly positive (+0.186). Price action was far more dramatic. Shares opened at $57.63 after the August report, which proved to be the inter-earnings low. They then surged to a 52-week high of $91.53 on September 4 and gave back much of that move. Entering earnings at $73.32, the stock was still up 27.2% since the prior report and about 8% above its 200-day moving average, but nearly 20% below the September peak. The Earnings Whispers trend readings lean positive, with sequential growth, momentum and AVWAP all constructive. Even so, the retreat from the high suggests investors were already weighing the acquisition costs against the commercial strength.
The bottom line is that XDEMVY is executing better than expected. Rising prescribers, deepening retreatment and two consecutive guidance raises support a credible growth franchise. What has changed is the investment setup around it. Tarsus has converted a near-profitable single-product story into a cash-consuming, multi-asset pipeline bet with long-dated retina risk, a shelved ex-U.S. opportunity and decelerating percentage growth. Bulls have a clean commercial beat to point to. Bears have legitimate ammunition in the balance sheet and the spending trajectory.
Read our earnings preview for Tarsus Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/TARS/22516
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-15 | |
| Sep-29 | |
| Sep-04 | |
| Sep-01 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 |
