TSS Needs Procurement Rebound And Vera Rubin Progress To Win Back A Skeptical Market
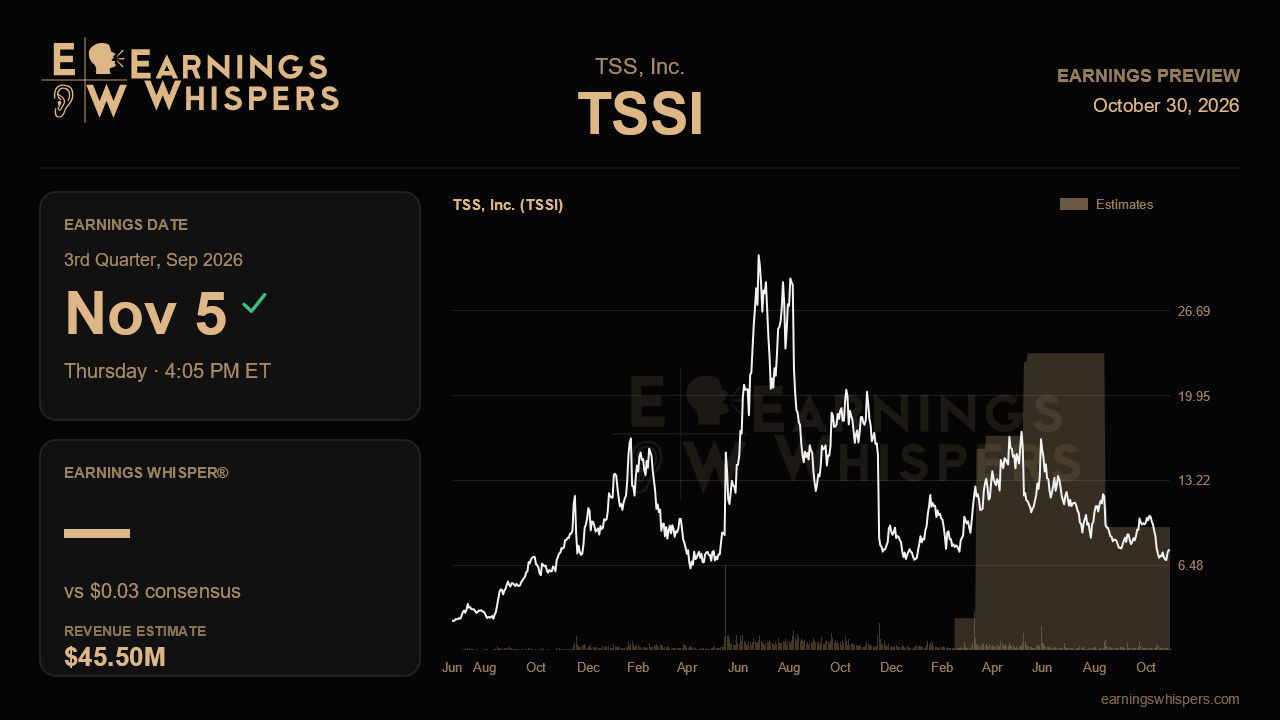
TSS heads into its September-quarter report with a split personality. The business management described three months ago looks healthier than ever, with margins expanding and higher-value integration work taking a bigger share of revenue. The stock tells a different story. Shares have fallen 17.3% since the last report, trailing the S&P 500 by about 16 percentage points. The results due after the close on November 5 need to show that last quarter's revenue slump was a timing hiccup and not the start of something worse.
The Street expects earnings of $0.03 a share on revenue of $45.5 million. That would be a sharp turnaround from a $0.06 loss a year ago, and revenue would rise 8.6%, which is modest growth. The bigger jump is sequential. Revenue would have to climb roughly 30% from the June quarter's $35.1 million. That rebound depends mostly on procurement, the low-margin pass-through business that collapsed to $18.2 million last quarter, well below its usual $30 million to $40 million range. Management called it a timing issue and said third-quarter orders were already running ahead of the second quarter. Those comments are the main reason the revenue target looks reachable. If procurement does not return to its normal range, the revenue estimate is probably out of reach.
The earnings estimate is less demanding. Consensus EPS sits below last quarter's $0.05 even though revenue is expected to be higher. That likely reflects a richer procurement mix, which dilutes margins, along with depreciation from new capacity and a full statutory tax rate that now hits net income. The better profitability gauge is adjusted EBITDA. Management narrowed its full-year outlook toward the upper end of a $20 million to $22 million range and said the second half should be stronger than the first. Holding that target after the June quarter's $4.5 million result requires a meaningful step up. Any retreat from that upper-end language would undercut the company's central argument that earnings quality is improving.
Systems integration is the segment to scrutinize. It grew 46% year over year last quarter and made up 39% of revenue. Sequentially, though, it has stalled around $14 million for three straight quarters. Management pointed to softer networking racks and to shortages of memory and cables as the limits on growth. The company says it is now handling significant GB300 volume. Investors should look for integration revenue to finally break out of that range, and for its gross margin to recover from 31.6% as depreciation at the Georgetown facility is absorbed. A related warning sign is the weekly minimum volume commitment, which had been exceeded only once or twice this year. That suggests capacity is still waiting for demand to fill it.
Several newer catalysts should also show up in this report. The warehousing and logistics service for TSS's largest customer, which began May 1, should contribute for a full quarter. The roughly $17 million build-out to prepare for NVIDIA's Vera Rubin platform was scheduled to finish in mid-September. Confirmation that it is complete and on track to produce recurring, higher-margin revenue in the fourth quarter would carry real weight. Updates on the modular data center installation planned for September or October, and on the sales team reorganization, would add evidence that the pipeline is broadening beyond a single dominant customer.
The market is pricing in skepticism. Sentiment has swung from 15.7% bullish before the last report to 29.8% bearish now. At $7.63, the stock sits well below its 200-day average of $10.89 and near the bottom of its post-earnings range of $6.78 to $10.66. That entire range sits beneath the prior quarter's low of $8.66. Expectations are low enough that a clean procurement rebound paired with reaffirmed EBITDA guidance could change the conversation. The core question is whether integration volume can grow again once supply constraints ease. If it can, the margin story holds up. If integration stays flat, the improvement looks more like a temporary mix effect than lasting growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-06 | |
| Sep-21 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Jul-30 | |
| Jun-04 | |
| May-08 | |
| May-07 | |
| May-01 | |
| Apr-28 | |
| Mar-11 |
