TSS Breaks Its Systems Integration Plateau And Raises Guidance, But A Steep Q4 Ramp And Sector Fears Keep Shares Near Lows
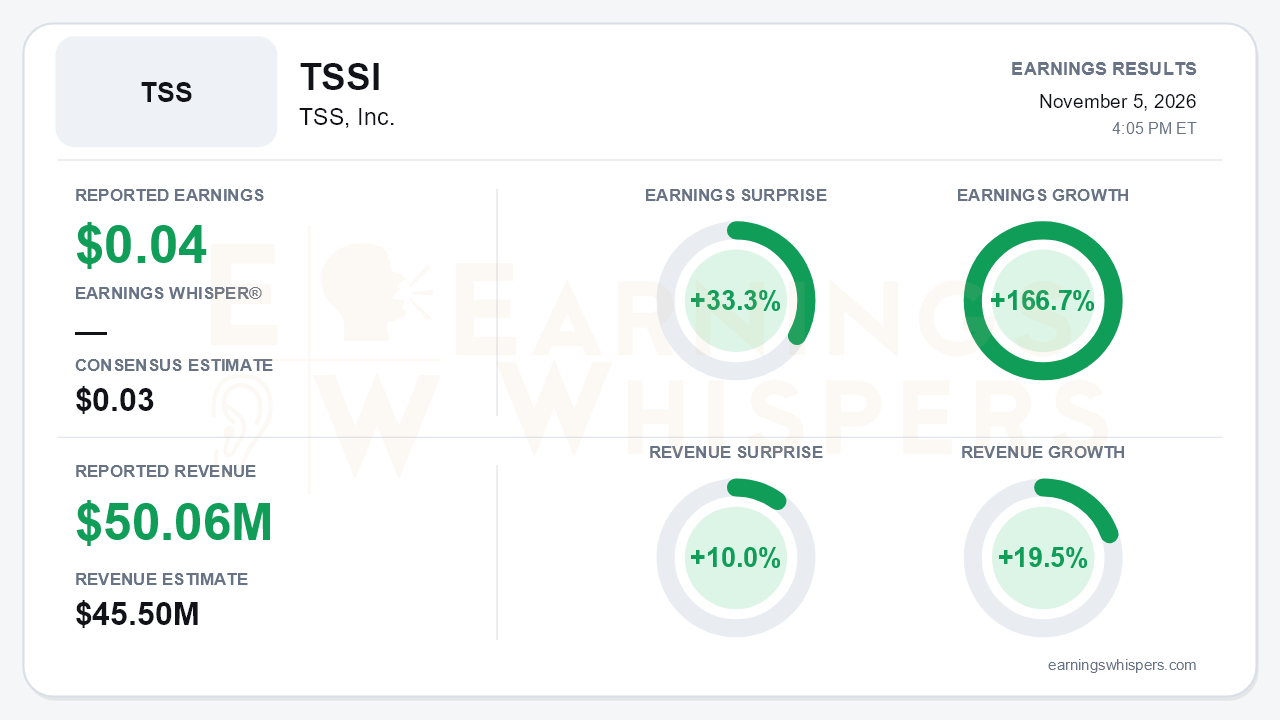
TSS, Inc. (NASDAQ: TSSI) delivered its cleanest quarter of the year. Third-quarter earnings of $0.04 per share beat the $0.03 consensus by 33.3%. Revenue of $50.06 million topped the $45.5 million estimate by 10.0%. Earnings grew 166.7% year over year, a swing from a $0.06 loss a year ago to a profit, and revenue grew 19.5%. That growth is a sharp reversal from the second quarter, when revenue of $35.1 million was down 20% year over year. The central development is not the penny beat. Systems Integration, the higher-margin business the bull case depends on, finally broke out of a three-quarter stall. Management followed with the first formal guidance raise of 2026.
The quality of the quarter is better than the small EPS figures suggest. Systems Integration revenue hit a record $16.1 million, up 75% year over year and 16% sequentially. It had sat near $14 million in each of the prior three quarters ($14.2 million, $14.1 million and $13.9 million). Segment gross margin expanded to 35.4% from 31.6% in Q2 and just 12.9% a year ago. Blended gross margin rose to 17.2% from 11.1%, and gross profit climbed 86% to $8.6 million. Adjusted EBITDA reached $4.7 million, up 225%, and SG&A fell to 71% of gross profit from 113%. GAAP results also reflect a full tax provision following last year's release of the deferred-tax valuation allowance. Interest income of $0.6 million and a $0.3 million asset-disposal loss sit below an operating profit of just $1.2 million. The quarter is improving, but the GAAP earnings base remains thin.
The call explains why management sounded more emphatic. Racks processed rose 248% year over year and 57% sequentially. Both AI racks and mainstream CPU, network and storage racks grew, with mainstream recovering after a Q2 dip. The company exceeded its minimum weekly volume commitments "more consistently," versus "once or twice" year-to-date as of the second quarter. Management described a demand signal "larger than it's ever been" and said it could double or triple integration capacity within its current facility. Procurement rebounded to $32.4 million from $18.2 million in Q2, as guided.
The secondary metrics are less flattering. Procurement non-GAAP margin slipped to 5.0% from 6.0% in Q2. Facilities Management revenue fell 30% to $1.1 million as older modular data centers were decommissioned and earlier project work rolled off.
The forward catalysts are tangible but carry tradeoffs:
- **Georgetown warehouse:** The seven-year, roughly 380,000-square-foot lease is backed by a matching seven-year warehousing services agreement with TSS's largest customer. The first 126,000-square-foot building was occupied in October, with full use expected in 2027. Because the warehousing is outsourced third-party logistics, management acknowledged it will dilute Systems Integration margins.
- **Vera Rubin readiness:** About $14 million of an expected $17 million to $18 million in capex has been placed into service. A contract amendment and incremental revenue are expected starting in Q4. However, Vera Rubin volume has been pushed toward December or January as the customer prioritizes other products.
- **Modular data centers:** A new deployment is planned for Q4, a larger one for 2027, and management hinted at strategic news "soon."
The investment build is draining cash. Cash fell to $54.0 million from $67.7 million in Q2 and $85.5 million at year-end, while deferred revenue collapsed from $13.9 million to $2.1 million. Customer concentration remains acute.
Guidance is the key judgment call. The full-year adjusted EBITDA outlook rises to $21 million to $23 million from the upper end of $20 million to $22 million. That is a modest raise in dollar terms. Against $14.5 million year-to-date, it implies roughly $6.5 million to $8.5 million in Q4, a steep step up from $4.7 million. Management cited pipeline visibility for further fourth-quarter growth. Bears will note that this target depends partly on a Vera Rubin ramp that has already slipped.
The market setup is far more pessimistic than the fundamentals. Investor sentiment, measured before the report, swung from a mildly positive 0.16 to -0.26. That is a meaningful deterioration rather than noise. Shares at $6.85 are down 25.7% since the open following the August report and sit 36.5% below the 200-day moving average. The stock slid about 36% from its October 6 high of $10.66 to a 52-week low of $6.53 on November 4, the day before results. Analysts tied part of that selloff to data center moratorium and political concerns across the sector; management said it has seen no impact. The Earnings Whispers price and AVWAP trend readings remain negative, consistent with a stock still under distribution.
The bottom line is that TSS delivered what skeptics questioned: a Systems Integration breakout, expanding margins, higher volume commitments and a guidance raise. Yet the stock entered the print near its lows on sector fears rather than company-specific misses. Whether the operating story can reassert itself depends on executing the implied Q4 EBITDA ramp, getting Vera Rubin volumes moving and managing warehousing-driven margin dilution while cash declines.
Read our earnings preview for TSS, Inc.: https://www.earningswhispers.com/article/TSSI/22538
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-30 | |
| Oct-06 | |
| Sep-21 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Jul-30 | |
| Jun-04 | |
| May-08 | |
| May-07 | |
| May-01 |
