TDS Must Show Its Fiber Surge Can Outrun A Faster Copper And Cable Slide
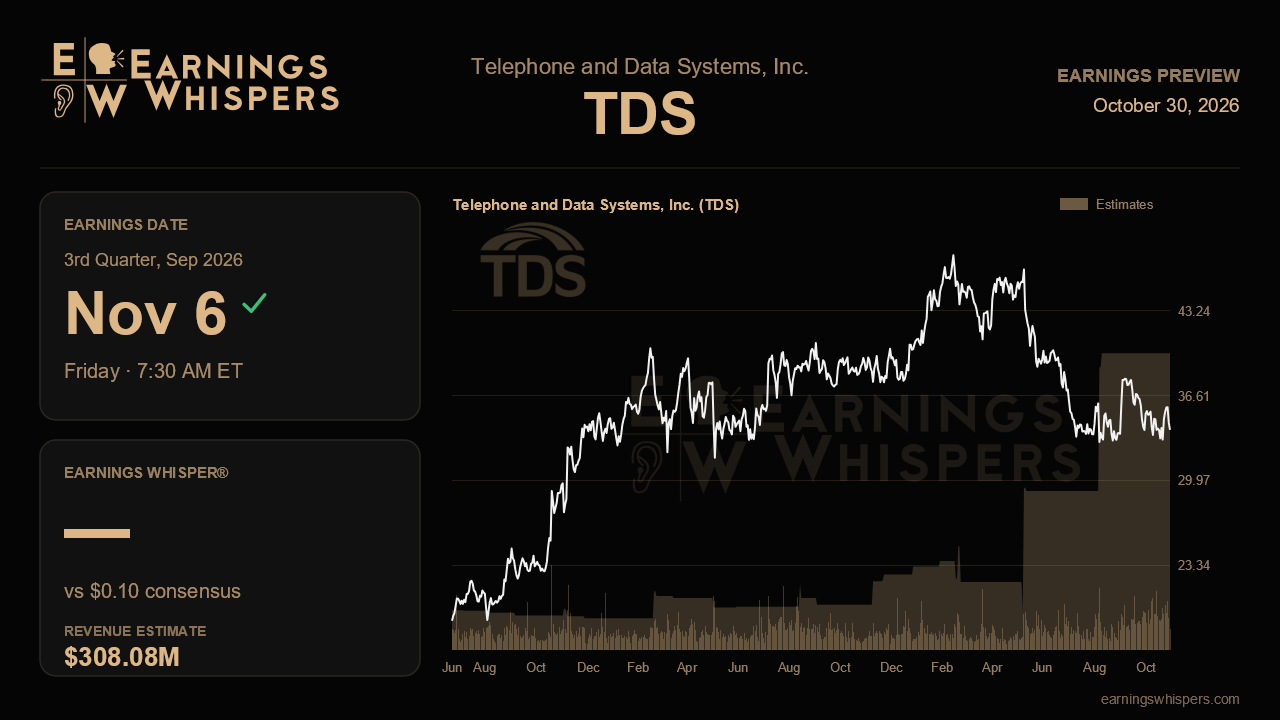
Telephone and Data Systems heads into its third-quarter report with two stories pulling in opposite directions. Last quarter, management raised its fiber build target, lifted capital spending and boosted nearly every Array tower forecast, yet it also cut TDS Telecom's revenue outlook as copper and cable customers left faster than expected. The November 6 release, due before the open, is the first real check on whether the acceleration in fiber is durable enough to matter more than the erosion underneath it.
The Street is not asking for much on the top line. Consensus calls for revenue of about $308.1 million, essentially flat with the $308.5 million posted a year ago and a touch below last quarter's $309.3 million. Earnings are expected at $0.10 per share, up roughly 43% from $0.07, though the low base makes that growth rate look more impressive than it is. The comparison with last quarter's $2.24 is not meaningful, since that period coincided with Array closing its $1 billion Verizon and $168 million T-Mobile spectrum sales. This quarter should offer a cleaner look at the underlying operations.
The fiber build is the centerpiece. TDS Telecom delivered 66,000 marketable fiber addresses in the second quarter, up from 40,000 in the first, bringing the first-half total to 106,000. With full-year guidance now at 250,000 to 300,000, the company needs roughly 144,000 to 194,000 more in the back half, so a third-quarter figure meaningfully above 66,000 would suggest the raised target is well within reach. Management said construction is not limited by capital and pointed to record crew counts, which raises the bar: a step back in deliveries would be hard to explain. Residential fiber net adds, which grew 47% last quarter after 32% in the first, are equally important because addresses only create value once they fill with paying customers. The pending Granite State Communications deal, adding about 11,000 fiber addresses, was slated to close this quarter and should be confirmed.
The counterweight is legacy decline. Telecom revenue fell 6% last quarter, or 4% excluding divestitures, versus 3% in the first quarter, and cable revenue was running down about 10%. Management narrowed adjusted EBITDA guidance to $310 million to $330 million, effectively trimming the top end because those losses flow almost straight to profit. If revenue declines widen again, or if EBITDA trends toward the bottom of that range, it would challenge the idea that fiber growth can stabilize the business while capital spending climbs to $625 million to $675 million.
Array offers a steadier source of validation. Its tenancy ratio rose to 0.98 from 0.96, cash site rental revenue jumped sharply, and adjusted OIBDA guidance was raised to $60 million to $75 million. Continued tenancy gains and reaffirmed guidance would support management's confidence, while any update on remaining C-band value or the minority buy-in offer could shift attention quickly. That pending offer has frozen the $520 million buyback, removing a source of support for the shares.
The market has not given management much credit. The stock has slipped 3.7% since the last report, trailing a roughly flat S&P 500, and at $33.92 it sits well below its 200-day moving average of $39.66 and in the lower half of its post-earnings range. Sentiment has cooled to 22.8% bullish from 30.9% a quarter ago. That leaves a modest bar. The verdict likely hinges on one question: whether fiber deliveries and net adds keep accelerating fast enough to make the shrinking legacy base look like a fading drag rather than a widening one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Sep-18 | |
| Sep-01 | |
| Aug-19 | |
| Aug-19 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-31 |
