TDS Beat Leans On Below-The-Line Items As Telecom Guidance Is Cut Again And Fiber Capex Jumps To $750 Million
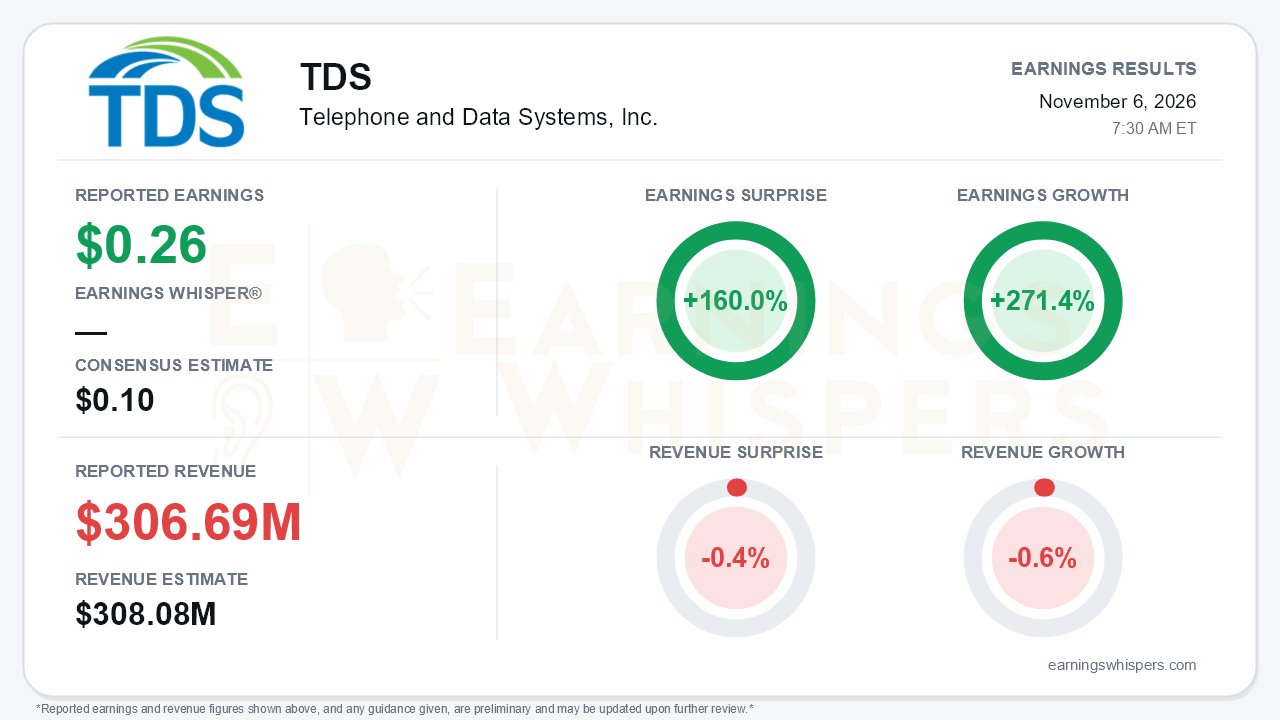
Telephone and Data Systems (NYSE: TDS) reported third-quarter earnings of $0.26 per share, beating the $0.10 consensus by 160.0%. Earnings Whispers measures year-over-year earnings growth at 271.4%. Revenue of $306.69 million missed the $308.08 million consensus by 0.4% and slipped 0.6% from a year ago. The beat is real, but it did not come from the operating business. TDS Telecom cut its full-year guidance for the second straight quarter and raised capital spending sharply, and that is the central tension. The company is spending heavily on a fiber build that is clearly gaining traction, while the legacy business it is replacing is eroding faster than management expected.
The quality of the beat deserves scrutiny. Consolidated operations lost $30.0 million in the quarter. Pretax income of $34.0 million came from below the operating line:
- $41.4 million of equity earnings from unconsolidated wireless partnerships, down 41% year over year;
- $22.0 million of interest and dividend income on a cash pile swollen by spectrum proceeds;
- $7.7 million of imputed spectrum lease income.
A $25.9 million income tax benefit then lifted net income from continuing operations to $59.9 million. The release's own GAAP comparison also differs from the normalized growth figure. Diluted EPS from continuing operations fell to $0.26 from $0.33 in the release, a decline that reflects lower equity earnings and a smaller tax benefit than a year ago. Investors should recognize that the 271.4% growth figure and the reported GAAP decline are measuring different things.
The operating picture at TDS Telecom is weaker:
- Segment revenue fell 3%.
- SG&A rose 7%.
- The operating loss widened to $17.5 million from $8.3 million.
- Adjusted OIBDA dropped to $63.5 million from $77.0 million.
The segment detail tells the story. Expansion-market revenue grew 22% and residential fiber revenue rose 14%. Those gains were swamped by declines elsewhere:
- incumbent revenue down 8%;
- cable down 7%;
- commercial down 5%;
- wholesale down 9%.
Management now guides Telecom revenue to $990-$1,010 million, down from $1,000-$1,025 million, and adjusted OIBDA to $280-$300 million, down from $300-$320 million. That follows a second-quarter revenue cut and a lower top end for EBITDA. Capital expenditures move to roughly $750 million from $625-$675 million. Third-quarter capex alone was $251 million, against $102 million a year earlier.
The fiber engine itself is accelerating, and that preserves a credible growth story:
- TDS added about 76,000 marketable fiber addresses, up from 66,000 in the second quarter and 40,000 in the first.
- Residential fiber net adds reached 16,700, versus 15,100 last quarter and 11,200 a year ago.
- Fiber churn improved to 1.3% from 1.5% a year ago.
- Residential revenue per connection edged up to $66.88.
The headline broadband growth is flattered, however. The 7,200 residential broadband net adds include 4,700 connections from a September acquisition, leaving modest organic growth. Copper connections have collapsed to 71,100 from 102,000 a year ago. Year-to-date address delivery of roughly 182,000 also leaves a heavy fourth-quarter lift if the company is to reach the 250,000-300,000 target set in the second quarter. That target was not restated in the release.
No TDS-specific conference call transcript was available for this analysis. The available call material was a T-Mobile conference appearance and offers only indirect context. T-Mobile described upcoming C-band and 2.7 GHz auctions and signaled price discipline in spectrum purchases, which matters for Array's remaining spectrum monetization. One risk carried over from the second quarter is now outdated. The pending Array minority buyout that had restricted repurchases ended when TDS withdrew the offer on September 1.
Array continues to improve:
- Site rental revenue rose 14%.
- Colocations grew sequentially to 4,372.
- Adjusted OIBDA climbed to $18.3 million from $6.1 million.
- Full-year guidance was reaffirmed.
- Remaining spectrum sales received regulatory approval in October, though closings still await FCC finality.
The capital return story is now front and center. TDS bought roughly 6 million shares in the quarter at an average of $36.65. It has repurchased nearly 15 million shares this year for more than $520 million, and the board added a $250 million authorization. Corporate cash of about $1.4 billion supports that program. Consolidated free cash flow, however, was a negative $472.8 million through nine months as the fiber build consumes capital.
The market has not rewarded the repurchases:
- Shares closed at $32.36 ahead of the report, below the average buyback price.
- The stock is down 8.1% since the open following the prior report.
- It sits 17.9% below its 200-day moving average.
- Shares peaked at $38.41 on September 8, shortly after the Array offer was withdrawn, then set a 52-week low of $30.71 on October 21.
- The stock entered earnings just 5.4% above that low.
Investor sentiment was essentially unchanged, edging from 0.31 to 0.30, and remains modestly positive. That steadiness is notable given the price weakness.
The bottom line is that the EPS beat says little about TDS Telecom's operating trajectory. Fiber execution is improving on addresses, net adds and churn, and Array is becoming a cleaner tower business. However, the legacy decline is still outrunning fiber growth, segment profitability is shrinking, and guidance has now been lowered twice while the capital bill keeps rising. Bears have legitimate ammunition in the guidance cuts and negative free cash flow. Bulls can point to the cash-funded buyback and accelerating fiber metrics. Until Telecom OIBDA stabilizes, the investment case rests more on capital allocation than on earnings power.
Read our earnings preview for Telephone and Data Systems, Inc.: https://www.earningswhispers.com/article/TDS/22543
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 6 hours | |
| Oct-30 | |
| Oct-30 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Sep-18 | |
| Sep-01 | |
| Aug-19 | |
| Aug-19 | |
| Aug-07 |
