Ingersoll Rand Beats On Orders Surge And Data Center Win, But Flat Underlying EBITDA Tempers The Upside
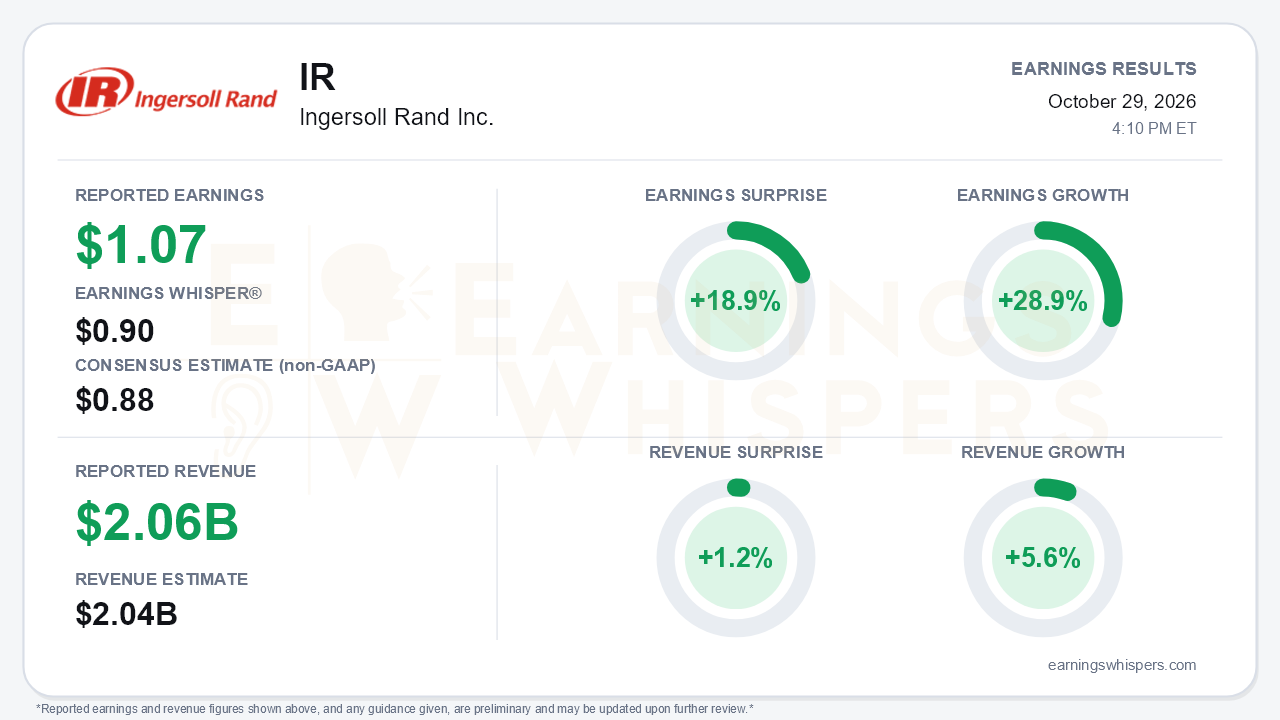
Ingersoll Rand (NYSE: IR) delivered the demand inflection that industrial bulls had been waiting for, though it arrived alongside weaker underlying profitability than the headline suggests. Third-quarter adjusted earnings of $1.07 per share beat the $0.88 consensus by 18.9% and cleared the $0.90 Earnings Whisper number. Revenue of $2.065 billion topped estimates by 1.2%. Earnings grew 28.9% year over year on Earnings Whispers' normalized basis, while the company's own adjusted comparison shows 24%. Revenue rose 5.6%, or 3.9% organically. The bigger story is orders, which rose 21% to $2.345 billion, or 18% organically, versus just 2% organic growth in the second quarter. Management raised full-year revenue and EPS guidance for the second straight quarter.
The quality of the beat deserves scrutiny. About $0.06 of the quarter came from IEEPA tariff refunds. Excluding them, adjusted EPS was $1.01. That still comfortably beats consensus, but it shows how much of the upside was one-time. Adjusted EBITDA excluding refunds rose only 1% to $552 million, and the 26.7% margin was below last year's 27.9%. Management cited inflation and China pricing for the year-over-year compression. Below the operating line, a lower tax provision and a share count reduced by roughly 11 million shares did much of the per-share work. GAAP EPS of $1.73 is even less representative. It includes $380 million of net recoveries tied to the ILC Dover transaction. Free cash flow of $623 million was similarly flattered, although the call put underlying free cash flow at roughly $461 million, still up about 40%.
The operating trends are what changed the narrative. Industrial Technologies and Services orders jumped 22% organically, with a 1.17x book-to-bill. The segment landed a roughly $195 million engineered-to-order award for backup power and filtration at a single data center site. Excluding that award, organic orders still grew high single digits. Long-cycle bookings rose more than 20%, and short-to-medium cycle orders firmed to mid-single digits. Margins also improved sequentially:
- ITS margin excluding refunds reached 27.8%, up 100 basis points from the second quarter, with another roughly 100 basis points guided for the fourth quarter.
- Precision and Science Technologies margin expanded to 32.6%, up 180 basis points year over year, helped by low-double-digit Life Sciences growth.
Management's tone shifted noticeably, from "mixed conditions" in the first quarter to "momentum building," with requests for quotes described as rapidly accelerating.
The data center win is the key catalyst. Ingersoll Rand had no presence in the market a year ago and now cites a growing funnel across Asia-Pacific, the U.S. and India. However, the order carries low-20s EBITDA margins, below the company average, and most of the revenue lands in 2027. That makes it a mix drag on ITS margins next year. Management also warned that these orders will be lumpy and require capacity and supplier investment. Guidance shows the same split. Revenue growth was raised to 5.5% to 7% and organic growth to 2% to 3.5%. Adjusted EPS excluding refunds rose to $3.58 to $3.70, aided by a tax rate cut to about 20% that management describes as durable. Yet the $2.13 billion to $2.19 billion EBITDA range was held and is now tilted to the bottom half. Fourth-quarter organic growth is guided to only about 2%, and acquired revenue is tracking well below the original target. Bears have legitimate ammunition: the EPS raise is driven more by tax and buybacks than by operating leverage.
Capital deployment adds support. The board added $2 billion to the buyback authorization on top of $313 million remaining, and leverage fell to 1.6x. Recoveries of roughly $425 million will further bolster cash in the fourth quarter.
The market setup is more complicated than the surprise implies. Investor sentiment was essentially unchanged and remains mildly negative at roughly -0.30. The stock enters the report at $80.01, almost exactly where it opened after the July release, and about 1.5% below its 200-day moving average. Investors have spent the quarter waiting for proof rather than pricing in recovery. The internal trend readings are mixed, with price trend negative while AVWAP is positive.
The bottom line is that Ingersoll Rand produced the clearest evidence yet of an orders recovery and a credible new growth avenue in data centers. Underlying EBITDA, however, barely grew, and the per-share upside leaned on refunds, tax and buybacks. Turning an 18% organic orders surge into margin-accretive earnings growth in 2027 is now the test, and skeptical sentiment suggests investors have not yet given management credit for passing it.
Read our earnings preview for Ingersoll Rand Inc.: https://www.earningswhispers.com/article/IR/21210
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Oct-08 | |
| Sep-18 | |
| Aug-26 | |
| Aug-06 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
