OmniAb Matches On EPS, Beats On Revenue, And Lifts Its Cash Outlook As Q3 Exposes The Lumpiness Of A Milestone-Driven Model
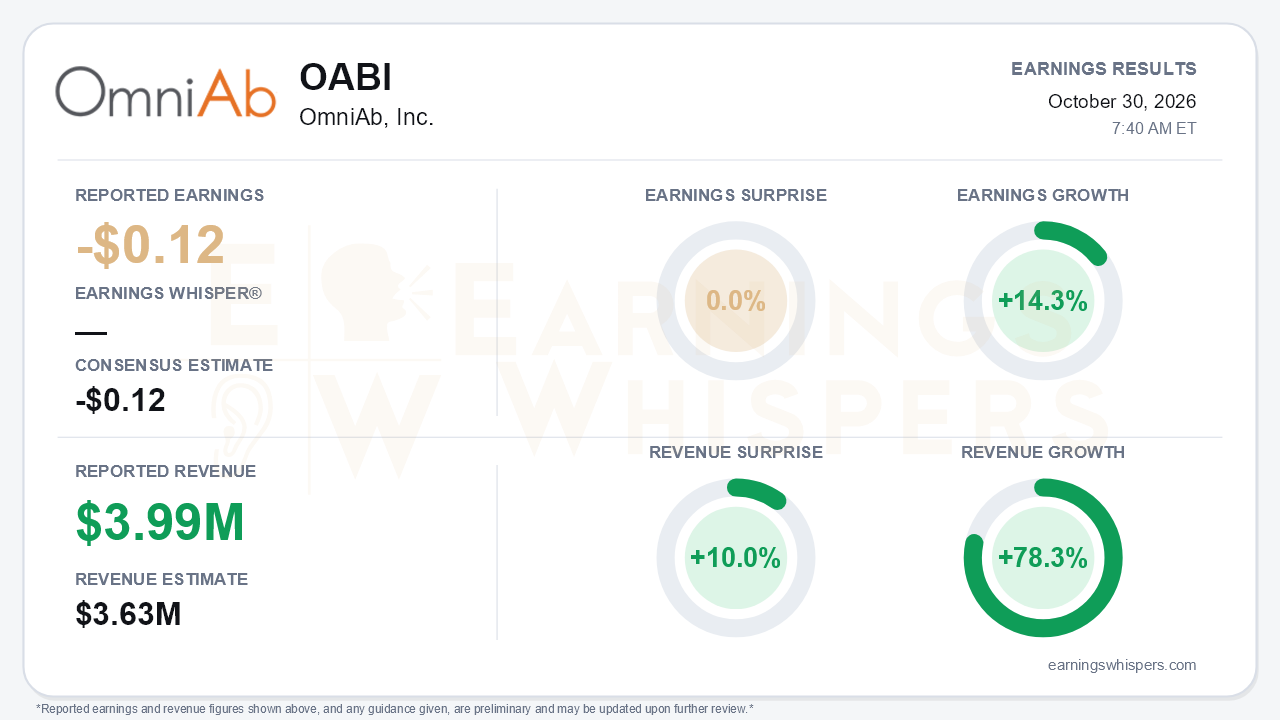
OmniAb (NASDAQ: OABI) posted a third-quarter loss of $0.12 per share, exactly in line with consensus. Revenue of $3.99 million beat the $3.63 million estimate by 10.0% and grew 78.3% year over year. Earnings improved 14.3% from the prior-year loss of $0.14 per share. Those are clean headline comparisons, but they are not the real story. The quarter's central tension is a sharp sequential revenue drop alongside the most constructive forward outlook the company has issued this year. Management raised full-year revenue guidance for the fourth consecutive time, to $35 million to $39 million. It also lifted its year-end cash forecast to $53 million to $57 million, from $49 million to $53 million.
The quality of the quarter deserves scrutiny. Q3 revenue of $4.0 million compares with $13.4 million in Q2 and $14.4 million in Q1. That is a steep decline that the year-over-year growth rate obscures. License and milestone revenue was just $0.1 million, versus $21.6 million year to date, so 2026's milestone haul was heavily front-loaded. The quarter's growth came from smaller lines. Service revenue more than doubled to $2.8 million on antibody and ion channel work, and xPloration revenue rose to $0.7 million from $0.07 million. The net loss of $15.7 million was modestly better than last year's $16.5 million but much wider than Q2's $5.9 million. Per-share comparisons are also flattered by a weighted share count that rose to 129.3 million from 114.7 million. Cash operating expenses of $13.7 million actually rose from $12.3 million a year ago, even as GAAP costs held flat at $20.4 million.
The balance sheet is where the quarter looks strongest. Cash and short-term investments climbed to $64.2 million from $52 million in Q2. Deferred revenue jumped, including $9.7 million of new long-term deferred revenue, which is consistent with the upfront payment from a new Eli Lilly ion channel license. That deal also carries up to $370 million in milestones plus tiered royalties, and service work on it begins in Q4. The new cash guidance now implies roughly break-even net cash flow for 2026, versus the roughly $15 million burn implied after Q2. Opex guidance was trimmed by $1 million on both a GAAP and cash basis. For a platform company, that shift in cash trajectory matters more than one quarter's EPS.
The call preserved a credible growth story built on breadth:
- **Partners and programs:** Active partners reached 111 and active programs rose to 433, up from 407 at year-end.
- **Big pharma reach:** Nine of the top 10 pharma companies are now partners, up from eight.
- **Approvals:** China's approval of batoclimab for generalized myasthenia gravis marks the fourth approved drug from OmniAb platforms.
- **Clinical data:** Teva reported positive Phase 2a celiac data for TEV-'408.
- **xPloration:** The platform moved to general availability with its first explicit outlook: $2 million to $3 million in 2026, doubling in 2027 and again in 2028.
- **New offering:** OmniTides extends the platform into peptides.
- **Upcoming readouts:** Management pointed to its busiest-ever calendar of partner readouts, with 19 expected over the next 15 to 18 months.
Bears still have legitimate ammunition:
- **Q4 setup:** Full-year guidance implies only about $3 million to $7 million of Q4 revenue.
- **Tougher 2027 comparisons:** Front-loaded 2026 milestones raise the bar for next year.
- **Shrinking milestone pool:** Remaining clinical milestones edged down to $340 million from $350 million as payments were earned.
- **Royalty timing:** A meaningful royalty inflection, tied to IMVT-1402, is not expected until late 2028.
- **xPloration economics:** Revenue is still mostly instrument sales with 12- to 18-month sales cycles, and consumable pull-through has not stabilized. Further investment may be required.
- **Partner attrition:** One partner was lost to M&A consolidation.
The market had already moved well ahead of the print. Shares rose 120.7% from the $2.37 open after the August report to $5.23 heading into earnings. That put them about 95% above the 200-day moving average and just 3.7% below the 52-week high of $5.43 set on September 2. Investor sentiment moved the other way, falling from -0.21 to -0.49. Expectations turned more skeptical even as price surged, which suggests a crowd wary of chasing a stock that had already doubled. The Earnings Whispers trend signals are mostly positive on price, momentum, and AVWAP. Sequential growth is the exception, and it is negative, which fits the Q2-to-Q3 revenue decline. Because the guidance raise was in line with estimates, the report offered little fresh upside surprise for a stock trading near its highs.
The bottom line is that OmniAb delivered a quarter that was weak sequentially but strategically strong. The Lilly deal, a near break-even cash outlook, a fourth platform approval, and quantified xPloration targets improve the durability argument. Yet the revenue base remains lumpy and milestone-dependent, and royalties are years away. With the stock near its highs and sentiment souring, the burden now shifts to partner readouts and xPloration execution to justify the rerating.
Read our earnings preview for OmniAb, Inc.: https://www.earningswhispers.com/article/OABI/21295
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 13 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-14 | |
| Oct-06 | |
| Sep-14 | |
| Aug-28 | |
| Aug-26 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-07 | |
| Aug-06 |
