Arbor Realty Misses, Suspends Its Dividend And Shifts To Defending Liquidity As Credit Losses Mount
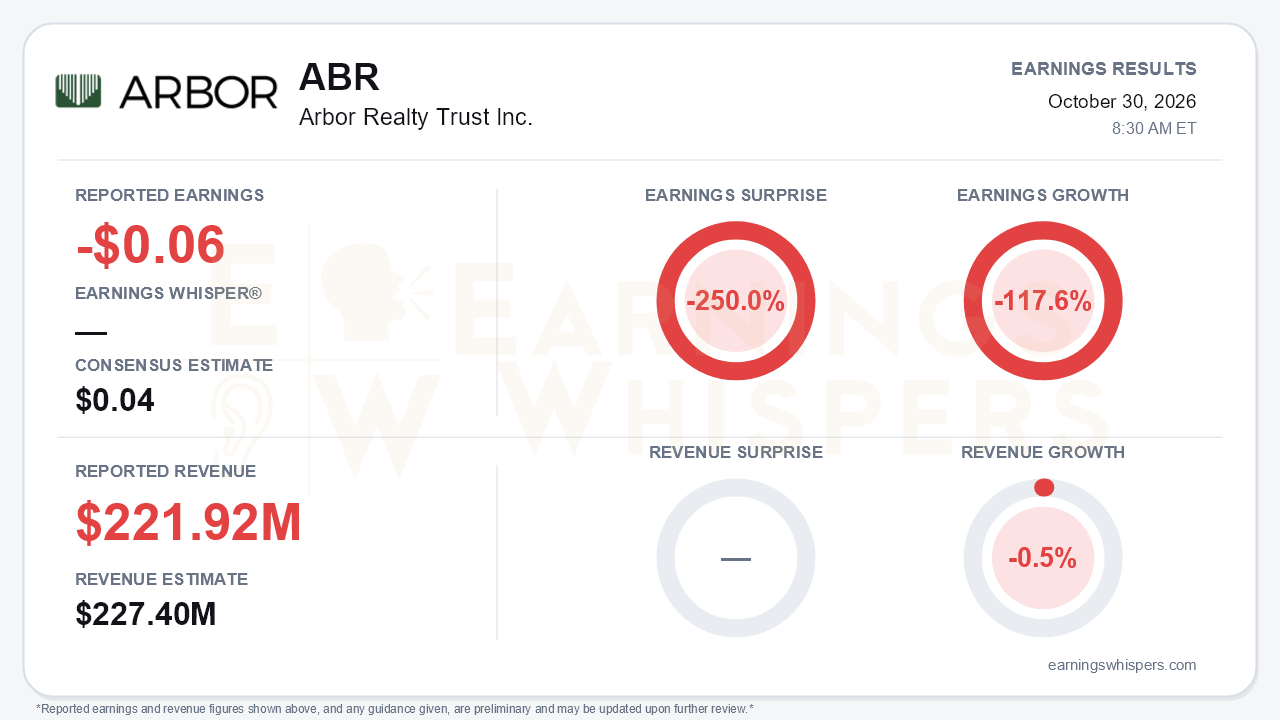
Arbor Realty Trust's third quarter marked a clear break lower. The company moved from managing a credit cycle to defending its balance sheet. On Earnings Whispers' normalized basis, Arbor lost $0.06 per share against a consensus profit of $0.04, a 250.0% miss. Earnings fell 117.6% year over year. Revenue of $221.92 million missed the $227.4 million consensus by 2.4% and slipped 0.5% from a year ago.
The company's own measures were worse in some respects. It reported a GAAP net loss of $0.51 per diluted share, compared with GAAP income of $0.20 a year earlier. Its distributable loss was $0.04 per share, down from distributable earnings of $0.35. The normalized figure falls between those two measures, and investors should know which one they are reading. The headline miss was not the most important development, though. The most important development was the board's decision to suspend the common dividend entirely, only two quarters after resetting it to $0.17.
The quality of the quarter does not hold up under scrutiny. Management pointed to distributable earnings of $0.08 excluding $21.7 million of realized losses on legacy assets. Even on that friendlier basis, the trend has fallen steadily:
- $0.22 in the fourth quarter of 2025
- $0.18 in the first quarter
- $0.15 in the second quarter
- $0.08 in the third quarter
That also breaks the roughly $0.17 'low watermark' management had guided to earlier in the year. The core lending spread is close to gone. The average portfolio yield fell to 6.84% from 7.21%, which the company attributed to new delinquencies and rate modifications. Meanwhile, the average cost of borrowings rose to 6.66% from 6.56%. Credit costs climbed sharply:
- **Provision for credit losses:** $55.5 million, up from $19.7 million a year ago.
- **REO impairments:** $34.1 million on six properties.
- **Loss-sharing provision:** $12.6 million.
- **Non-performing loans:** 32 loans with $647.6 million of principal, up from 19 loans and $428.8 million in June.
The call made the credit picture look worse, not better. Non-performing assets rose to roughly $1.25 billion from $1.07 billion, driven by about $450 million of new delinquencies. Management guided to reserves and impairments staying near the elevated third-quarter pace. It also pushed back several targets:
- **Year-end REO target:** now about $500 million, roughly flat, versus $300 million guided last quarter.
- **Year-end legacy book target:** now $2.7 billion, versus $2.4 billion.
- **Resolution timeline:** pushed out another one to two quarters, with earnings expected to bottom over the next two quarters.
Management called the rise in Treasury yields a 'material adverse change' and estimated that multifamily values are down 5% to 15%. Immigration enforcement raids, which earlier in the year were described as getting behind the company, have re-emerged as a driver of delinquencies in several Sun Belt markets.
The agency business, usually the steadier franchise, also weakened. Originations fell to $907 million from $1.08 billion, with Freddie Mac volume down by more than half. September originations came in under $200 million. Gain-on-sale margins compressed to 1.12% from 1.33% in the second quarter and 1.86% in the first. Full-year agency volume guidance was cut to $3.5 to $4.0 billion from roughly $5 billion. One modest positive was the mortgage servicing rights rate, which rose to 1.35% because of business mix.
The forward story is now about liquidity. Arbor faces a $275 million unsecured maturity in March 2027 and about $250 million more later that year. Management's plan includes:
- Building cash from about $400 million to roughly $700 million by the end of the first quarter of 2027.
- Saving about $125 million a year from the dividend suspension.
- Generating cash from payoffs, loan sales and REO dispositions, including one REO sale expected to free about $35 million of equity.
- Largely halting balance-sheet lending.
Capital markets access is a real strength. The new $825 million CLO priced at SOFR plus 170 with 88% leverage and added about $50 million of liquidity. Bears have legitimate ammunition elsewhere, however. Management did not rule out action on the preferred dividend. It also raised strategic options including private credit, warrants and a possible sale of an interest in the agency business, which is the franchise's most valuable asset. In hindsight, the timing of capital use is questionable. The company spent about $126 million of its convertible-note proceeds repurchasing stock in the same period it was preparing to cut the dividend.
The market had been pricing in serious distress well before the report. Shares fell 36.7% from the $4.77 open after the July report to $3.02 on the eve of this release. That leaves them about 49.5% below the 200-day moving average and 44.9% below the August 11 inter-earnings high of $5.48. The stock set a 52-week low of $2.53 on October 19 and entered earnings only about 19% above it. That price is under 30% of reported book value of $10.92 per share, a sign the market doubts the stated marks. Investor sentiment was roughly unchanged, slightly negative and only marginally less so than after the prior report. The Earnings Whispers trend signals are uniformly negative.
The bottom line is that Arbor's third quarter changed the investment question from how much the dividend will be to how the company bridges its 2027 maturities without diluting shareholders or selling core assets. Securitization access and a credible cash-building plan offer some cushion. However, rising delinquencies, reserve guidance that has moved higher, a shrinking agency pipeline and a resolution timeline that keeps slipping suggest the earnings trough has not yet arrived.
Read our earnings preview for Arbor Realty Trust Inc.: https://www.earningswhispers.com/article/ABR/21335
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-05 | |
| Oct-01 | |
| Sep-29 | |
| Sep-04 | |
| Aug-14 | |
| Aug-11 |
