Forum Energy Technologies Crushes Estimates And Raises Guidance Again, But Flattening Orders And A Flat Q4 Guide Temper The Momentum
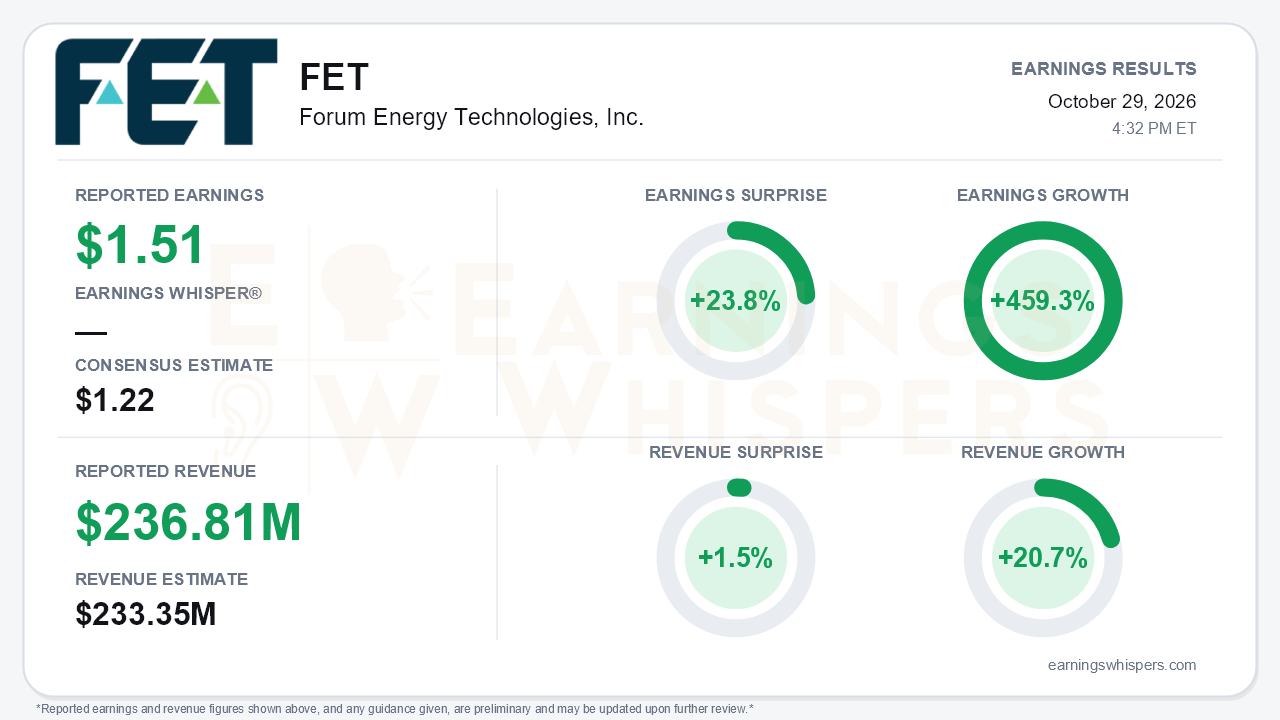
Forum Energy Technologies delivered another clean beat in the third quarter. Adjusted earnings came in at $1.51 per share against a $1.22 consensus, a 23.8% surprise. Revenue of $236.81 million topped the $233.35 million estimate by 1.5%. Year-over-year earnings growth of 459.3% reflects how far the company has come from a year-ago quarter that produced only $0.27 of adjusted EPS and a GAAP loss of $1.76 per share. Revenue grew 20.7% from the prior year. Management raised full-year guidance for the third consecutive call, and Earnings Whispers characterizes the outlook as above estimates. The central tension is that profitability and the balance sheet keep improving, while the forward indicators of top-line demand are leveling off.
The quality of the beat is mostly solid, though the GAAP and non-GAAP figures diverged. GAAP diluted EPS fell to $0.93 from $1.05 in the second quarter. The decline came from $4.9 million of restructuring and other costs (including a roughly $3 million litigation charge and facility sublease costs), $1.2 million of transaction expenses tied to the Premiere Torque Rings acquisition, and foreign exchange losses. Underneath those items, the operating story was strong:
- **Revenue and EBITDA:** Revenue rose 5% sequentially, and adjusted EBITDA climbed 14% to $36 million, the top of the guided range.
- **Margins:** Adjusted EBITDA margin expanded to 15.2%, up from 14.0% in Q2 and roughly 11% in Q1, on about 40% incremental margins.
- **Drilling and Completions:** This segment did the heavy lifting. Revenue grew 6%, adjusted EBITDA jumped 28% to $21 million, and margin widened about 240 basis points to 14.3%. Subsea revenue reached $34.7 million, up from $23.6 million a year ago.
Artificial Lift and Downhole is where the friction shows. Segment revenue rose 3%, helped by the acquisition and by sand and flow control demand. However, higher freight and tariff costs held adjusted EBITDA flat at about $21 million and trimmed margin to 23.7% from 24.8%. Order trends are also cooling at the margin:
- Consolidated book-to-bill slipped to 103%, from 104% in Q2 and 106% in Q1.
- Drilling and Completions fell below parity at 97%, and its orders of $142 million were below both the prior quarter and the year-ago period.
- AL&D was the bright spot, booking $101.5 million for a 113% ratio on processing equipment and technology orders.
Revenue per rig also dipped sequentially to $125,000 from $129,000 as the global rig count rose. That undercuts the market-share narrative slightly, although management noted the metric is still up about 35% since 2022.
The guidance and cash story is strong but carries asterisks. Full-year guidance now calls for:
- revenue of $900-$920 million;
- adjusted EBITDA of $123-$129 million, up from $115-$125 million;
- adjusted net income of $52-$58 million, up from $42-$52 million;
- free cash flow narrowed upward to $66-$71 million.
The implied fourth quarter, however, is essentially flat with Q3 at the midpoint: $240 million of revenue, $36 million of EBITDA and about $18 million of adjusted net income. Q4 also absorbs a roughly $5 million one-time stock compensation charge from cash-settling equity awards. Third-quarter free cash flow of $30 million beat the $15-$25 million guide, but management acknowledged about $10 million was pulled forward from Q4 working capital. Even so, net debt fell to $97 million and net leverage dropped to 0.9x from 1.4x in Q1. That leaves room for more bolt-on deals and refinancing optionality when the $100 million bond becomes callable in May 2027.
The call shifted the narrative toward 2027 growth. Management moved from Q1's assumption of a flat market to stating that indications favor a growth year. The annualized Q4 guide implies roughly 5% revenue and 14% EBITDA growth, which management expects to meet or beat. New catalysts include:
- Premiere Torque Rings, bought at about 4x EBITDA and adding roughly $8 million of annual EBITDA;
- a high-tensile perforating gun housing tube that has received its first order and expands the addressable market by about $200 million;
- advanced-stage RFQs for data center cooling;
- rising flow-control adoption in the Canadian oil sands;
- activity in Venezuela and Argentina.
International revenue is up 31% year to date. On the risk side, management cited Middle East conflict volatility (with no meaningful cancellations), working-capital needs as growth accelerates, and credit and country risk in Latin America.
The market setup is more complicated than the surprise implies. Shares have rallied 44.5% since the open following the July report, from $61.42 to $88.76, and sit about 41.7% above the 200-day moving average. Price and AVWAP trend readings are both positive. Yet investor sentiment moved the other way, deteriorating from -0.08 to -0.21. That is a meaningful shift deeper into negative territory and suggests skepticism is building even as the stock climbs. After such a steep run, a flat Q4 guide and softening book-to-bill give bears legitimate ammunition on near-term upside.
The bottom line is that FET's third quarter validated the margin-expansion and deleveraging thesis. It delivered a sizable adjusted beat, a third straight guidance raise and leverage below 1x, while laying out credible 2027 growth levers. The near-term top line is plateauing, Drilling and Completions orders dipped below revenue, and Q4 cash flow is partly borrowed. With the stock well extended above its long-term average and sentiment souring, the next leg likely depends on whether orders reaccelerate to support the growth year management now expects.
Read our earnings preview for Forum Energy Technologies, Inc.: https://www.earningswhispers.com/article/FET/21282
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-12 | |
| Sep-21 | |
| Aug-25 | |
| Aug-18 | |
| Aug-12 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jul-08 |
