Perma-Fix Must Show Delayed Treatment Revenue Arrived As Hanford Grouting Hopes Face Scrutiny
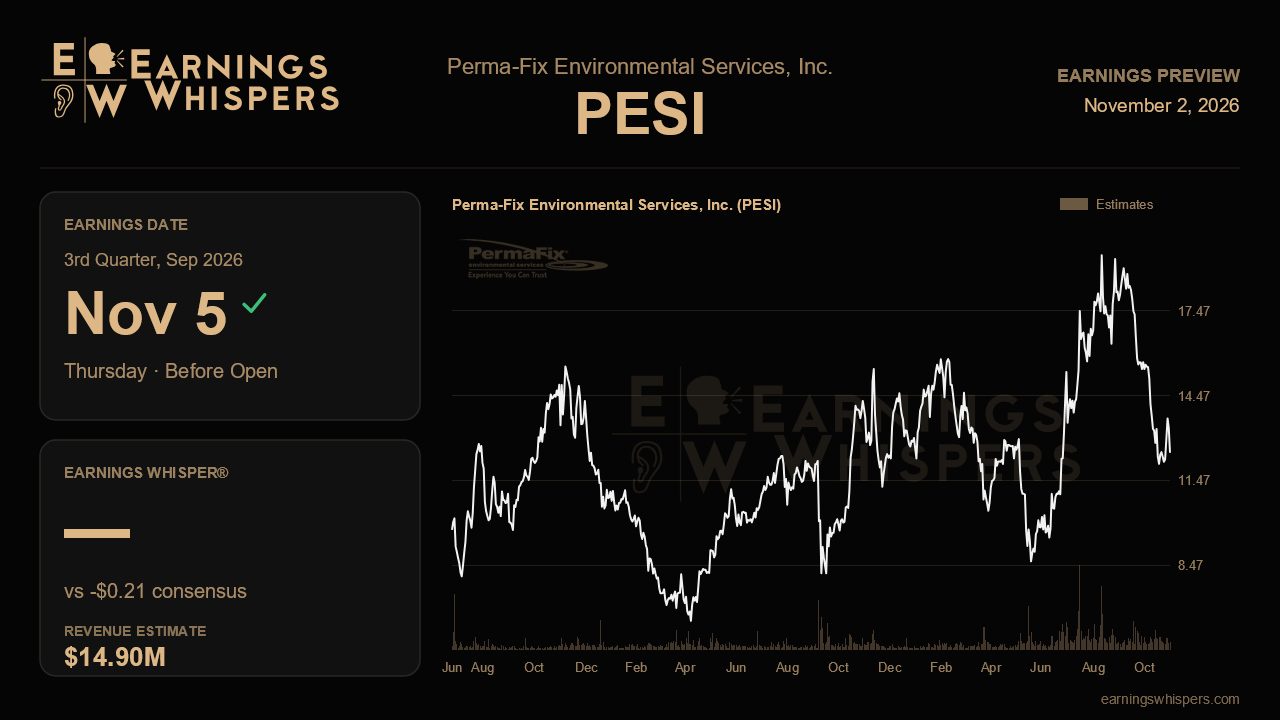
Perma-Fix Environmental Services heads into its September-quarter report with two very different stories competing for investors' attention. The long-term story improved sharply in August, when the company was named a grouting provider under a Hanford master subcontract and the Department of Energy publicly identified Perma-Fix Northwest within its Glass Plus Grout strategy. The near-term story got worse: a weak June quarter, a wider loss and a going-concern disclosure in the 10-Q. This report is the first chance to see whether the operating business can stabilize while the bigger opportunity takes shape.
The Street is not asking for much. Consensus calls for a loss of $0.21 per share on revenue of about $14.9 million. That is a contraction from the year-ago quarter, with revenue down roughly 15% from $17.5 million and the loss roughly double the $0.10 posted a year earlier. Sequentially, though, the numbers imply real improvement from the June quarter's $12.9 million in revenue and $0.32 loss. Management has not issued formal guidance, so the consensus figures stand alone as the benchmark. They rest largely on one assumption: that the revenue held back last quarter actually shows up this quarter.
That assumption comes straight from the last call. Management had described the June quarter as an inflection point. Instead, a customer-directed change to treatment protocols paused processing, shifting revenue into the third quarter after the related costs had already been booked. If that explanation holds, the September quarter should show treatment revenue recovering and margins improving as stored waste moves through the plants. A clean rebound would support the idea that the June miss was a timing issue. Another quarter of low-margin processing and thin treatment revenue would suggest a deeper volume and mix problem. Treatment revenue fell about $3.1 million year over year last quarter, and that comparison matters more than the headline loss.
The leading indicators are encouraging but need follow-through. Treatment backlog climbed 29% sequentially to $15.7 million, new waste receipts rose by $4.1 million, and services revenue jumped 44% with more than $17 million of backlog over 18 months. A healthy report would show backlog converting into revenue without being replenished at a slower pace. Investors should also look for any meaningful pickup in liquid effluent and dry waste from Hanford's direct-feed vitrification plant, which began arriving in early July at what management described as nominal levels. On the grouting front, task orders cannot begin until January 2027. Useful evidence this quarter would include progress on the Washington Ecology permit modification to expand capacity from 1.2 million to about 10 million gallons a year, and any sign that DOE's early schedule of roughly 60,000 gallons a month in late 2026 is still realistic. Cash, which stood at $20.5 million after the May equity raise, will also be closely examined given the going-concern language.
The market has already passed judgment on the quarter. Shares have fallen about 40% since the last report while the S&P 500 slipped only 2.5%. At $12.45, the stock sits below its 200-day moving average of $13.89 and not far above its post-earnings low of $11.88, well off the $20.78 peak reached after the Hanford news. Sentiment is modestly bearish. Expectations are subdued, which lowers the bar for a constructive surprise but also leaves little patience for another timing excuse.
The central question is simple. Did the deferred treatment work convert into revenue and better margins as management said it would? If it did, the June quarter looks like a stumble, and the grouting opportunity becomes credible upside for a company that can fund itself in the meantime. If it did not, the going-concern flag will weigh more heavily than any shared contract ceiling, however large.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-30 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 | |
| May-15 | |
| May-14 | |
| May-06 | |
| May-05 |
