Perma-Fix Beats Lowered Bar As Revenue Rebounds 39% Sequentially, But Missed Breakeven, Cash Burn And Slipping Hanford Timelines Keep The Story Unproven
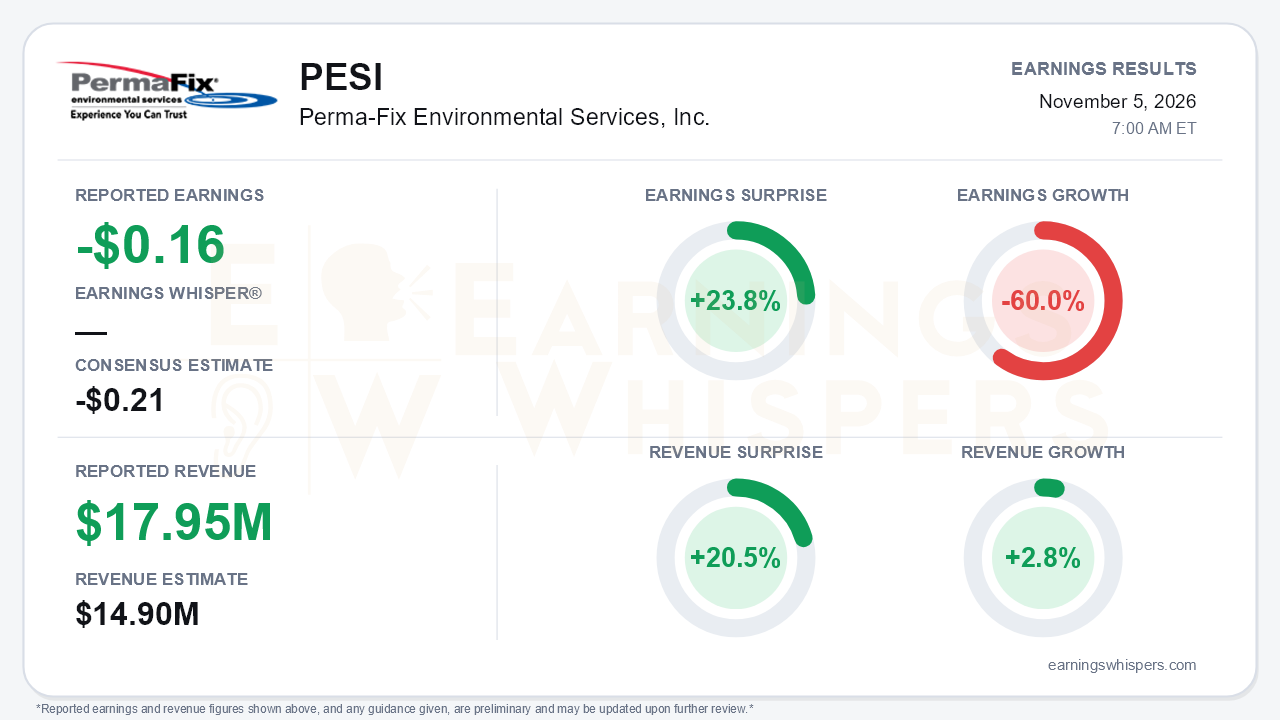
Perma-Fix Environmental Services (NASDAQ: PESI) cleared a low bar in the third quarter. The company posted a loss of $0.16 per share, 23.8% better than the consensus estimate of a $0.21 loss. Revenue of $17.95 million topped the $14.9 million consensus by 20.5%. The beat is real, but it measures progress against depressed expectations rather than a healthy earnings base. Earnings fell 60.0% year over year, with the net loss widening to $3.5 million from $1.8 million. The company also missed management's own stated goal of reaching breakeven in Q3. That is the central tension: the quarter was clearly better than the first half, yet the recovery remains more promised than delivered.
The headline also masks a sharp divergence between segments. Revenue grew just 2.8% year over year. That still marks a return to growth after a first half in which nine-month sales trailed the prior year. Sequentially, the rebound was substantial, with revenue up 39% from $12.9 million in Q2 and $11.1 million in Q1. All of the year-over-year gain came from Services, which grew 46% to $6.3 million, lifted gross margin to 12.2% from 6.7%, and turned a small operating profit. Treatment, the core franchise, went the other way:
- Revenue fell to $11.6 million from $13.1 million.
- Gross margin collapsed to negative 1.9% from 17.3%.
- A Hanford-related waste stream sat idle until customer-directed protocol changes were approved in late August.
- Thermal upgrades at Florida and Kingston forced temporary downtime.
- Roughly $1.1 million of added fixed costs landed on a smaller revenue base.
Consolidated gross profit did return to positive territory at $552,000. Still, EBITDA was a loss of $3.1 million, versus a $1.5 million loss a year ago.
The forward indicators are the strongest part of the report. Treatment backlog reached $19.6 million, up about 25% in the quarter and roughly 65% since year-end 2025. Price increases rolled out from August through October on both commercial and government streams, which management described as a first, and they are now showing up in new backlog. On the call, management said DFLAW effluent volumes had roughly doubled since October to about 16,000 gallons a month, which it framed as roughly $17-18 million annualized, with potential to reach about 40,000 gallons. Several other catalysts are lined up:
- The first task order under the H2C Master IDIQ is expected within weeks.
- The grouting capacity target was raised to more than 10 million gallons a year, from 4.2 million discussed in Q1.
- The Gen 2.0 PFAS unit is set to begin commissioning this quarter, supported by Florida's phase-out of PFAS-containing firefighting foam.
Note that the $4.4 billion IDIQ ceiling is shared among three contractors and does not represent committed revenue.
Bears have legitimate ammunition on timing. East Area AP-106 grouting was guided in Q2 to start in Q4 2026 at about 60,000 gallons a month. It now looks likely to slip several months after Washington Ecology issued incompleteness letters on DOE's permit modifications. The other Hanford schedules are also moving:
- DFLAW throughput for 2026 is expected at 300,000-400,000 gallons, against a 500,000-gallon goal.
- Dry waste is held up by the Bechtel-to-H2C operating transition, which runs through April.
- Permit expansion moved from Q2/Q3 2027 to 2027 or late 2027.
- The full-rate DFLAW revenue opportunity is now framed at $35-70 million, versus $70 million previously.
This also echoes a pattern: earlier calls pointed to a Q2 inflection that did not arrive until Q3.
Liquidity sharpens the stakes. Cash fell to $14.7 million from $20.5 million at the end of Q2, and working capital dropped to $11.4 million from $18.4 million. That burn came despite the May equity offering, which pushed the weighted share count up about 15% year over year. The 10-Q still carries going-concern language, and the company acknowledges that resolving it depends on government-directed waste shipments outside its control. Management said on the call that it expects to exit the going-concern qualification and sees no near-term need to raise equity. That is an expectation, not a result. A likely federal continuing resolution could also weigh on receipts at non-Hanford sites. The extension of the PNC credit facility to May 2030 provides some breathing room.
The market had already priced in considerable skepticism before the report. Shares closed at $12.81 on November 4, down 38.1% from the $20.71 open after the August report, which nearly marked the inter-earnings high of $20.78. The stock sat 7.6% below its 200-day moving average of $13.87 and only 7.8% above the October 20 low of $11.88. Investor sentiment was modestly negative at -0.22, consistent with a shareholder base that has heard inflection promises before. AVWAP trend readings remain negative while price momentum has merely stabilized at neutral.
The bottom line is that Perma-Fix delivered a credible sequential turn: higher revenue, positive gross profit, record backlog, real pricing power and a strengthening Services business. It did all that against expectations low enough to make the beat look larger than the underlying improvement. Treatment margins, cash burn, the going-concern overhang and a lengthening Hanford calendar mean the investment case still hinges on Q4 and early 2027 execution. The setup has improved, but investors will want to see breakeven, task-order awards and stabilizing cash before treating this quarter as the inflection management has long anticipated.
Read our earnings preview for Perma-Fix Environmental Services, Inc.: https://www.earningswhispers.com/article/PESI/22547
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-30 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 | |
| May-15 | |
| May-14 | |
| May-06 | |
| May-05 |
