Ceva Must Prove Its Twice-Raised Outlook Holds As Shares Slide Despite Momentum
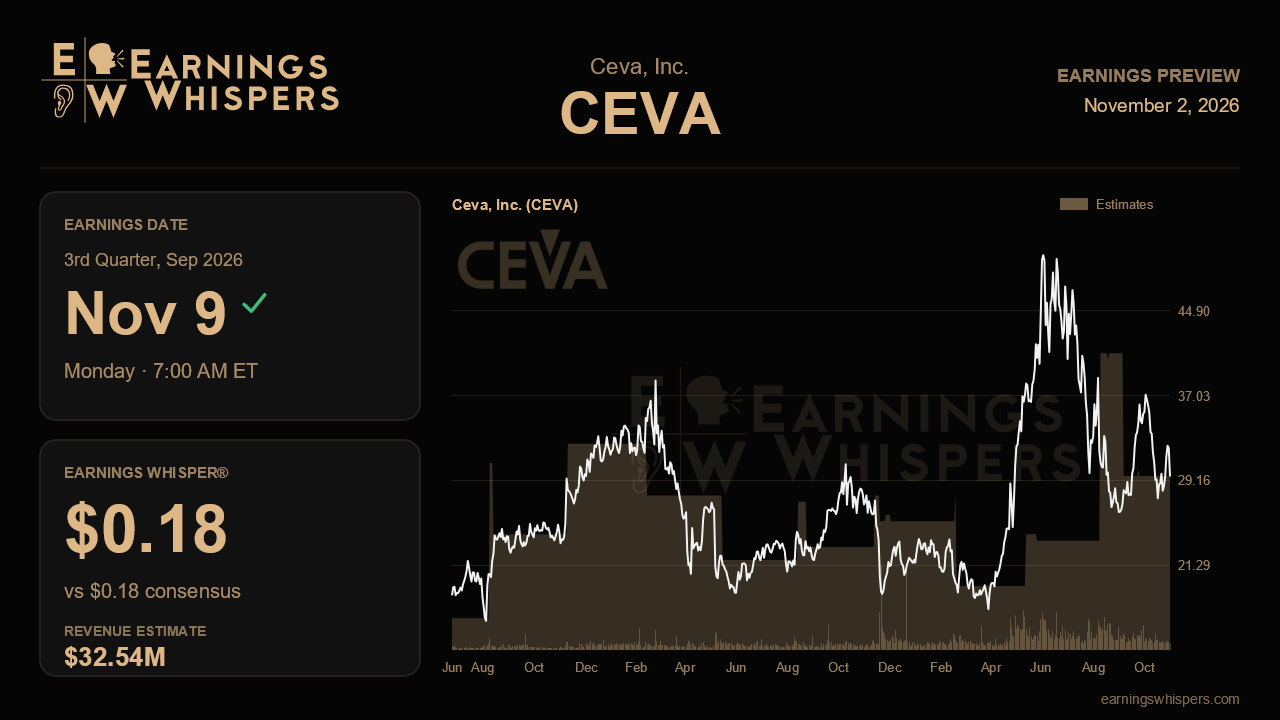
Ceva heads into its third-quarter report with an awkward contradiction to resolve. Management has raised its full-year outlook on two consecutive calls, royalties have turned back up, and profitability expanded sharply last quarter. Yet the stock has dropped roughly 20% since that upbeat update, trailing the S&P 500 by nearly 18 percentage points. The November 9 release, due before the open, is the company's chance to show that the operating story has not quietly cracked while the share price was falling.
The Street is looking for non-GAAP earnings of $0.18 a share on revenue of about $32.5 million, which would be growth of roughly 14.6% from the year-ago quarter. The Earnings Whisper sits right at consensus, so there is no hidden bar to clear. Expectations are simply that Ceva delivers what it has promised. That figure lines up neatly with management's raised target of 13% to 15% revenue growth for fiscal 2026, landing toward the upper half of the range. The more demanding detail is sequential: getting from $29.0 million last quarter to $32.5 million requires a jump of about 12% in a single quarter. That is the kind of second-half lift the guidance implies, but it leaves little room for a soft licensing period.
Licensing is where the narrative was built. Last quarter's $18.2 million in licensing and related revenue was the strongest in three years, even as the count of signed agreements fell to 10 from 14 the quarter before and 18 the quarter before that. Management framed the trend as quality over quantity, pointing to larger platform and subsystem deals and, most notably, a NeuPro-M NPU win with a major AI and computing platform company that builds both hardware and operating systems. Further evidence of that depth, such as additional NPU customers or more full-subsystem adoptions, would validate the reframing. Another quarter of fewer deals without a corresponding revenue payoff would make the explanation sound more like a rationalization.
Royalties are the second test. They rebounded 17% sequentially to $10.8 million after a flat first quarter, helped by strong Wi-Fi shipments, record cellular IoT units and share gains in entry-tier smartphone modems. The drag came from Bluetooth, where units fell 16%, partly due to combo-chip reclassification, and from softer industrial IoT volumes. Sustaining royalty growth matters because royalties are the recurring, high-margin engine that justifies Ceva's operating leverage. Management has also repeatedly flagged memory pricing and supply constraints as second-half variables, and any sign those pressures slowed customer shipments would be the clearest threat to the outlook. Investors should also check the shekel's effect on financial income, which fell short of guidance last quarter.
Profitability ties it together. Non-GAAP operating margin leapt to 11% from 2% the prior quarter, and the full-year guide now calls for non-GAAP operating income to rise about 70%, up from 35% to 40% at the start of the year. Having raised that number so aggressively, management has set a high bar for yet another increase. Holding the guide would likely be acceptable; trimming it would be costly.
Sentiment remains modestly bearish and essentially unchanged from last quarter, while the stock trades just below its 200-day moving average and toward the lower part of its post-earnings range, well beneath the prior quarter's highs above $50. That positioning suggests skepticism is already built in. The deciding issue is whether Ceva can confirm the back-half acceleration its guidance requires. Reaffirming the 13% to 15% growth target alongside steady royalties would leave the improving narrative intact; any retreat from it would suggest the market's doubts were warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 16 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-14 | |
| Sep-16 | |
| Sep-15 | |
| Sep-09 | |
| Aug-20 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-04 | |
| Jul-20 |
