Ceva Misses On A Slipped Licensing Deal And Cuts Full-Year Growth, Leaving A Record Q4 Guide And The Modem Royalty Ramp To Carry The Story
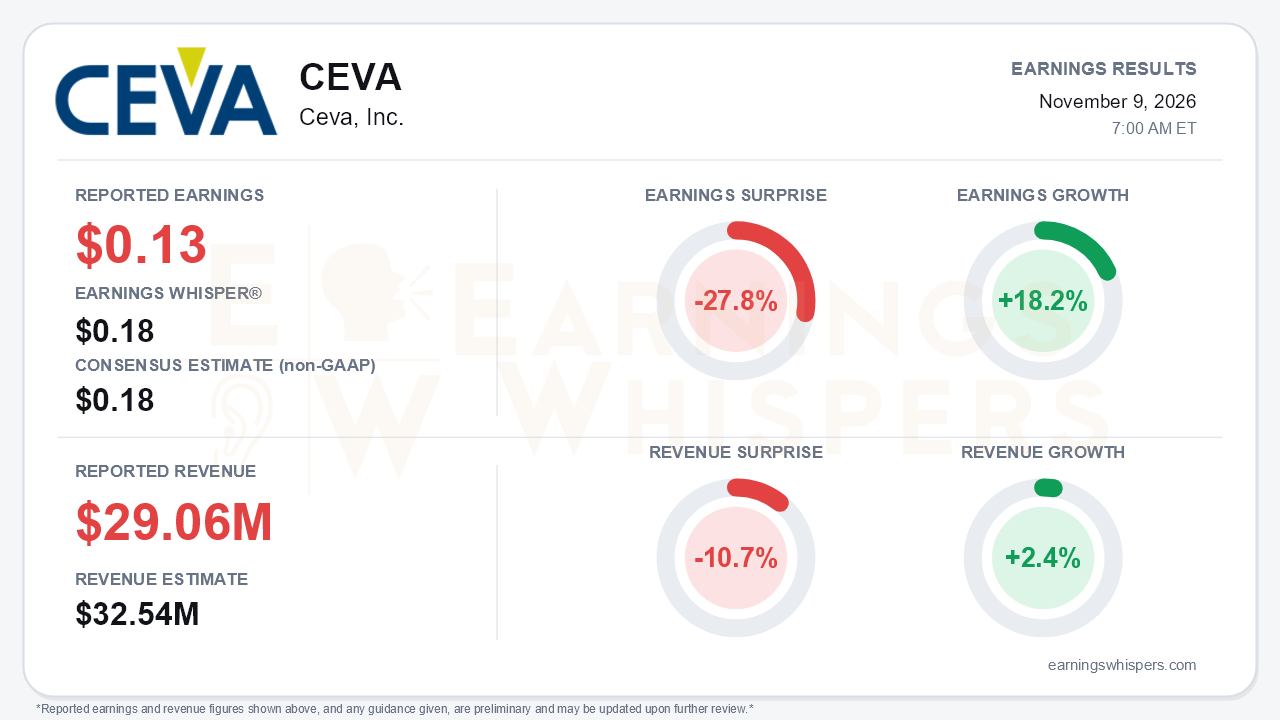
Ceva (NASDAQ: CEVA) delivered a clear third-quarter miss. Non-GAAP earnings of $0.13 per share fell 27.8% short of both the $0.18 consensus and the $0.18 Earnings Whisper number. Revenue of $29.06 million trailed the $32.54 million consensus by 10.7% and also landed below management's own $30.5-34.5 million guide. Earnings still grew 18.2% from a year earlier, but revenue growth slowed sharply to 2.4%, down from roughly 13% in Q2 and 11% in Q1. The central tension is that the growth engines are improving while near-term execution is slipping. Royalties, AI licensing and the U.S. smartphone modem ramp are building, but a delayed licensing deal and memory-driven end-market weakness pushed the burden of the year onto a record fourth quarter.
The quality of the beat in year-over-year EPS deserves scrutiny. Non-GAAP operating income actually fell to $2.5 million from $3.1 million a year ago. Non-GAAP operating margin slipped to 9% from 11% in Q2. Non-GAAP gross margin of 86% missed the 88% guide and was below 89% a year earlier. The lift to non-GAAP net income came largely below the operating line: financial income nearly doubled to $2.3 million and the tax expense fell, which more than offset a share count that rose to about 29.9 million from 25.7 million. On a GAAP basis, the operating loss widened to $3.5 million from $2.1 million as G&A jumped to $6.2 million from $4.4 million and deal-related costs rose. The GAAP net loss of $0.08 per share was modestly narrower than last year's $0.10 loss, but core operating profitability went the wrong way.
Beneath the miss, the revenue mix shifted. Licensing revenue fell to $16.3 million from $18.2 million in Q2 and $17.8 million in Q1, largely because a significant multi-year connectivity agreement slipped into early Q4. Royalties moved the other way:
- Royalty revenue climbed to $12.7 million, up 18% sequentially and up from $10.8 million in Q2 and $9.2 million in Q1.
- Mobile royalties rose 20% year over year and 30% sequentially as a major U.S. OEM's in-house modem entered high-volume flagship production.
- AI licensing hit a record at more than 35% of licensing revenue, versus over 20% in FY2025. Six of the quarter's 10 deals were AI-related, including a first AI-infrastructure customer for the new NeuPro Ultra NPU.
- Wi-Fi 6 rose to 57% of Wi-Fi units from 24% a year ago, which more than doubled Wi-Fi royalty dollars even as total Wi-Fi units fell 6% to 78 million.
Guidance is where bears have legitimate ammunition. Full-year growth is now implied at roughly 11%, effectively reversing the Q2 raise to 13-15%. Management also did not repeat its prior targets for roughly 70% non-GAAP operating income growth and 50% net income growth. Memory-market headwinds, previously a watch item, are now an active drag on phone, PC and TV volumes. The Q4 guide of $34-38 million would be the company's best quarter ever, but it requires roughly 24% sequential growth. That makes the outlook heavily back-end loaded and dependent on the delayed deal, the modem step-up and a broader licensing pipeline converting on schedule. Management trimmed expected non-GAAP expense growth to about 7%, and engineering headcount has drifted lower. That supports margins but also signals tighter spending.
The forward catalysts are real. The modem ramp is expected to accelerate in Q4 and through 2027. Initial NPU royalties are targeted around the end of 2026 or early 2027, supported by multiple tape-outs including a large PC OEM. Three of Ceva's highest-volume connectivity customers extended multi-year agreements and added IP. Those developments widen the future royalty base, but the payoff sits mostly outside the quarter just reported.
The market had already been punishing the stock before the release. Shares closed at $27.10 on November 6, down 26.4% from the $36.84 open after the August report. That price was 11.6% below the 200-day moving average and about 27% below the October 2 inter-earnings high of $37.33, though roughly 14% above the November 5 low of $23.71. Investor sentiment remained negative and weakened modestly, from -0.115 to -0.147, so expectations were already subdued rather than euphoric. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative, consistent with improving royalty trends set against a stock that has been heavily sold.
The bottom line is that Ceva missed on earnings and revenue, cut its full-year growth outlook, and posted weaker operating margins, with year-over-year EPS growth flattered by financial income rather than core operations. The underlying royalty story improved, and AI licensing is gaining share of the mix. Credibility now rests on delivering a record fourth quarter that requires a steep sequential jump. With the stock already well below its 200-day average and sentiment soft, the setup hinges less on what Ceva promised and more on whether the modem ramp and the delayed deal show up in Q4 numbers.
Read our earnings preview for Ceva, Inc.: https://www.earningswhispers.com/article/CEVA/22556
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-14 | |
| Sep-16 | |
| Sep-15 | |
| Sep-09 | |
| Aug-20 | |
| Aug-10 |
