Compugen Heads Into Q3 Near Its Lows As Investors Await Clarity On MyOvarian And Gilead
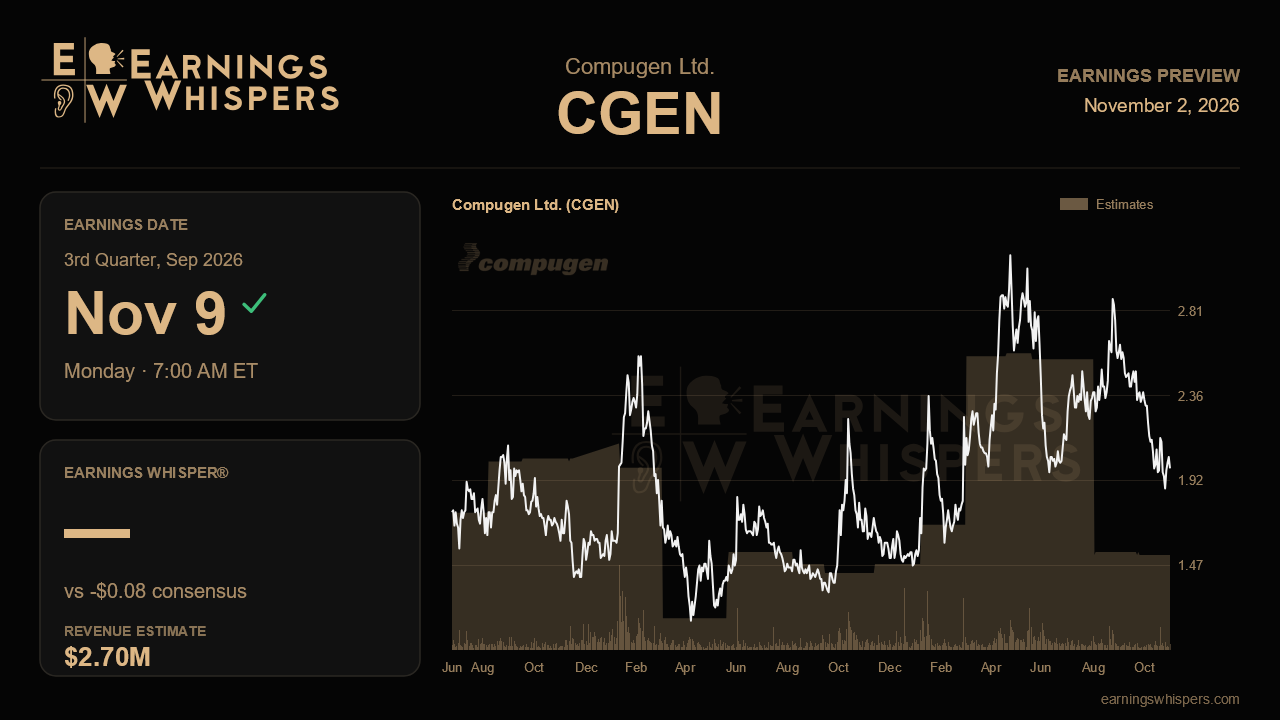
Compugen's third-quarter report will not change the company's fate on its own, but it arrives at an uncomfortable moment. The stock has slid about 15% since the last update while the broader market barely moved. The company's most important internal catalyst, the MyOvarian interim readout, is still slated for the first quarter of 2027. Management also lowered the bar that readout will be measured against. With the shares trading near their post-earnings low, the real question is whether management can make the waiting period look productive rather than merely patient.
The numbers themselves are modest by design. Wall Street expects a loss of 8 cents per share, slightly wider than the 7-cent loss a year ago, which works out to roughly 14% deterioration. Revenue is forecast at about $2.7 million, up nearly 43% from $1.9 million in the year-ago quarter and roughly in line with the $2.6 million reported last quarter. That growth rate sounds impressive, but the base is tiny, and for a clinical-stage immuno-oncology company the income statement is mostly a test of spending discipline. Management has offered no formal financial guidance to compare against consensus. The more relevant yardstick is cash. Reserves fell from $145.6 million at the end of 2025 to $125.3 million by June, a burn of roughly $10 million a quarter. If quarterly spending holds near that pace, it would support the claim that runway extends into 2029. A noticeably larger drawdown would invite questions about that timeline.
The scientific story is where the last call left investors divided. On one side, AstraZeneca keeps expanding its commitment to rilvegostomig, the PD-1/TIGIT bispecific that carries Compugen's economics. The partner's Phase 3 program grew from 10 trials to 11 and then to 12, most recently adding an adjuvant bladder cancer study combining the drug with Dato-DXd. The first overall survival data, 16.8 months in first-line biliary tract cancer against historical figures below 13 months, reinforced management's view of a differentiated backbone therapy. That view underpins a peak sales estimate above $5 billion and $195 million in remaining milestones. Another addition to the trial count, or further clinical data, would show this momentum is still building. A quarter with no new AstraZeneca activity would not break the thesis, but it would remove the main source of good news recently.
The other side is MyOvarian. Management cut its assumed placebo-arm progression-free survival to about 4 months from the roughly 5.5 months it cited in the two prior quarters. The change was driven by outside trials showing control-arm outcomes as short as 2.8 months in more heavily pretreated patients. A lower benchmark could make the drug look better by comparison. It also implies a harsher disease setting and raises the question of whether the goalposts are being adjusted ahead of the readout. Reassurance this quarter would mean reaffirming the first-quarter 2027 timing and explaining clearly how the new benchmark shapes the interim analysis. Any slippage in timing would be damaging given current sentiment.
Gilead's GS0321 is the quieter swing factor. Roughly 18 months into Phase 1, management described dose-escalation data as a bit early and committed to no disclosure date. That partnership still carries up to $768 million in potential milestones, so even a rough timeline for data would help restore confidence.
The mood has clearly soured. Sentiment readings have moved from mildly bearish ahead of the last report to decidedly more negative now. The stock sits at $1.98, well below its 200-day moving average of $2.30 and only about 6% above its post-earnings low of $1.87. That low is slightly beneath the prior quarter's floor of $1.95, a sign that support is eroding rather than holding. Low expectations can cushion a quiet quarter, but they also suggest buyers want proof before they return. Ultimately, this report hinges on whether Compugen can show steady cash burn, firm MyOvarian timing, and continued partner progress. Those three things would keep intact the case that the company is well funded and on schedule for its 2027 catalyst.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| Nov-02 | |
| Oct-26 | |
| Oct-06 | |
| Sep-22 | |
| Sep-08 | |
| Aug-26 | |
| Aug-05 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-21 | |
| Jul-20 | |
| Jun-18 | |
| Jun-11 |
