Monday.com's AI Pivot Faces Its First Test As Margins Rise And Growth Cools
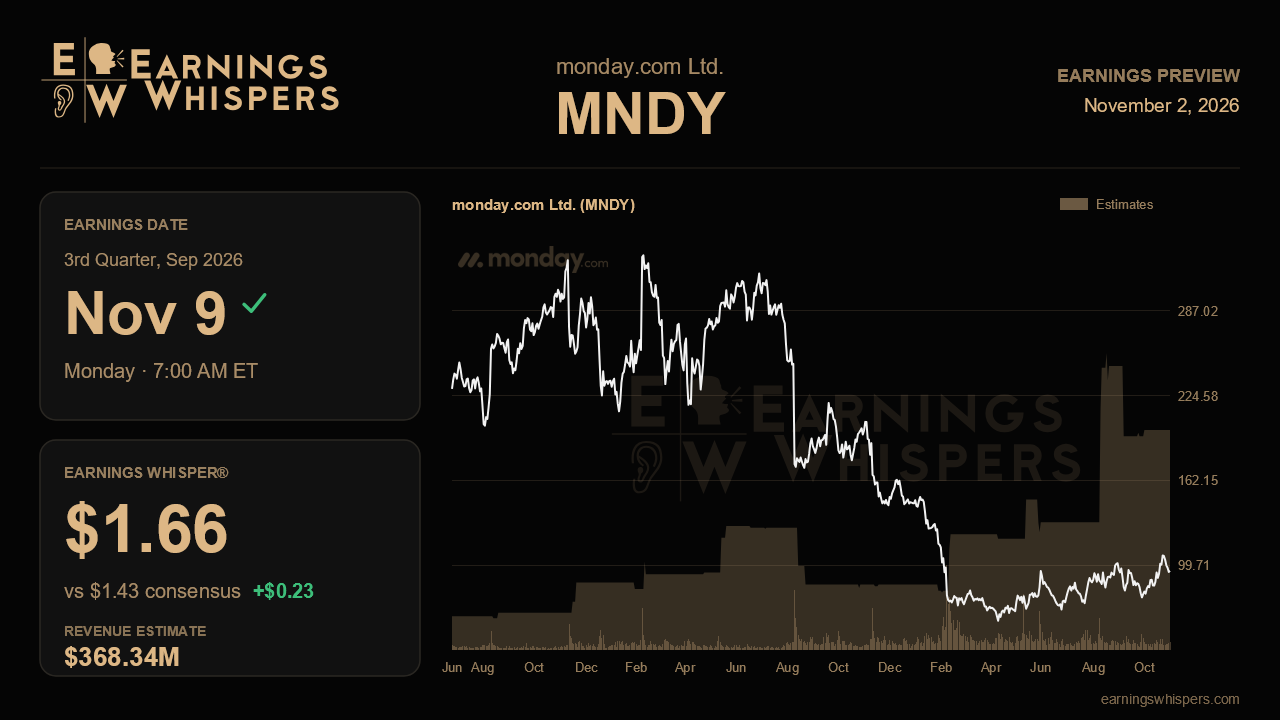
monday.com heads into its third-quarter report in the middle of a deliberate reinvention. Three months ago, management cut roughly a fifth of its workforce, leaned hard into AI products and pricing, and guided revenue growth down to the mid-teens while promising fatter margins. The market has largely given the company the benefit of the doubt. The stock is up about 17% since the last report while the S&P 500 slipped, so this quarter needs to show that the restructuring is producing efficiency and AI traction rather than simply a slower business.
The revenue bar is modest by monday.com's standards. Consensus calls for $368.3 million, up about 16% from a year ago, compared with 22% growth in the second quarter and mid-20s growth through most of last year. That figure sits at the low end of management's $368 million to $370 million guidance, and below the roughly $372 million analysts were modeling before the company reset expectations. Sequentially, the guide implies only about 1% growth over the second quarter's $364.6 million. The company also reaffirmed full-year revenue of $1.466 billion to $1.474 billion. Management explicitly chose not to pass the second-quarter beat through to its outlook and adopted an under-promise posture, so a revenue result at or slightly above the top of the range would be the normal outcome. Landing near the bottom would raise doubts.
Profit is where the expectations get more interesting. Consensus calls for non-GAAP EPS of $1.43, a sharp step up from $0.71 last quarter and $0.25 a year ago. The whisper number of $1.66 sits meaningfully above that, so the informal bar is higher than the published one. That gap makes sense given the margin story. Operating margin reached 17% in the second quarter, well ahead of the 11% to 12% full-year target management set at the start of the year and the 13% to 14% it raised to in the spring. The layoffs are expected to save about $100 million a year, and this is the first full quarter in which some of those savings should appear. Investors will want evidence that margin expansion is running ahead of plan without visible disruption to sales execution.
The operating metrics will matter as much as the headline numbers. AI annual recurring revenue doubled from the first quarter to the second and accounted for 17% of net new ARR, up from about 10%. That was helped by the new seats-plus-credits pricing and customers buying extra credit buckets. Continued growth in that share would support the idea that AI is a genuine new expansion lever. A plateau would suggest early enthusiasm rather than durable demand. Net dollar retention is guided to about 108% for the year after easing from 111%, so a further drop below that level would be a warning sign. The upmarket story should also hold up. Customers paying over $100,000 grew 37% and those over $500,000 grew 68% last quarter, while gross retention hit record highs. On the weaker side, the small-business segment, paid-search lead generation, multi-product adoption and the newer CRM and Service products all need to stabilize rather than slip further.
Sentiment remains bearish but has improved from the prior quarter, and the stock's rally suggests some of the margin upside is already priced in. Shares trade above their 200-day moving average near $84 but well below the post-earnings peak of about $111. That leaves room in either direction.
The central question is whether monday.com can show that deliberately slower growth is buying lasting operating leverage and a real AI revenue engine. If AI's share of new ARR keeps climbing, retention holds near 108%, and margins clear the whisper-level bar, the reset story stays intact. If revenue merely meets a lowered guide while growth indicators keep fading, the restructuring will look more like a retreat than a reinvention.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-12 | |
| Oct-08 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 |
