Monday.com's Record Margin Masks A Slowdown: Restructuring And Buybacks Drive A Big EPS Beat As Q4 Guide Points To 14% Growth
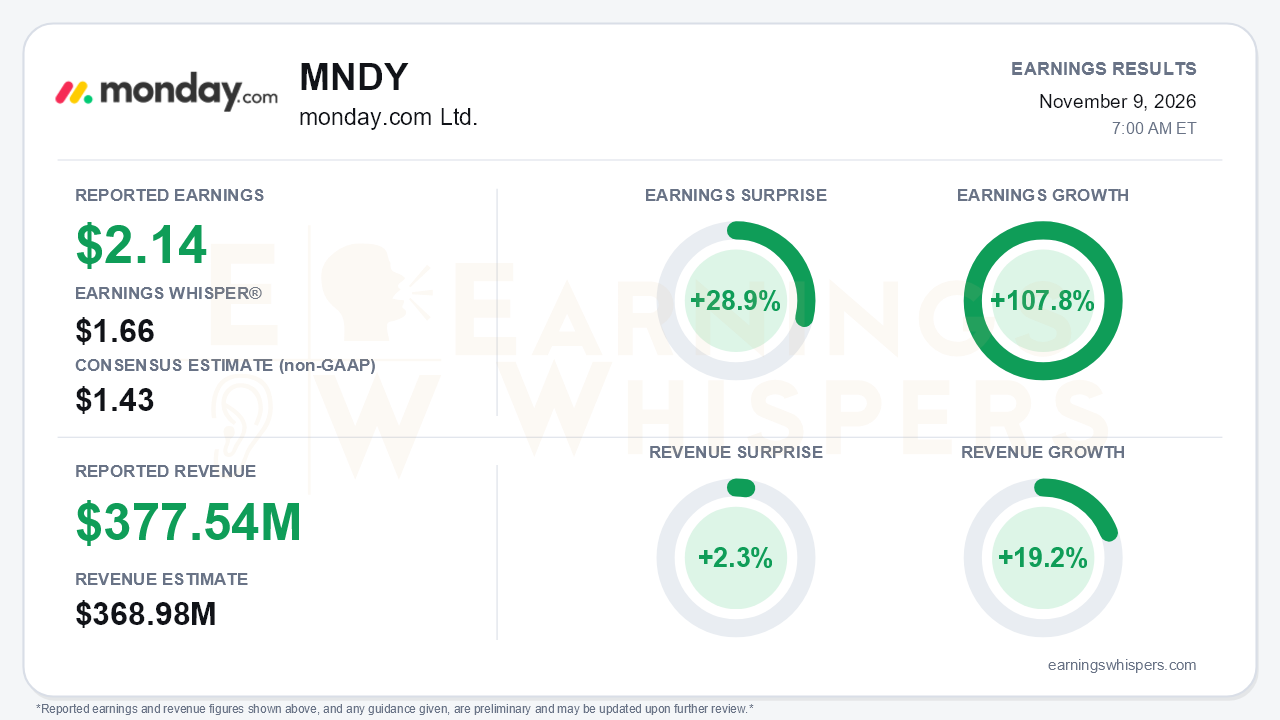
monday.com (NASDAQ: MNDY) delivered a large third-quarter earnings beat. Non-GAAP EPS of $2.14 topped the $1.43 consensus by 28.9% and cleared the $1.66 Earnings Whisper number by a wide margin. Earnings grew 107.8% year over year. Revenue of $377.54 million beat the $368.98 million consensus by 2.3% and grew 19.2%. The headline, however, is not the story. Growth has stepped down from 24% in Q1 to 22% in Q2 to 19% in Q3. Fourth-quarter revenue guidance of $380 million to $382 million implies only about 14% growth and roughly 1% sequential expansion, below expectations. That is the central tension: a company posting record profitability while telling investors its top line will keep decelerating for several more quarters.
The quality of the beat deserves scrutiny. Non-GAAP operating margin hit a record 24%, up from 15% a year ago and well above the 16% management had guided. That expansion came largely from the July restructuring, which cut roughly 20% of the workforce for about $100 million in gross savings. Headcount fell by 690 people in the quarter to 2,479. Non-GAAP sales and marketing expense actually declined year over year, to $145.4 million from $151.8 million.
The buyback also flattered per-share results. After $735 million of share repurchases this year, diluted shares fell to 43.8 million from 53.3 million. As a result, EPS more than doubled while non-GAAP net income rose to $93.6 million from $61.9 million.
Cash generation moved the other way. Operating cash flow fell to $20.4 million from $95.1 million. Adjusted free cash flow of $63.0 million, a 17% margin versus 29% a year ago, excludes $47.2 million of restructuring payments. The release carries a full-year adjusted free cash flow outlook of $282 million to $288 million, essentially a narrowed version of the prior $280 million to $290 million range. Still, the call analysis noted management did not reaffirm that target on the call.
The call marked a sharp shift in tone. In Q2, management said there was no material change in sales cycles and highlighted record large-customer additions. This quarter brought a different set of messages:
- Enterprise cycles are elongating as customers scrutinize AI spending.
- The CRO said disruption from the layoffs "lingered longer than we thought."
- SMB logo churn rose and SMB net adds weakened, with top-of-funnel traffic disrupted by AI-driven search and a Gen-Z marketing experiment that underperformed.
- Net dollar retention slipped to 108% and is now expected to reach 107% by year-end. That compares with roughly 108% guided on the Q2 call and a stable 110% outlook at the start of the year.
- Net adds and retention among $50,000-plus customers softened sequentially.
- New products (CRM, Service and Dev) stalled at 11.7% of ARR.
- The CFO said stability is "a few quarters" away, likely extending through 2027.
Bulls are not without ammunition. The enterprise mix keeps improving:
- Customers above $100,000 in ARR grew 33% to 2,127, and those above $500,000 rose 58% to 123.
- Remaining performance obligations increased 27% to $946 million, and current RPO grew 22%, ahead of revenue growth.
- Multi-product adoption among $50,000-plus accounts climbed to 41% from 29%.
- The largest deployment now exceeds 87,000 seats.
AI is also becoming measurable. AI ARR reached $36 million, more than 30% of $50,000-plus accounts pay for AI credits, and agents have logged over 6 million interactions. The new Monday Frontier forward-deployed engineering group and the Harmony voice-agent platform are credible enterprise catalysts. At $36 million, though, AI ARR is a small slice of a business nearing $1.5 billion in annual revenue, far too small to offset SMB and retention softness in the near term. Frontier is also a services-heavy effort that management's own commentary links to margin dilution. That helps explain why the Q4 operating margin guide normalizes to about 18%. Full-year non-GAAP operating income guidance of $268 million to $270 million is up sharply from $165 million to $175 million at the start of the year. That improvement is a cost story, not a demand story.
Investor sentiment barely moved, edging from -0.4534 to -0.4445. It remains firmly negative, suggesting the crowd entered the report skeptical rather than complacent. Price action has been volatile:
- Ahead of the report, shares traded at $87.93, about 8.0% above the $81.40 open after the August report and 6.3% above the 200-day moving average.
- The stock fell to $73.16 in late September, then surged to $110.77 on October 22.
- It entered earnings roughly 20% off both extremes, having given back about half of that rally.
The Earnings Whispers trend readings are mixed. Sequential growth is positive, but AVWAP is negative. Those readings fit a stock caught between margin upside and top-line erosion.
The bottom line is that monday.com's quarter was engineered more by cost cuts and a shrinking share count than by improving demand. The record margin and sizable EPS beat are real. But the guide to 14% growth, falling net retention, rising SMB churn and management's admission that stabilization may take until 2027 shift the debate from profitability to whether growth can find a floor. Enterprise momentum, RPO strength and early AI monetization keep a credible long-term story intact. For now, investors are being asked to accept slower growth and weaker cash conversion in exchange for margins that management itself expects to normalize next quarter.
Read our earnings preview for monday.com Ltd.: https://www.earningswhispers.com/article/MNDY/22576
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-12 |
