Lincoln Educational's August Start Class Is The Real Test After A 36% Slide
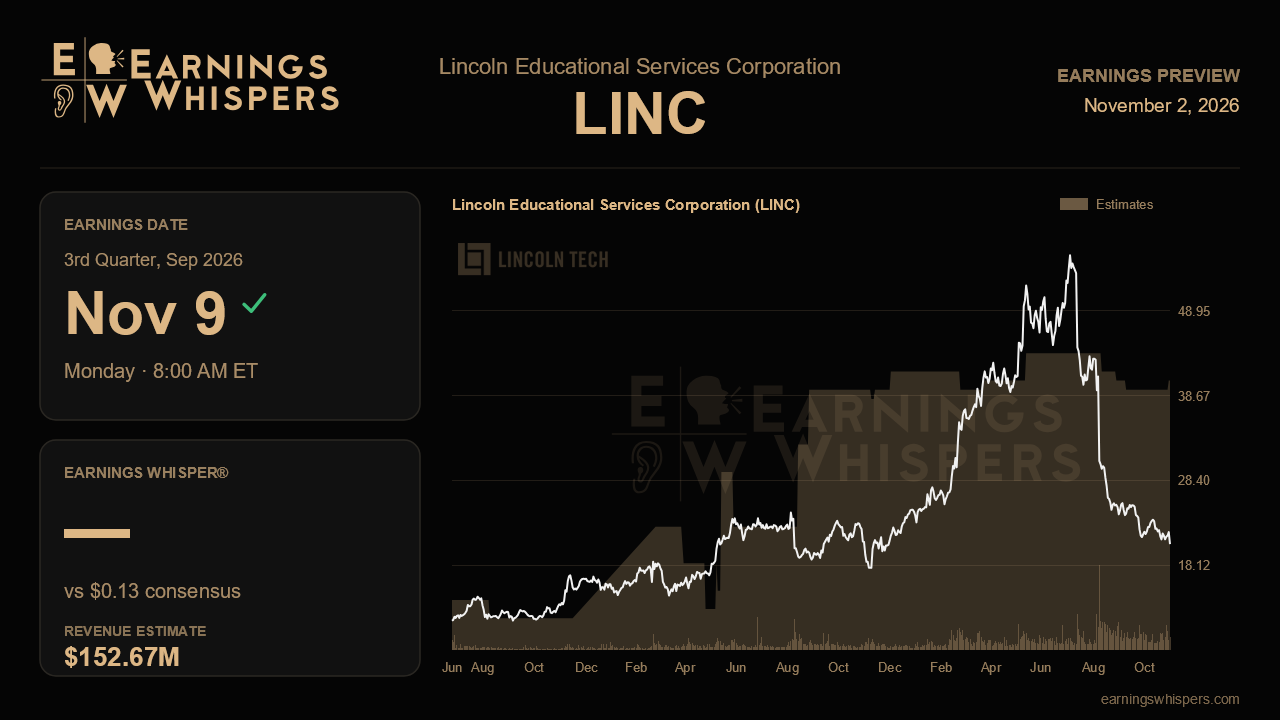
Lincoln Educational Services heads into its third-quarter report with a stock that has lost more than a third of its value since the last update, and the reason has little to do with the income statement. Revenue and profit were still growing briskly in the second quarter. What spooked the market was student starts, the company's most important leading indicator, which slowed to roughly 1% growth after a 19.5% jump in the first quarter. Management argued the shortfall was temporary and promised that August would be the largest start month in company history. This report, due before the open on November 9, is where that promise either holds up or falls apart.
The Street expects earnings of $0.13 per share on revenue of about $152.7 million. That implies sales growth of around 8% from a year ago, a sharp step down from the 22% pace of the first half, while earnings are forecast to fall roughly 35% from the $0.20 posted in the year-ago quarter. Part of the profit squeeze is structural. Lincoln is spending heavily on new campuses, which ran at a $3.1 million loss in the second quarter, and capital spending guidance was lifted to $95 million to $100 million, which brings higher depreciation that weighs on net income even when adjusted EBITDA looks healthy. For the full year, management reaffirmed earnings of $0.74 to $0.83 per share on revenue of $590 million to $600 million, along with adjusted EBITDA of $76 million to $80 million. Consensus sits at $0.78 and about $596 million, essentially the midpoint of both ranges, so analysts have not yet bet against the company's outlook.
The core question is starts. Management's full-year target of 10% to 14% start growth now depends heavily on the back half, and specifically on a high school recruiting push that was expected to lift third-quarter high school starts by about 15%. A strong August class would validate the view that the second quarter was a hiccup caused by financial aid packaging timing and other temporary factors. A soft one would point to more persistent problems. Two of the explanations offered last quarter deserve particular attention. One is AI-driven search disrupting the volume and quality of prospective student leads, which Lincoln is trying to address by reworking its website. The other is a wave of student loan defaults leaving some applicants ineligible for federal aid. Neither sounds like it fixes itself in a single quarter, so any update on show rates and lead conversion will matter as much as the headline start number.
There are cushions. Attrition improved by 150 to 200 basis points last quarter, which supports the average student population even when new enrollment slows. Cash generation has also been striking, with first-half operating cash flow of $26.6 million versus a cash outflow a year earlier. Keeping that momentum is important because the expanded capital plan, including the $18.8 million Melrose Park building purchase and the new Suitland and Tempe campuses, is expected to leave about $20 million of debt on the books at year-end rather than none.
Sentiment has drifted from mildly bearish before the last report to essentially neutral, which suggests the selling may have exhausted some of the pessimism. The chart tells a harsher story. At $20.68, the stock sits just above its post-earnings low of $20.31 and far below its 200-day moving average near $35.86, a long way from the $36 to $56 range it traded in the prior quarter. That kind of drawdown means the bar is low on sentiment but high on proof.
Ultimately, the quarter's earnings figure is unlikely to decide the stock's direction. If Lincoln can show that August delivered and that full-year start guidance remains within reach, the growth narrative behind its expansion plans stays intact. If starts stay stuck near flat, the market will question whether the company's demand engine has stalled just as it is committing record sums to new campuses.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-29 | |
| Oct-26 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-28 | |
| Sep-23 |
