Lincoln Educational Beats As Starts Rebound To 14%, But An Unchanged Profit Outlook Leaves A Halved Stock Waiting For Proof
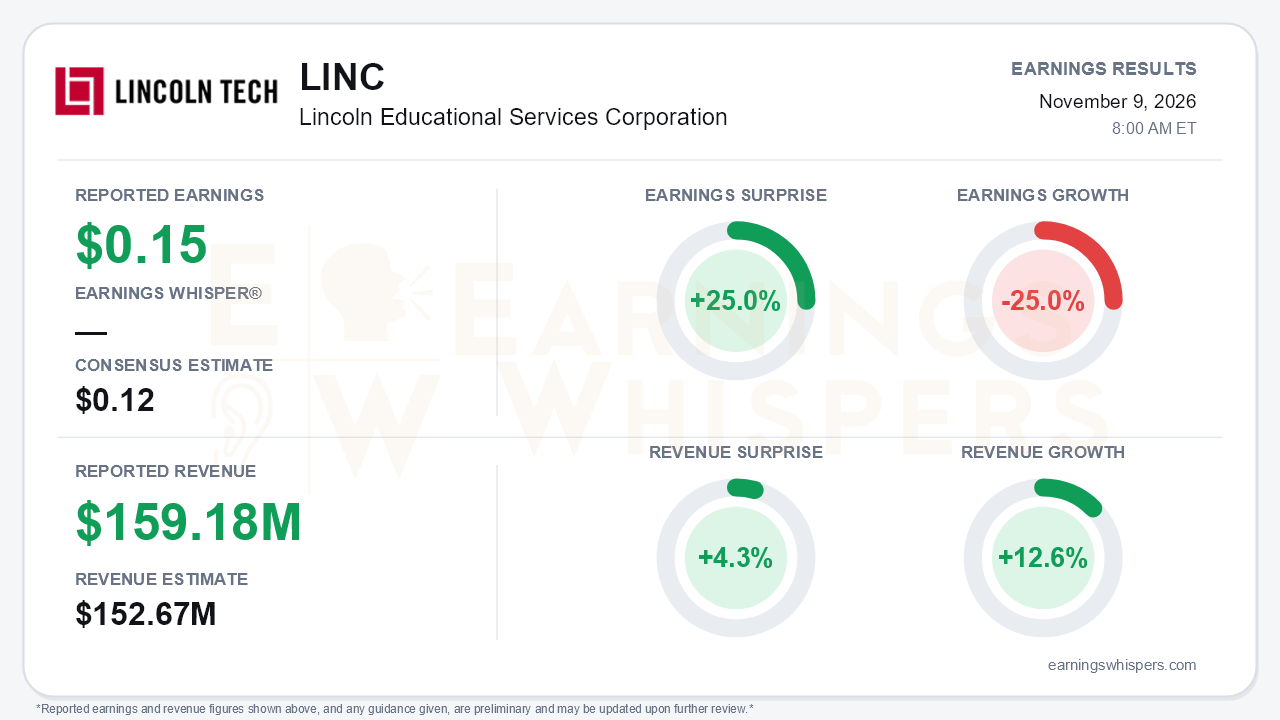
Lincoln Educational Services delivered the quarter the market needed after a damaging summer, though not yet the one that fully repairs the story. The company reported third-quarter earnings of $0.15 per share on revenue of $159.18 million, beating the $0.12 consensus by 25.0% and the $152.67 million revenue estimate by 4.3%. Revenue grew 12.6% year over year. On Earnings Whispers' normalized basis, earnings fell 25.0% year over year. That conflicts with the company's GAAP presentation, where diluted EPS rose to $0.15 from $0.12 and net income increased 24.1% to $4.7 million. Investors should be aware that the two bases point in different directions. The more important development is operational. Student starts rebounded 14.2% after rising just 1% in the second quarter, the stumble that preceded the stock's collapse.
The quality of the beat holds up better than the headline growth rate suggests, but it needs some unpacking. The 14.2% start figure is on an adjusted basis. It excludes 2,764 starts from July 1, 2025, to align with a calendar shift. On an unadjusted basis, starts fell 20.1%. Management cited organic start growth of nearly 5%, double-digit growth in high school starts, and a roughly 200-basis-point improvement in the start rate, driven by better financial aid packaging and admissions engagement. Revenue growth of 12.6% marked a 14th straight double-digit quarter. It was still a clear deceleration from 22.4% in the second quarter and 22.5% in the first, partly because of the same calendar comparison. Adjusted EBITDA rose 30.8% to $17.4 million, with margin up about 150 basis points to roughly 11%. That measure now includes new-campus losses, with prior periods recast, which makes the improvement more credible. Operating cash flow of $34.9 million for the quarter was also a genuine strength.
The call kept a credible growth story intact, but the cost picture is where bears have legitimate ammunition. Cost per lead is still running about 20% above last year. Management acknowledged that lead flow disrupted by AI-driven search is "not back to anywhere close" to prior levels. Better conversion held cost per start roughly flat in the third quarter, but management expects it to rise above prior-year levels in the near term. Expense lines show the strain as well:
- Educational services and facilities costs rose 17.2%, outpacing revenue.
- Laptop prices are higher.
- Depreciation jumped to $8.0 million from $5.5 million as the campus build-out moves onto the income statement.
That is the central tension in the guidance. Full-year revenue guidance rose to $600-$605 million from $590-$600 million. Adjusted EBITDA guidance of $76-$80 million, net income of $23-$26 million, and EPS of $0.74-$0.83 were only reiterated. Management attributed the lack of flow-through to cost inflation across marketing, laptops and medical expenses, plus retention investments. The top of the start-growth range was also trimmed, to 10%-12% from 10%-14%. With $45.6 million of adjusted EBITDA and $0.35 of EPS through nine months, the reiterated targets depend heavily on a strong fourth quarter.
The forward catalysts are tangible:
- The Hicksville, New York campus begins its first class in November.
- Suitland, Maryland is targeted for late 2027. Management framed it at roughly $10 million of capex for about $15 million of revenue and $5 million of EBITDA at maturity.
- Tempe, Arizona, the company's first campus in the state, is slated for 2028.
- A new ABB partnership trains electrical technicians for data-center maintenance.
Capital is getting tighter, however. Management said existing campuses have no space left to replicate HVAC and electrical programs, so future growth depends on new sites, program swaps and teach-outs. Capex guidance remains $95-$100 million. Long-term debt went from zero to $24.8 million, reflecting the mortgage and revolver borrowings. Liquidity slipped to $135.6 million from $143.2 million after the $18.8 million Melrose Park purchase and about $21 million of buybacks. Even so, the board added $30 million to the repurchase authorization and amended the revolver to permit further buybacks, a clear signal that management views the shares as undervalued.
The market has priced in considerable skepticism. Shares fell 45.8% from the $32.58 opening after the August report to $17.66 as of November 6. They sit about 50% below the 200-day moving average and just 3.2% above a 52-week low of $17.11 set that same day, ahead of this report. The stock has round-tripped from an inter-earnings high of $35.80 struck on the day of the prior release. Investor sentiment remained slightly negative but improved, moving to -0.028 from -0.077, a modest shift toward neutral rather than a decisive turn. Earnings Whispers trend signals show price and AVWAP readings still negative, while sequential growth has turned positive. That combination fits a business stabilizing beneath a stock that has not.
The bottom line is that Lincoln answered the most urgent question: the second-quarter start collapse looks like a stumble, not a structural break. The answer arrived with caveats. Lead generation remains impaired, costs are absorbing the revenue upside, and the reiterated profit outlook leans on the fourth quarter. A stock trading near its lows gives the rebound room to matter, but sustained start growth and stable acquisition costs will need to show up in the next report, not just in a raised revenue range.
Read our earnings preview for Lincoln Educational Services Corporation: https://www.earningswhispers.com/article/LINC/22575
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Oct-29 | |
| Oct-26 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 |
