NESR's Sell-Off Leaves One Question: Can The Jafura Ramp Defend The $2 Billion Floor?
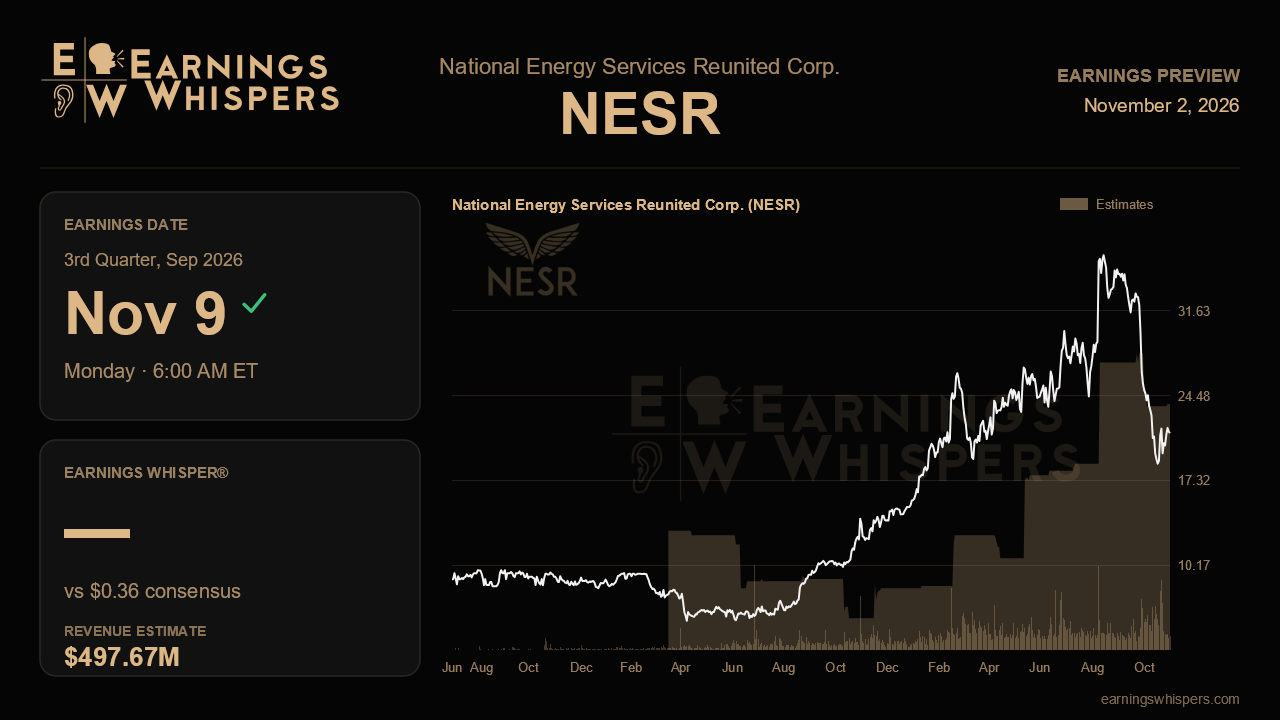
National Energy Services Reunited heads into its third-quarter report with a striking disconnect. Three months ago management delivered its most confident call in a year, hitting its founding $2 billion revenue run-rate goal two quarters early and turning that figure into a minimum for full-year 2026. Since then the stock has lost about a third of its value. The November 9 release, due before the open, is the first real chance to show whether the market's retreat reflects something the operations will confirm, or simply a loss of nerve.
The Street is not asking for a repeat of the second quarter. Consensus calls for EPS of $0.36 on revenue of $497.7 million, below the record $0.44 and $520.8 million posted last time. On a year-over-year basis the picture still looks explosive, with revenue expected to rise roughly 68% and earnings to more than double from $0.16, but sequentially analysts are modeling a step back of about 4% in sales. That matters because of the arithmetic behind management's raised target. First-half revenue totaled roughly $925 million, so reaching $2 billion requires about $1.07 billion in the back half. A third quarter near consensus would leave the fourth quarter needing something close to $575 million, a demanding jump. In other words, the Street appears to be sitting at the cautious end of what management's floor implies, which gives the company room to beat but also makes any softness in the quarter a direct challenge to the full-year promise.
The operational swing factor is Saudi Arabia's Jafura gas program, which drove the second-quarter surge with four frac fleets running and a fifth shipped. Investors should look for confirmation that the fifth fleet is deployed and earning, and for evidence that utilization on the existing fleets held up rather than proving lumpy. The newer catalysts deserve a check-in too: the Kuwait Ahmadi Innovation Valley technology framework, fresh awards in Kuwait, the UAE and North Africa, and the Syria opportunity. None needs to show up in revenue yet, but commentary on timing would help support management's claim that its $3 billion three-year goal is arriving faster than planned.
Margins and cash are the other tests. The record 20.4% adjusted EBITDA margin came despite roughly 80 basis points of extra freight and logistics costs tied to regional disruption, and full-year margin guidance was only broadly in line with 2025. Holding near the low 20s while Iraq remains a drag would validate the story; slippage would suggest the conflict is costing more than assumed. Higher interest expense and a roughly 24% tax rate already trim the earnings conversion, so the 9% to 9.5% net margin target is worth tracking. Cash flow needs careful reading as well, since about $40 million of last quarter's free cash flow was working-capital timing that could reverse. With capex lifted to $210 million to $215 million and a $0.10 quarterly dividend slated for the fourth quarter, steady normalized free cash flow and leverage near 0.4x would reinforce the shareholder-return pitch.
Sentiment has cooled sharply, sliding from strongly bullish before the last report to only mildly positive now. The chart tells the same story: after spiking to about $37 following the prior release, shares have collapsed to $21.31, well below the 200-day moving average of $25.53 and not far above the post-earnings low of $18.45. That lowers the bar for a relief move but also signals that the market wants proof, not adjectives.
The central issue is whether the third quarter keeps NESR on a credible path to its $2 billion minimum. A print that shows Jafura's fifth fleet contributing, margins holding despite freight costs, and management reaffirming the floor would argue the sell-off overshot. A sequential dip deeper than expected, or any hedging on the full-year target, would suggest the market's skepticism was warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 12 hours | |
| Oct-12 | |
| Oct-08 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Aug-03 | |
| May-18 | |
| May-12 | |
| May-11 | |
| May-11 |
