NESR Edges Past Q3 Estimates, But Trimmed Targets, Rising Capex And Cash Burn Reset The Growth Story
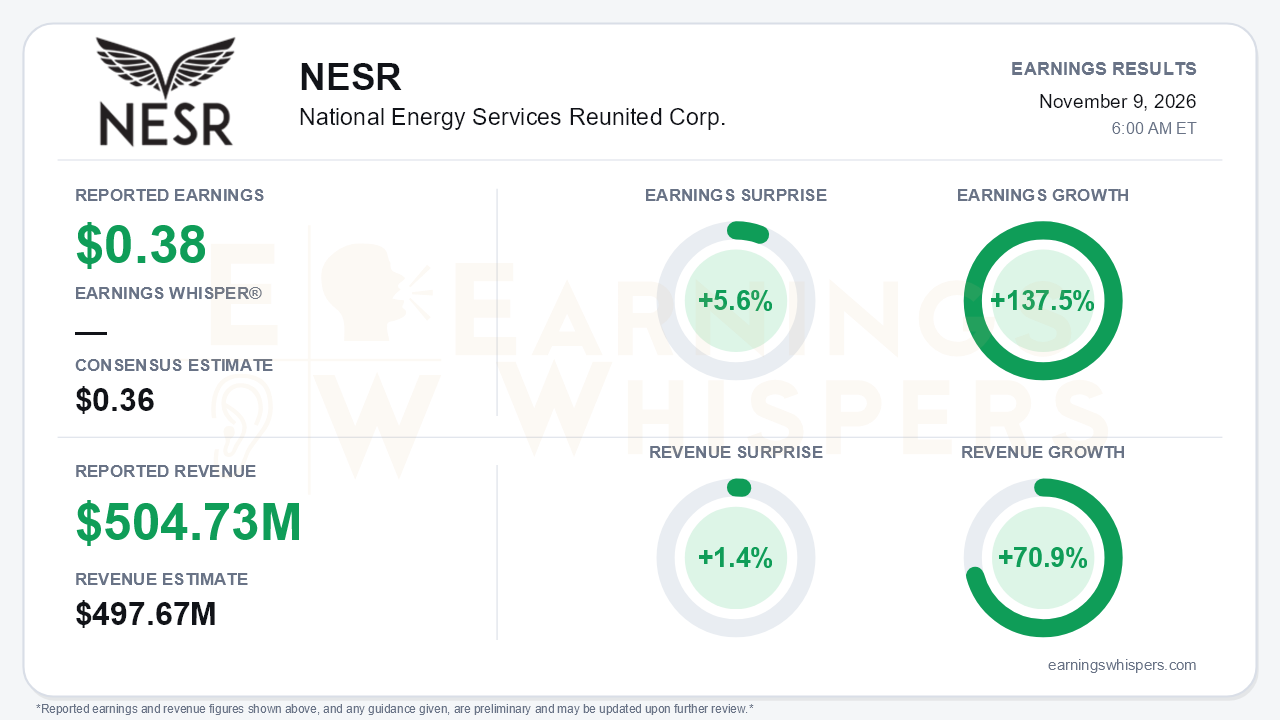
National Energy Services Reunited cleared a modest bar in the third quarter, but the beat matters less than what management did to the full-year outlook. Adjusted EPS of $0.38 topped the $0.36 consensus by 5.6% and rose 137.5% year over year. Revenue of $504.7 million beat expectations by 1.4% and grew 70.9%. Those are strong year-over-year figures, yet this was the first call of 2026 in which NESR trimmed targets for revenue, EBITDA margin, net margin and free cash flow while raising capex again. That is the central tension: headline growth remains exceptional, but the trajectory has clearly bent.
The sequential picture is weaker than the beat implies. Revenue fell 3.1% from the record second quarter, a sharp reversal from Q2's 28.7% sequential gain. Adjusted EBITDA dropped 9.7% to $95.9 million, and the margin slipped to 19.0% from 20.4%. In Q2, management had pointed to sequential margin improvement, so the quarter moved the wrong way against its own outlook.
GAAP results took a harder hit. Diluted EPS was $0.33, down from $0.43 in Q2, after $5.3 million of charges. Those included a $2.9 million impairment on a technology investment and a $1.1 million credit-loss provision tied to a North African customer. Year over year, adjusted EBITDA grew 49.9%, well below the 70.9% revenue growth. That gap points to margin compression even as the top line expanded.
The quality of cash generation deserves the most scrutiny. Free cash flow was negative $45.9 million, versus positive $99.9 million in Q2, and operating cash flow was slightly negative for the quarter. Management attributed the swing to slower collections and a roughly $45-50 million contingency inventory build.
The balance sheet shows the strain. Unbilled revenue has climbed about $100 million and receivables about $87 million since year-end, offset largely by a $225 million increase in payables. The leverage figures need careful reading:
- The release says net debt of $160.5 million is down from $185.3 million at year-end.
- The call noted it rose from $99.6 million in Q2, lifting net leverage to 0.44x from 0.30x.
Both are accurate, but the sequential deterioration is the more current signal.
The call explained the softness through external disruption. September security escalation in the GCC triggered offshore and some land rig suspensions. Iraq activity remains impaired, and IOCs are unlikely to return until the conflict is fully resolved. About 110 basis points of the margin decline came from $5.5 million of freight costs.
Guidance moved lower across the board:
- FY26 revenue is now about $2 billion "plus or minus," versus a $2 billion "minimum" in Q2.
- EBITDA margin is roughly 20%, versus the 2025 level of 21.3% guided on earlier calls.
- Net margin is about 8%, from 9-9.5%.
- FCF conversion is 30-35%, from 35-40%.
- Capex keeps climbing, now $220-225 million versus about $165 million guided in Q4 FY25.
The 3B3 target (a $3 billion revenue run-rate) is now framed as an exit-2028 goal, after earlier talk of doubling by 2027. Large Kuwait and UAE tender awards have slipped for a third straight quarter, and pricing pressure on new contracts persists.
The call did preserve a credible longer-term growth narrative. The bullish elements include:
- A $200 million direct lithium extraction contract in Saudi Arabia, with first lithium due by end-2027.
- A fifth Jafura frac fleet now in-country and potentially active late in Q4.
- ROIA drilling-platform commercialization slated for next quarter.
- North Africa guided to 20-30% growth in 2027.
- A completed ~$747 million refinancing and the inaugural $0.10 dividend.
- Trailing ROCE improved to about 13.7%.
Management still expects 2027 revenue growth even with flat Middle East spending. However, its 2027 margin framing of roughly 20% or slightly better depends heavily on how the conflict evolves.
The market had already repriced much of this before the report. Shares fell 37.6% from the $32.00 open after the August report to $19.96. That is 46% below the $36.94 52-week high set just days after that release, only 8.2% above the October low, and about 22% below the 200-day moving average. Price and AVWAP trend readings are both negative. Investor sentiment collapsed from 0.65 to 0.06, a substantial shift from clearly optimistic to roughly neutral. Expectations are now far lower than the earnings surprise alone suggests.
The bottom line is that NESR delivered a technical beat inside a deteriorating quarter. Its operating story is now more dependent on regional stability, tender timing and working-capital discipline than it was three months ago. The lithium win and Jafura expansion keep the growth case alive. But bears have legitimate ammunition in the guidance cuts, rising capex, negative free cash flow and repeatedly delayed targets, and the stock's slide shows investors have already stopped giving management the benefit of the doubt.
Read our earnings preview for National Energy Services Reunited Corp.: https://www.earningswhispers.com/article/NESR/22578
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Nov-02 | |
| Oct-12 | |
| Oct-08 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Aug-03 | |
| May-18 | |
| May-12 |
