Vivid Seats Must Prove Its Back-Half Growth Promise Survives The World Cup Hangover
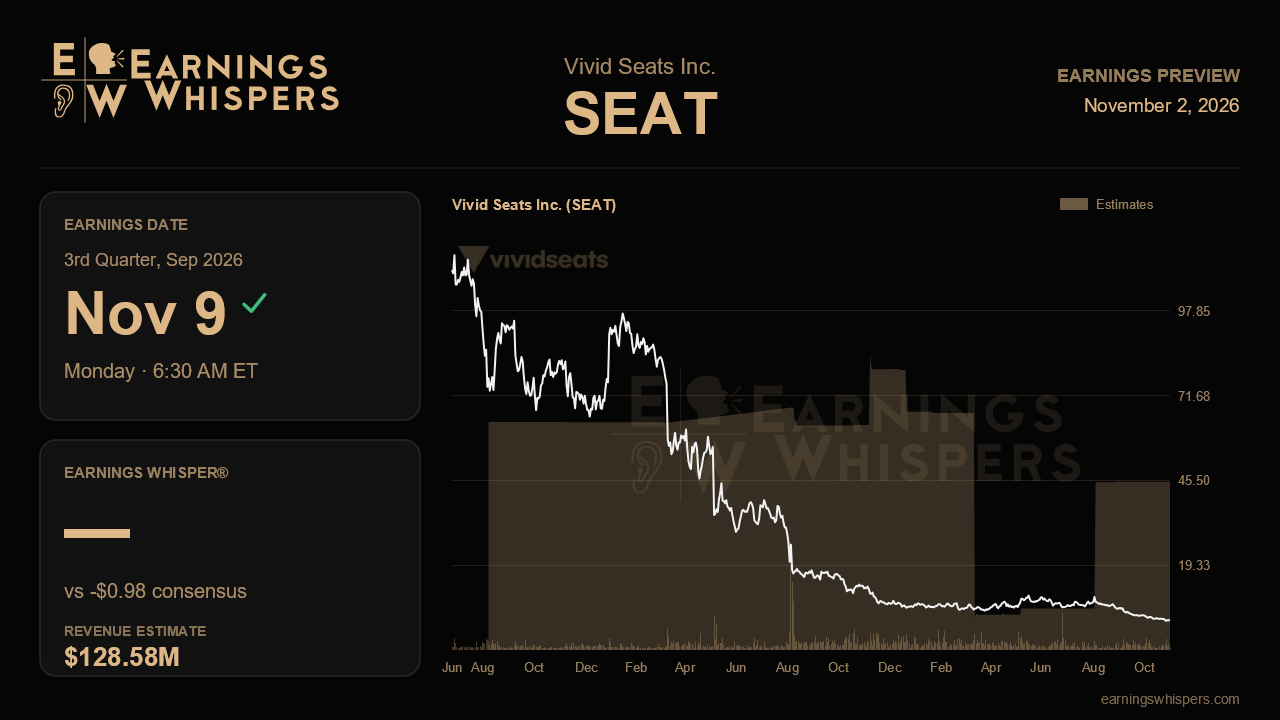
Three months ago, Vivid Seats delivered its most confident quarter in a year: a World Cup-fueled beat, higher full-year targets and a private label business that finally turned from drag to driver. The market's response has been brutal anyway. Shares have collapsed about 72% since that report, to $2.31, against a roughly flat S&P 500. That gap between an improving operating story and a disintegrating stock price is what makes the November 9 report, due before the open, so consequential. The company now has to show that its recovery was more than one tournament deep.
The Street's bar is modest on the top line. Consensus calls for revenue of $128.6 million, down 5.7% from $136.4 million a year ago and slightly below the $129.9 million posted last quarter. Analysts expect a loss of $0.98 per share, a sharp narrowing from the $1.91 loss in the year-ago period and better than last quarter's $1.30 loss. In other words, the forecast leans on cost discipline and margin repair rather than growth, and that framing sits awkwardly with management's repeated promise of a return to year-over-year growth in the second half of 2026. A revenue decline in the first back-half quarter would not break that thesis by itself, but it would push the burden onto the holiday quarter.
The full-year guidance math sharpens the test. Management lifted its adjusted EBITDA outlook to $34 million to $40 million and raised the floor of its gross order value range to $2.3 billion to $2.6 billion. With roughly $22 million of adjusted EBITDA banked in the first half, the company needs about $12 million to $18 million across the final two quarters. That looks achievable on paper, given the third quarter of last year produced only about $5 million, but it requires the business to hold its profitability without the World Cup, which accounted for a mid-teens percentage of second-quarter order value. Marketplace GOV climbed to $659 million last quarter; a sharp step back toward the $581 million to $618 million band of prior periods would reveal how much of the recent momentum was borrowed from a single event.
The more durable evidence should come from private label. Having lapped the loss of a large customer in July 2025, the segment grew 16% sequentially last quarter, helped by a new partner that management said was beating expectations. Continued sequential growth there would be the cleanest confirmation that the recovery has structural legs. Take rates also deserve scrutiny. World Cup transactions carried below-average take rates, so a normalizing mix could support margins even if volumes soften. Against that, management flagged rising competition in theater, ongoing weakness in Las Vegas and low-end leisure, elevated marketing from its largest rival and new regulatory noise in a handful of states. Any sign those pressures are spreading would undercut the improving tone. Early traction from the Skybox broker-to-broker marketplace would be a welcome bonus, as would visibility into fourth-quarter concert on-sales, which were still unset at the last call. Cash, which slipped to $137 million on seasonal working capital, should ideally stabilize.
Sentiment has thawed, moving from a decidedly bearish reading before the last report to a slightly bullish one now, though that hardly signals conviction. The chart tells a harsher story. The stock trades far below its 200-day moving average of $6.40 and sits just above its post-earnings low of $2.03, a long way from the $9.59 high. Expectations embedded in the price appear deeply pessimistic.
That sets up the central question. If Vivid Seats can show that non-World Cup demand, private label growth and steadier take rates keep the full-year targets intact, the disconnect with the share price becomes hard to ignore. If the third quarter instead suggests the guidance raise rested mostly on a once-in-four-years tournament, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-28 | |
| Oct-08 | |
| Sep-09 | |
| Aug-19 | |
| Aug-04 | |
| Aug-03 | |
| Jul-21 | |
| May-05 | |
| May-04 | |
| Apr-22 | |
| Apr-16 | |
| Mar-13 | |
| Mar-12 | |
| Mar-11 |
