Telos Must Prove Its Margin Pivot Can Survive A Shrinking Top Line After 43% Rally
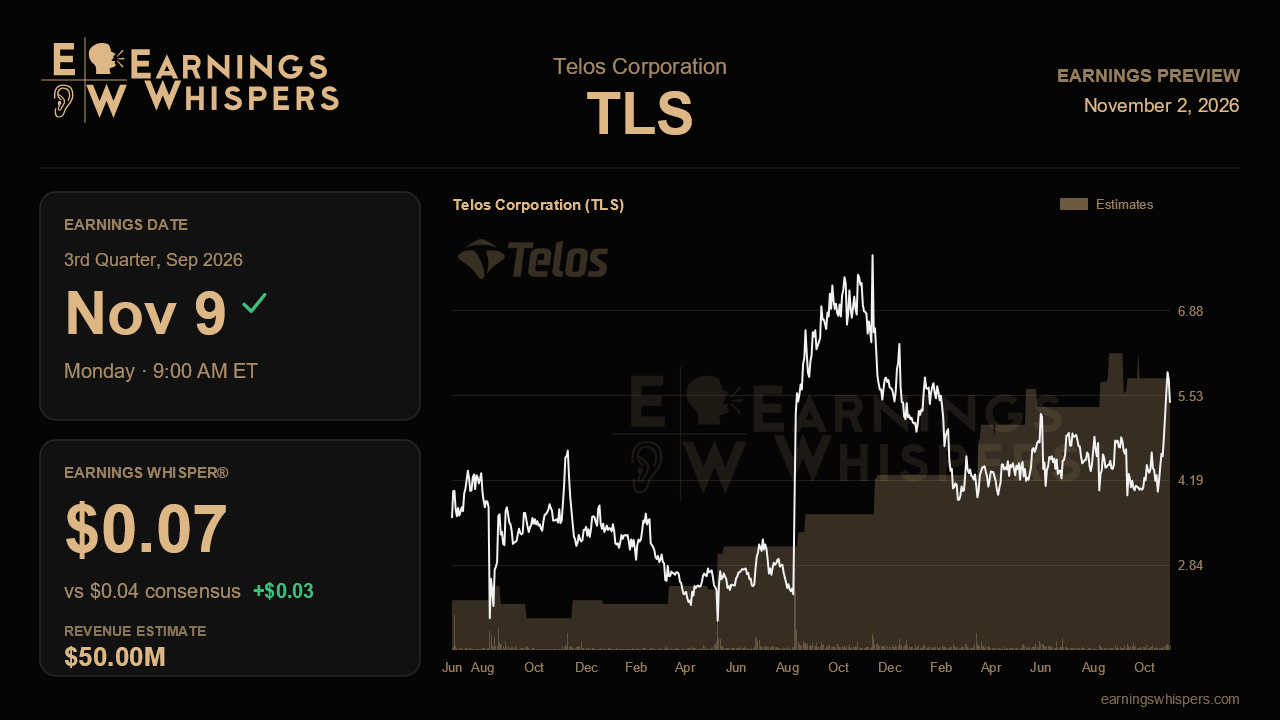
Telos heads into its third-quarter report with an unusual pitch: it is getting smaller on purpose and asking investors to pay up for it. Last quarter management chose to walk away from roughly $33 million a year of thin-margin third-party software resale and raised every profitability target while trimming revenue. The stock has since climbed 43%, so the September quarter is less about whether Telos can grow and more about whether the quality-over-quantity story holds when the revenue line slips backward.
The Street is looking for non-GAAP earnings of $0.04 a share on revenue of about $50.0 million, which would be a 2.8% decline from the $51.4 million reported a year ago. That revenue figure sits almost exactly at the midpoint of management's $49.2 million to $50.6 million guidance, so analysts are not reaching. The Earnings Whisper of $0.07 is notably above consensus, a sign that the more aggressive expectations are for another profit beat. That would fit the recent pattern. In the second quarter, revenue of $47.7 million cleared the top of guidance and adjusted EBITDA of $6.9 million beat a $5 million to $6 million range, with margin jumping to 14.4% from about 1% a year earlier.
The catch is that management flagged a softer quarter on margins before the improvement story really kicks in. Cash gross margin is guided to 37.5% to 38.5%, down from 40.6% in the second quarter, reflecting contingency reserves on fixed-price contracts and the usual second-half lull in TSA PreCheck enrollments. Landing at or above the top of that range would suggest the reserves were conservative and would make the full-year cash gross margin target of 39% to 40% look comfortable. A result near the bottom would raise questions about whether the raised EBITDA outlook of $23.6 million to $28.6 million leaves enough cushion. Free cash flow also matters: Telos has posted six straight quarters with a free cash flow margin above 12%, and a seventh would reinforce that operating discipline, including another round of expense cuts, is structural rather than episodic.
The bigger strategic questions point toward 2027. The software resale wind-down begins in the fourth quarter and should add about 600 basis points to run-rate cash gross margin, with another roughly 400 basis points expected in the back half of 2027 as prepaid PreCheck costs finish rolling off. Any updated detail on timing, or a fourth-quarter outlook that keeps full-year revenue inside the $187 million to $195 million range, would validate that plan. On the growth side, management said award decisions on a proposal portfolio of more than $500 million in total contract value were expected in the second half. Concrete wins would go a long way; continued silence, or blame placed on government budget timing, would push the recovery further out. Progress on PreCheck share gains and the post office pilot rollout is the nearer-term demand signal to watch.
The mood around the report has cooled even as the share price has run. Sentiment has slipped from mildly bullish before the last report to moderately bearish now, which suggests some skepticism that the rally has outpaced fundamentals. The stock sits well above its 200-day moving average near $4.53 and around the top of last quarter's trading range, though still roughly 9% below its post-earnings high of $5.95, so this is not a breakout setup. Management's mention of elevated inbound acquisition interest adds a speculative layer that may be supporting the price.
Ultimately, the quarter hinges on whether Telos can absorb the expected margin dip and a modest revenue decline while keeping its profitability and cash flow trajectory intact. If it does, the case for a leaner, higher-margin 2027 strengthens. If margins slip further than guided or the pipeline stays stuck, a stock that has already rewarded the pivot has little room for disappointment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-11 | |
| Sep-11 | |
| Sep-11 | |
| Sep-08 | |
| Sep-03 | |
| Aug-31 | |
| Aug-10 | |
| Aug-10 |
