Telos Misses The Whisper But Delivers Its Strongest Beat-And-Raise Of The Year As Xacta Demand Builds
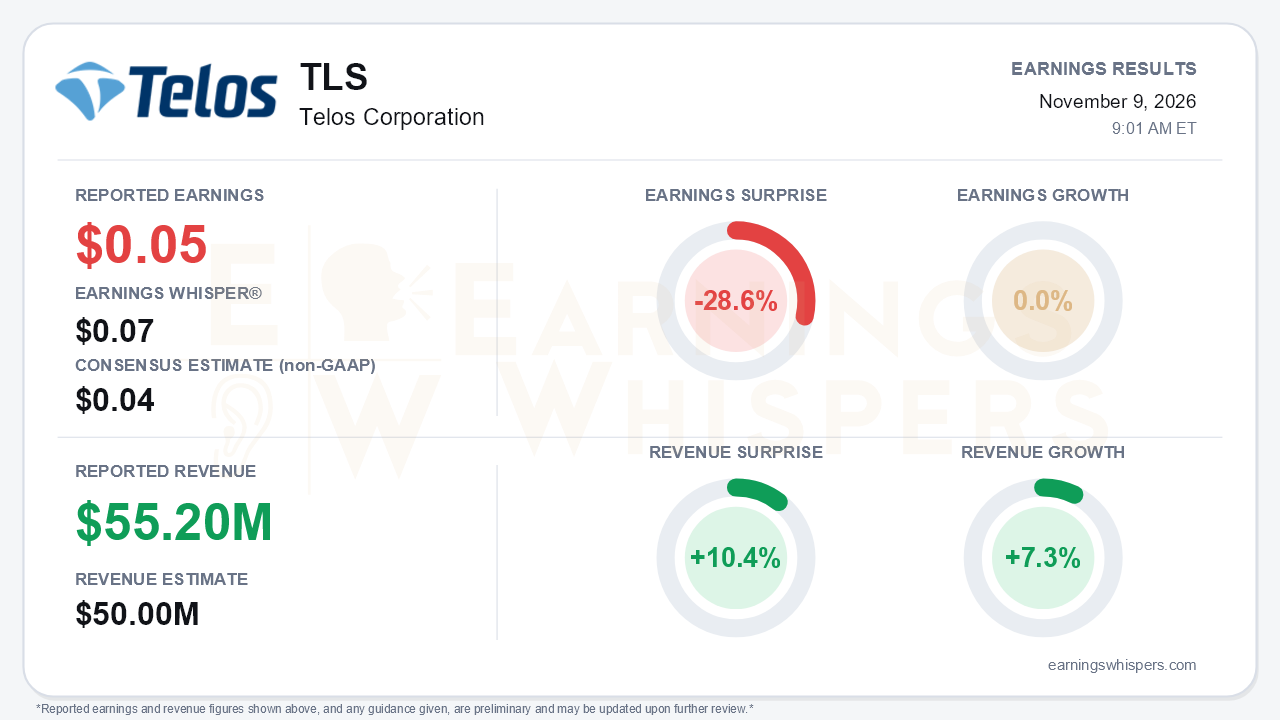
Telos Corporation (NASDAQ: TLS) reported third-quarter earnings of $0.05 per share on revenue of $55.2 million. That was a penny above the $0.04 consensus but short of the $0.07 Earnings Whisper number, a 28.6% shortfall against the bar investors were actually using. EPS was flat year over year at 0.0% growth. Revenue rose 7.3% and topped the $50.0 million consensus by 10.4%. The EPS line is the least flattering part of the report. Beneath it, Telos produced its biggest operating outperformance of the year, raised full-year guidance well above estimates, and disclosed a meaningful new wave of Xacta bookings. That is the central tension: a whisper miss on earnings alongside a fundamental story that clearly improved.
The quality of the operating beat stands out. Revenue cleared management's own $49.2-50.6 million guide by a wide margin. Adjusted EBITDA reached a record $10.6 million, the highest since the 2020 IPO, against guidance of just $6.0-6.8 million. The adjusted EBITDA margin expanded to 19.2%, up from 14.4% in Q2 and 16.5% in Q1. Cash gross margin of 43.1% beat the 37.5-38.5% guide and improved from 40.6% in Q2. Free cash flow was $7.4 million, a 13.4% margin and the seventh straight quarter above 12%. Buybacks stepped up to $5.7 million from $4.7 million in Q2 and $2.2 million in Q1. Flat EPS against that EBITDA performance suggests below-the-line items and the higher-than-planned operating expenses management acknowledged absorbed part of the gain.
The more important change came on the call. Management disclosed $58 million of net new Xacta and professional services bookings in information assurance. These are separate from the roughly $500 million proposal pipeline investors have been waiting on. The awards are described as recurring and higher-margin, and they are expected to contribute about $6 million of revenue in 2026 and about $20 million in 2027. Wins span the Air Force intelligence community, the Office of Naval Intelligence, NARA, HHS, the Commerce Inspector General and the State Department. In Q1, Xacta was flat year over year with only 400 AI licenses. Xacta.ai now appears to be moving from pilots into RFPs and awards, a shift skeptics of the product cycle were not positioned for.
Guidance reinforced the improvement:
- Full-year revenue guidance rose to $198.2-200.7 million, from $187-195 million last quarter and $187-200 million originally.
- Adjusted EBITDA guidance climbed to $32.3-34.1 million, from $23.6-28.6 million in Q2 and $20.6-28 million at the start of the year. That lifts the midpoint roughly 37% above the original outlook.
- Management reiterated a target of about 10 points of cash gross margin lift by the second half of 2027. Roughly 600 basis points would come from exiting low-margin third-party software and 400 basis points from TSA PreCheck.
- Management said revenue growth in 2027 is possible despite that exit.
Bears still have legitimate ammunition:
- The fourth-quarter guide is modest. Revenue of $47.5-50 million implies only 2-7% growth, and EBITDA of $7.0-8.8 million is a sequential step down from Q3.
- Phasing out the ITGEMS third-party software creates a roughly $32 million revenue headwind in 2027, front-loaded at $7.5-8.5 million in each of the first two quarters and about $10 million in Q3.
- The roughly $500 million in large proposals, expected in the second half of 2026 since Q1, remains undecided and keeps slipping.
- CEO John Wood is moving to Executive Chairman for health reasons, with Mark Griffin succeeding him. Management says strategy is unchanged, but the handoff adds execution uncertainty during a pivotal award cycle.
The market setup is more complicated than the surprise figures imply. Investor sentiment deteriorated meaningfully heading into the report, falling from a slightly positive 0.04 to -0.23. That suggests expectations had cooled even as the whisper sat above consensus. The price action reflects a similar round trip:
- The stock opened at $3.79 after the August report, a 52-week low.
- It rallied to $5.95 by late October.
- It entered this report at $4.82, still 27.2% above that post-report open but 19.0% below the inter-earnings high.
- Shares sit about 6.7% above the 200-day moving average of $4.52.
Price, momentum and AVWAP trend readings are positive, while sequential growth is neutral. That profile fits a stock that has rerated off its lows but surrendered a good share of its October enthusiasm.
The bottom line is that Telos missed the whisper on EPS but delivered the most convincing operating quarter of its year. It posted record EBITDA, expanded margins, sustained free cash flow and raised guidance for the third time. The new $58 million Xacta bookings wave is the most significant development because it is recurring, higher-margin and independent of the long-delayed $500 million pipeline. The remaining questions are timing and transition: a soft Q4 guide, a front-loaded 2027 software headwind, pending large awards and a new CEO. Together they will determine whether improving fundamentals can carry the stock back toward its October highs.
Read our earnings preview for Telos Corporation: https://www.earningswhispers.com/article/TLS/22594
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 10 hours | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-11 | |
| Sep-11 | |
| Sep-11 | |
| Sep-08 | |
| Sep-03 |
