AbCellera Heads Into Results With Stock Doubled And ABCL635 Phase 2 Data Taking Center Stage
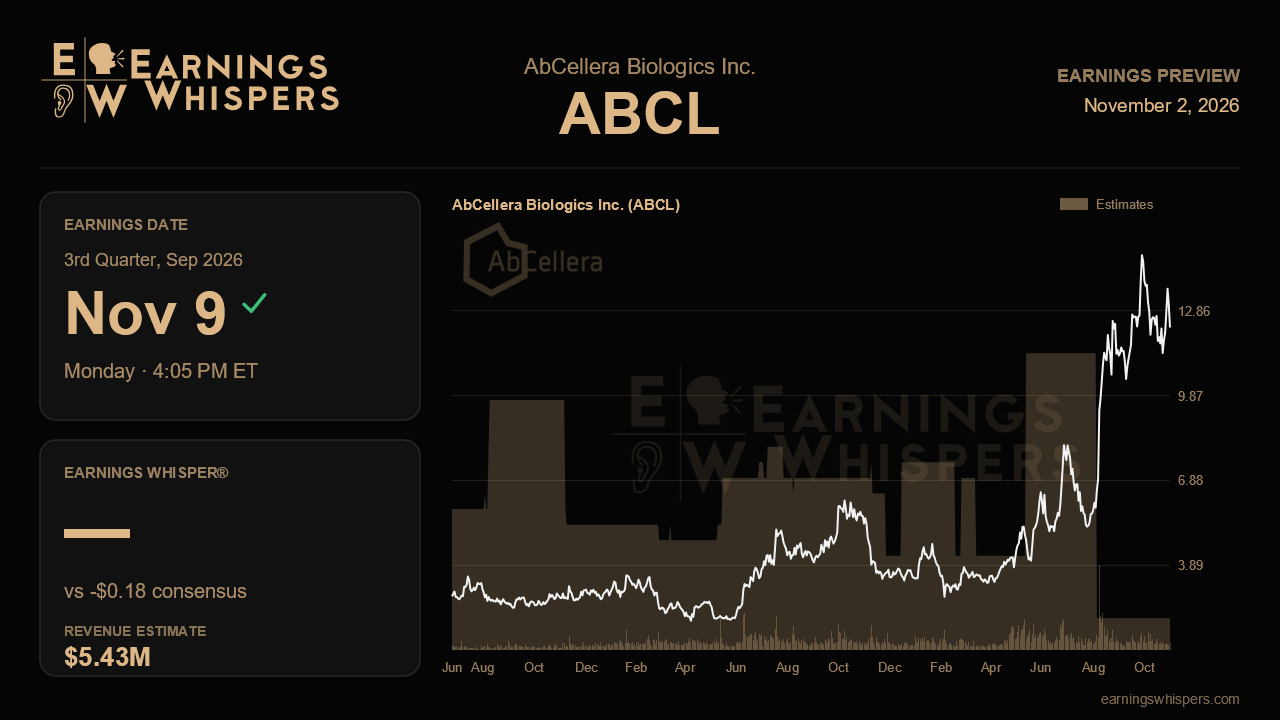
AbCellera's shares have more than doubled since its August report, so the quarterly numbers due after the close on November 9 will be judged less on their size than on whether they support that move. Management had flagged the Phase 2 top-line readout for ABCL635, its hot-flash candidate, as due in the third quarter and called it the company's most important catalyst of 2026. That means this report is where investors should expect management to frame the data, map out next steps and show how the program fits with a T-cell engager business that only recently began attracting large partners.
The Street expects a loss of $0.18 per share, matching the prior quarter and slightly better than the $0.19 loss a year ago. Revenue is forecast at about $5.4 million, roughly 39% below last year's $9.0 million, though modestly above the $4.1 million booked last quarter. None of that should surprise anyone. AbCellera is deliberately moving away from partner-funded research fees toward its own pipeline, so shrinking revenue and steady losses are part of the plan. The company has not issued formal quarterly guidance. Its main financial commitment is a liquidity runway of more than three years, which it reaffirmed last quarter.
The bigger shift at the last call was strategic. After three straight quarters without a new partnership, AbCellera announced two T-cell engager deals. Vertex agreed to pay $28 million upfront for autoimmune programs. Jazz Pharmaceuticals committed $84 million in near-term upfront payments, of which $56 million had already arrived, along with three confirmed programs, more than $2 billion in potential downstream payments and royalties in the mid-single to low-double digits. To support the more confident tone, investors should look for progress on the Jazz option programs, signs that additional partners are interested in the platform, and clarity on how the upfront cash will be recognized as revenue over time. That last item matters because it could make reported revenue lumpier and less tied to the shrinking research-fee base.
Cost discipline is the other test. General and administrative spending fell to about $14 million after litigation costs faded, while R&D climbed to roughly $46 million as internal programs advanced. Flat per-share losses would suggest spending is under control. A noticeably wider loss would raise questions, especially if late-stage costs for ABCL635 begin rising ahead of a larger trial. Liquidity stood above $675 million last quarter, helped by the Jazz cash. Any meaningful drop would weaken the runway argument that keeps dilution worries in check.
Sentiment has warmed. Bullish readings rose to 31.6% from 22.8% ahead of the prior report, though that remains a measured level of optimism given how much the stock has run. Shares sit at $12.27, far above the 200-day moving average of $6.84. They have traded between $5.62 and $15.02 since the last report, a much wider and higher range than the prior quarter's $3.94 to $8.44. The stock is now about 18% below that recent peak, which suggests some profit-taking and a market that has priced in a good deal of success but is not euphoric.
Ultimately, the quarterly loss and revenue figures are close to irrelevant on their own. The central question is whether ABCL635 has cleared the remaining scientific hurdles management identified, namely whether targeting brain regions beyond the core hot-flash circuitry matters and how large the placebo effect turns out to be. If management can pair a credible ABCL635 story with continued T-cell engager deal momentum and a stable cash position, the narrative of a platform company becoming a pipeline company stays intact. If the clinical picture looks murky, the doubled share price leaves little room for error.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-08 | |
| Oct-08 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 | |
| Sep-02 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 |
