AbCellera Tops Estimates, But ABCL635's Breakout Phase 2 Data And A $900 Million War Chest Are The Real Story
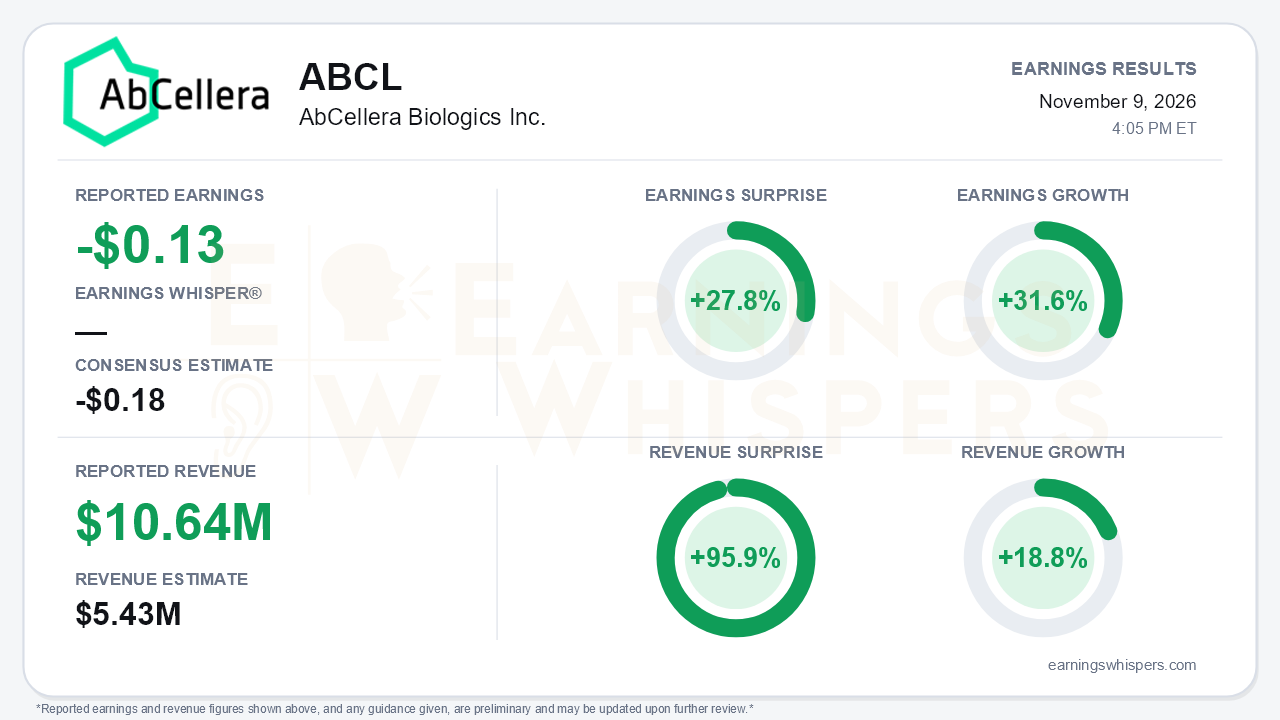
AbCellera Biologics (NASDAQ: ABCL) beat third-quarter expectations, but the income statement is not why this quarter matters. The company lost $0.13 per share, ahead of the -$0.18 consensus by 27.8%. That loss improved 31.6% from a year earlier. Revenue of $10.64 million nearly doubled the $5.43 million estimate, a 95.9% surprise, and grew 18.8% year over year. Net loss narrowed to $40.8 million from $57.1 million. The quarter's defining event was clinical. ABCL635's Phase 2 data in menopausal vasomotor symptoms cleared the bar management had set by a wide margin, and a $200 million equity raise pushed available liquidity to roughly $890 million. AbCellera now looks less like a discovery-platform company with a pipeline attached and more like an emerging late-stage developer. That shift is both the opportunity and the new burden.
The quality of the financial beat deserves scrutiny. Expense discipline drove the improvement more than the business did. SG&A fell to $13.6 million from $25.0 million, and R&D dropped to $43.5 million from $55.0 million. Higher interest income also helped. Pre-tax loss improved even more than net loss, because the income tax recovery shrank to $2.1 million from $11.6 million.
The nine-month picture is less flattering. Year-to-date revenue fell to $23.0 million from $30.3 million as licensing and royalty revenue all but disappeared. The year-to-date net loss of $139.4 million is slightly wider than last year's.
The positive $19.3 million in nine-month operating cash flow also needs context. It was driven largely by a $66 million build in deferred revenue tied to partner upfronts, along with collections of receivables and tax refunds. It does not reflect a self-funding operation.
The partnership business is also a mixed signal. Research fees rose to $10.5 million from $8.8 million, yet the call characterized research-fee revenue as structurally declining. Partner-led programs with an AbCellera downstream stake fell to 34 from 44 at year-end.
The call explains why investors largely look past those details. On the first- and second-quarter calls, management framed success for ABCL635 as rough parity with the NK3R small molecules, about a 20% placebo-adjusted reduction in hot-flash frequency. The data delivered:
- a 50% placebo-adjusted frequency reduction at four weeks;
- a 46% placebo-adjusted severity reduction;
- complete resolution in 37% of patients versus 2.2% on placebo;
- no GI or liver signal.
Those figures come from cross-study comparisons, not head-to-head trials. Management's tone moved from cautioning that scientific risk remained to calling this a transformative quarter.
The forward agenda is substantial. AbCellera plans late-stage development in menopausal VMS in 2027, plus trials in VMS caused by breast and prostate cancer treatment. ABCL992, a half-life-extended follow-on to ABCL635, entered IND-enabling work alongside two new programs: ABCL385 in oncology and ABCL646 against an ion channel target. That is three additions against a 2026 goal of at least one. ABCL386 and ABCL688 remain on track for the clinic in 2027.
Bears have legitimate ammunition:
- Headache and fatigue rates were higher on ABCL635.
- Repeat-dose immunogenicity remains unproven.
- The 12-week washout and open-label extension data slipped from late 2026 to early 2027.
- Pivotal dose, comparator, and sample size are not finalized, and manufacturing must scale.
- ABCL575 met its Phase 1 endpoints but will not advance, after external failures in the OX40L class. Management had previously described it as Phase 2-ready and a partnering candidate.
- Committed government funding continues to draw down, now at more than $100 million.
The market setup is more complicated than the surprise implies. Shares closed at $11.88 on November 6, ahead of the report. That is up 105.2% from the $5.79 open after the August report and 69.1% above the 200-day moving average. Most of the clinical good news is therefore already in the price.
The stock peaked at a 52-week high of $15.02 on September 30, around the financing, and has since given back 20.9%. Investor sentiment moved the opposite way from price. It slid from 0.23 to -0.08, a meaningful shift from mildly positive to slightly negative. That cooling may reflect dilution, with shares outstanding up to 326 million from 301 million at year-end, and the long runway before pivotal data. Momentum and AVWAP trend readings remain positive, while the price trend has flattened to neutral, consistent with a stock consolidating a large move.
The bottom line is that AbCellera delivered a clean beat on a narrower loss, but the earnings figures are secondary to a de-risked lead asset and a balance sheet built to carry it into late-stage trials. The investment debate has shifted from whether the platform can produce a meaningful drug to whether ABCL635 can hold its efficacy and tolerability profile over longer dosing and a pivotal program. Investors already paid up for the answer they hope to get. The early-2027 data and final trial design now carry more weight than any quarterly revenue line.
Read our earnings preview for AbCellera Biologics Inc.: https://www.earningswhispers.com/article/ABCL/22603
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-08 | |
| Oct-08 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 | |
| Sep-02 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 |
