AAON Must Show Margins Can Catch Up To Its Data Center Sales Boom
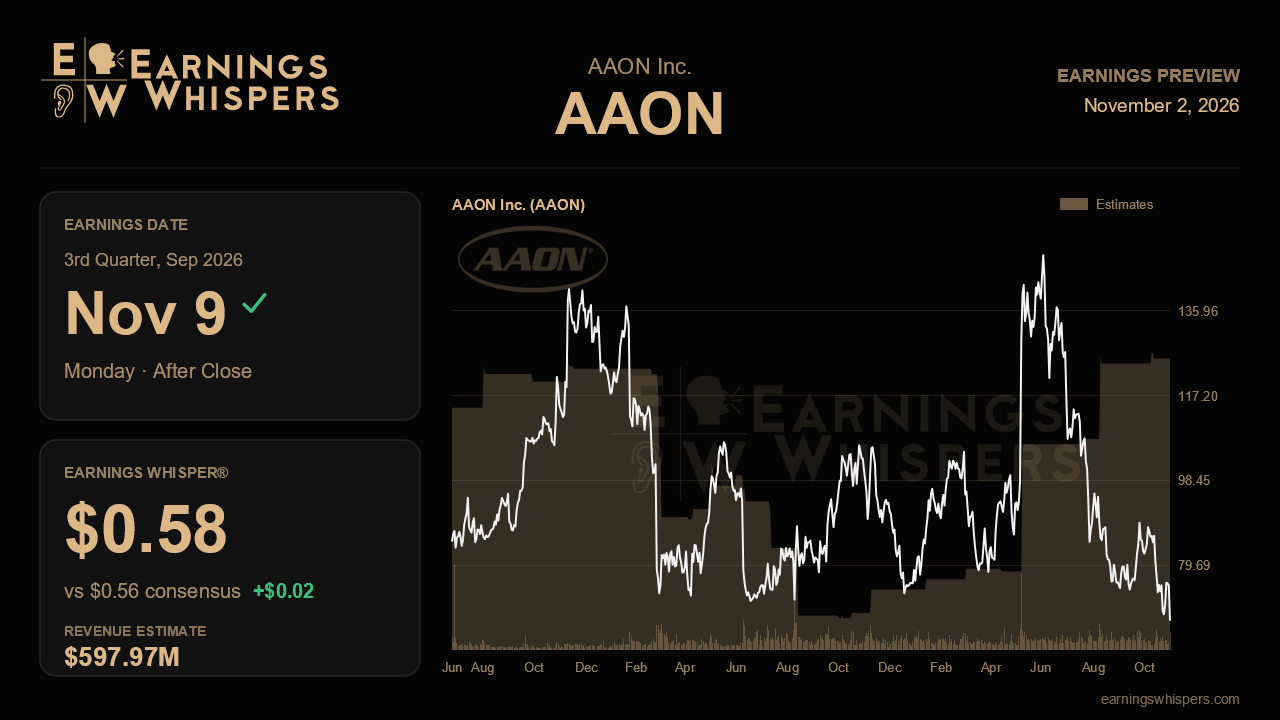
AAON enters its third-quarter report with a sales story that keeps getting bigger and a margin story that keeps getting pushed back. Management has raised its 2026 sales growth outlook twice, to 55% to 60%, while trimming its gross margin forecast on each of the last two calls, from 29% to 31% at the start of the year to just 25% to 26% now. Shareholders have clearly decided which half of that message matters more: the stock has fallen about 28% since the last report, while the S&P 500 slipped only about 2%.
The Street is looking for earnings of $0.56 a share on revenue of $598.0 million when results arrive after the close on November 9. That would be roughly 51% earnings growth and 56% revenue growth from a year ago, which is still exceptional expansion. Sequentially, though, it marks a step down from the record $627 million and $0.69 posted in the second quarter, consistent with management's signal that second-half revenue from Basics, the data center business, would run roughly flat with the second quarter. The earnings whisper of $0.58 sits only slightly above consensus, suggesting a modestly higher bar rather than an aggressive one. Full-year revenue guidance of $2.24 billion to $2.31 billion sits well above the $2.07 billion consensus figure, which looks anchored to the company's earlier outlook, so a quarter near or above $598 million would help confirm that the raised range is real.
Gross margin is the number that matters most. AAON reported 24.3% in the second quarter, down from 25.1% in the first and 26.6% a year earlier. Reaching a full-year 25% to 26% requires the second half to run noticeably better than the first, and management placed most of that improvement in the fourth quarter as higher-margin backlog converts. That makes the third quarter a bridge. A figure that holds steady or edges up would support the plan; another decline would raise doubts about whether the fourth-quarter inflection can do so much work on its own. Watch the Aon Oklahoma segment, where margin fell 460 basis points year over year, and the ACP segment, where pricing trailed inflation and recovery was pushed to year-end.
The Memphis plant is the operational centerpiece. After weighing on results as an underabsorbed cost center, it was described last quarter as running ahead of plan with margins improving for two straight quarters. Continued progress there would validate the idea that rapid data center growth can eventually lift profitability rather than dilute it. Supply of fans and other components, flagged as a possible source of noise, is the main thing that could disrupt that ramp.
Demand signals deserve equal scrutiny. Basics bookings fell from elevated levels and backlog declined sequentially after about four quarters of roughly 3x book-to-bill, which management attributed to the lumpy timing of large projects. A rebound in bookings, or concrete progress on the 2027 and 2028 pipeline and new customer diversification, would ease fears that the data center surge is peaking. On the traditional side, Aon-branded bookings rose 16% and AlphaClass heat pump orders jumped 50% last quarter; sustaining that recovery would show the core commercial HVAC business can carry weight if data center orders pause.
Sentiment has barely moved, at a mildly bullish reading of 5.7% versus 6.0% a quarter ago, but the price action tells a harsher tale. At $67.40 the stock sits near the bottom of its post-earnings range of $65.55 to $97.47 and far below its 200-day moving average of $97.70, after trading as high as $150.46 the prior quarter. That pessimism lowers the bar in one sense, yet it also means another margin guidance cut could be punished. The report ultimately hinges on whether AAON can show that its record volumes are finally translating into margin recovery, rather than another quarter of growth bought at the expense of profitability.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-30 | |
| Aug-21 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 | |
| Jul-30 | |
| Jul-23 | |
| Jul-02 | |
| May-27 | |
| May-18 | |
| May-13 | |
| May-07 | |
| May-07 | |
| May-07 |
