AAON Crushes Estimates And Raises Guidance A Third Time, But A Restatement And Material Weakness Muddy The Margin Recovery
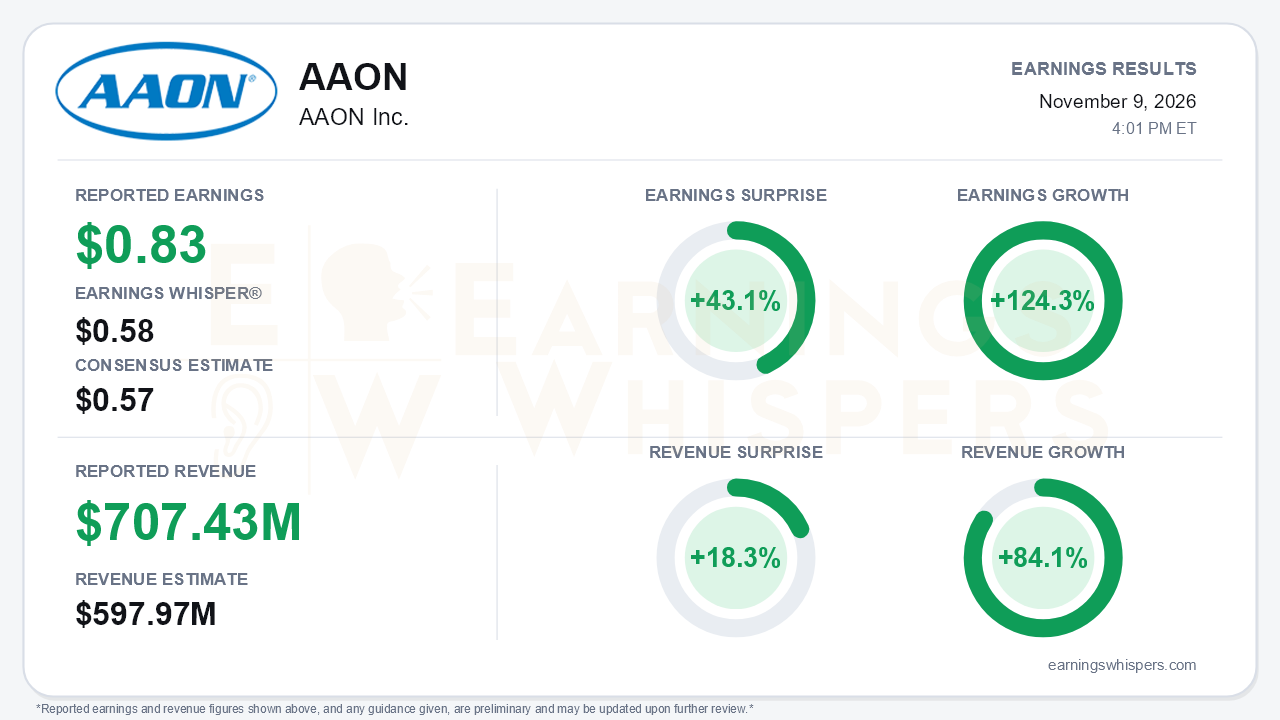
AAON delivered a beat that is difficult to argue with on the numbers. The company earned $0.83 per share for the September quarter, well above the $0.57 consensus and the $0.58 Earnings Whisper number, a 43.1% surprise. Revenue reached a record $707.43 million, up 84.1% year over year and 18.3% above the $597.97 million consensus. Earnings grew 124.3%. Management also raised full-year sales growth guidance to 72%-75% from 55%-60%. That is the third straight raise from an original 18%-20% outlook. The central tension is that the quarter arrived alongside a self-identified material weakness and a restatement of the first half. That restatement complicates how investors should read the sequential margin recovery.
The quality of the beat holds up better than the governance headline suggests. EPS was identical on a GAAP and adjusted basis. Gross profit rose 76.4% to $188.5 million, and SG&A fell 400 basis points to 12.5% of sales. Operating income more than doubled to $100.0 million, and adjusted EBITDA margin reached 18.0% versus 16.5% a year ago. Cash conversion improved as well. Year-to-date operating cash flow was $146.9 million against a $18.8 million outflow a year earlier, the call described the period as the first free-cash-flow-positive quarter in two years, and leverage fell to about 1.0x. Gross margin of 26.7% was still 110 basis points below last year because of a 300-plus basis-point mix headwind as BASX volume ran through less mature plants.
The restatement is where scrutiny belongs. The errors involved revenue recognition and software subscriptions. They lowered first-quarter net sales by $4.4 million and raised second-quarter net sales by $15.2 million, for a net $10.7 million and $0.09 EPS increase to the first half. Management reported no evidence of fraud. The adjustments still change the margin narrative.
- **Consolidated gross margin:** The call framed Q3 against a 24.3% second-quarter figure, which was the originally reported number. The release's restated comparison shows only a 60 basis-point sequential gain.
- **Coil Products margin:** The segment's jump to 25.8% looks dramatic against the originally reported 16.0%. Against the restated 19.1%, it is more modest.
The improvement is real, but it is smaller than the call's framing implies.
Underneath, demand trends turned more constructive. BASX sales more than tripled to $397.2 million on data center demand. BASX orders rebounded roughly 116% sequentially after soft second-quarter bookings, and management expects fourth-quarter bookings at or above the year-ago record. The AAON brand grew 19.6% despite a soft commercial HVAC market, with national account orders up about 70%. AAON Oklahoma's adjusted gross margin, which excludes Memphis overhead, improved 160 basis points sequentially to 32.8%.
Bears have legitimate ammunition on the forward picture:
- **Backlog:** Total backlog fell 5.9% sequentially to $1.85 billion. Management attributes the decline to faster conversion and the lumpy timing of large BASX awards.
- **Fourth-quarter outlook:** The full-year growth guide implies fourth-quarter revenue roughly in the $640-$680 million range by our math, below Q3. The call also flagged a sequential gross-margin dip on fewer production days.
- **Margin targets:** The roughly 26% full-year gross-margin guide sits well below the original 29%-31% target. The mid-to-high-30s Oklahoma margin goal has been pushed out as a 2027 story.
- **Political risk:** Post-election political pressure on data centers emerged as a new concern, although management said less than a third of backlog sits in affected states.
The positive catalysts are a capex step-down in 2027, a $70 million buyback authorization, and a planned resegmentation into AAON and BASX brand segments with recast historicals.
The market setup was not demanding. Investor sentiment heading into the report was essentially neutral at about 0.06. The whisper number sat only a penny above consensus, so few investors were positioned for a beat of this size. Shares opened at $94.00 after the August report, a touch below the current 200-day moving average of $96.78. Management also referenced a share pullback in discussing its buyback. Earnings Whispers trend readings are mixed: momentum is positive, but price and AVWAP trends remain negative. That suggests the stock has not been rewarded for the improving fundamentals in recent months.
The bottom line is that AAON's operating story strengthened materially this quarter. Revenue, cash flow and guidance all moved decisively higher, and BASX demand recovered after a soft patch. The beat was large enough that the restatement does not undermine it. However, the restatement softens the apparent sequential margin rebound, and a material weakness in revenue recognition is a governance blemish investors will want remediated. With Q4 implied lower and margins still short of early-year ambitions, the story now rests on execution and credibility rather than demand.
Read our earnings preview for AAON Inc.: https://www.earningswhispers.com/article/AAON/22602
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-02 | |
| Oct-30 | |
| Aug-21 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 |
