Casella's Landfill Surge Meets Margin Test As Mid-Atlantic Synergies Come Due
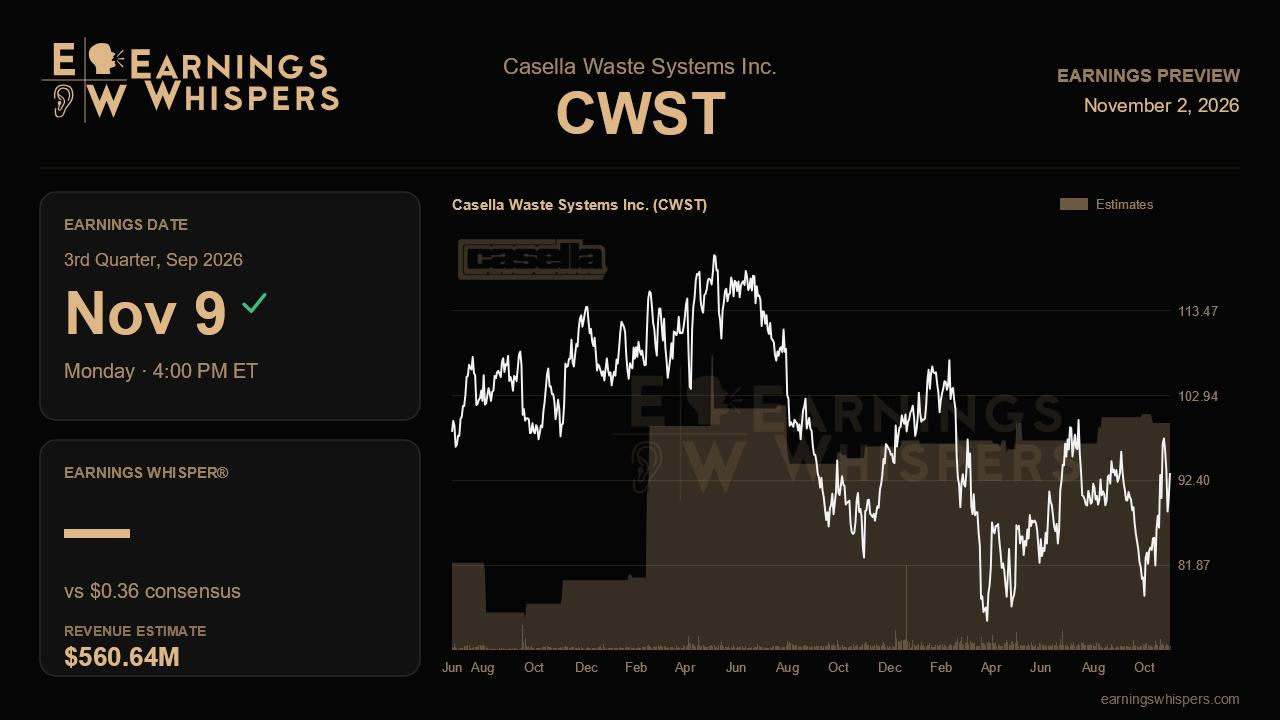
Casella Waste Systems heads into its third-quarter report with an unusual split. The top line is growing at its fastest clip in years, yet Wall Street expects per-share earnings to shrink. That gap is the story of this report. Management has spent two quarters arguing that the margin softness is mostly cosmetic, caused by fuel surcharges that inflate revenue and by a tough recycling comparison. The second half of the year is when that argument is supposed to show up in the numbers.
Analysts are looking for earnings of $0.36 a share on revenue of $560.6 million. That would be roughly 15.5% revenue growth from the year-ago $485.4 million, alongside a 14.3% decline in EPS from $0.42. Acquisitions, price and volume should drive the revenue gain. Higher amortization from deal activity and a heavier tax provision explain much of the earnings drag; those same factors led management to cut its full-year GAAP net income outlook to between zero and $6 million. Casella has raised full-year revenue guidance twice. The range started at $1.97 billion to $1.99 billion and now stands at $2.09 billion to $2.11 billion. Consensus for the year sits at about $2.08 billion, below the low end of that range. Either the Street is discounting the fuel pass-through that helped lift guidance, or it is lagging management. Either way, a third raise is not fully priced in.
The operational evidence that matters most starts at the landfill. Volumes jumped 8.4% in the second quarter after rising just 2.3% in the first. Construction and demolition tons climbed about 17%. Management tied that strength to tightening disposal capacity in the Northeast, citing the Hudson Falls incinerator closing at the end of 2026 and the Albany landfill closure. If that view is right, volumes should stay strong and third-party landfill pricing should hold near 4%, rather than continuing the slight dip it showed last quarter. A clear update on the Hakes landfill expansion permit, which management expected this quarter and which would add about 20 years of airspace, would support the long-term case. Early results from the new McKean rail transfer station, which began moving company waste from Massachusetts in July, would add to it.
Margins are where the narrative faces its real test. Adjusted EBITDA margin fell 80 basis points to 22.7% in the second quarter. Management said fuel gross-up and Resource Solutions accounted for more than all of it, and that the core business still expanded. EBITDA guidance of $473 million to $483 million was held rather than raised. That puts weight on the second half. Two programs should begin paying off: the $5 million in Mid-Atlantic synergies, now that systems integration is complete and route cuts are underway, and the $15 million G&A savings effort. Margin stabilization, or a narrower year-over-year decline, would validate the optical-headwind explanation. Another sizable drop, or slow progress at the lagging Star and Mountain State integrations, would undercut it.
The market has leaned toward the optimistic reading. Shares have gained 4.3% since the last report while the S&P 500 slipped 2%. Sentiment has also flipped from mildly bearish to mildly bullish. At $93.33, the stock sits above its 200-day moving average of $90.15. That is in the upper half of its post-earnings range, though still about 5% below the $98.03 high, so it is not yet pressing for a breakout.
The verdict likely comes down to whether EBITDA starts catching up with revenue. Another guidance lift built mostly on fuel and acquisitions would carry less weight than proof that synergies and firm pricing are turning volume gains into wider underlying margins. Casella has earned credibility on growth. This quarter it needs to show that the growth is profitable.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-20 | |
| Oct-13 | |
| Oct-05 | |
| Oct-01 | |
| Sep-29 | |
| Sep-23 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Aug-17 | |
| Aug-11 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 |
