Casella Waste Narrowly Misses As Margin Slippage And A Write-Off Overshadow A Bolder 2027-2029 Margin Plan
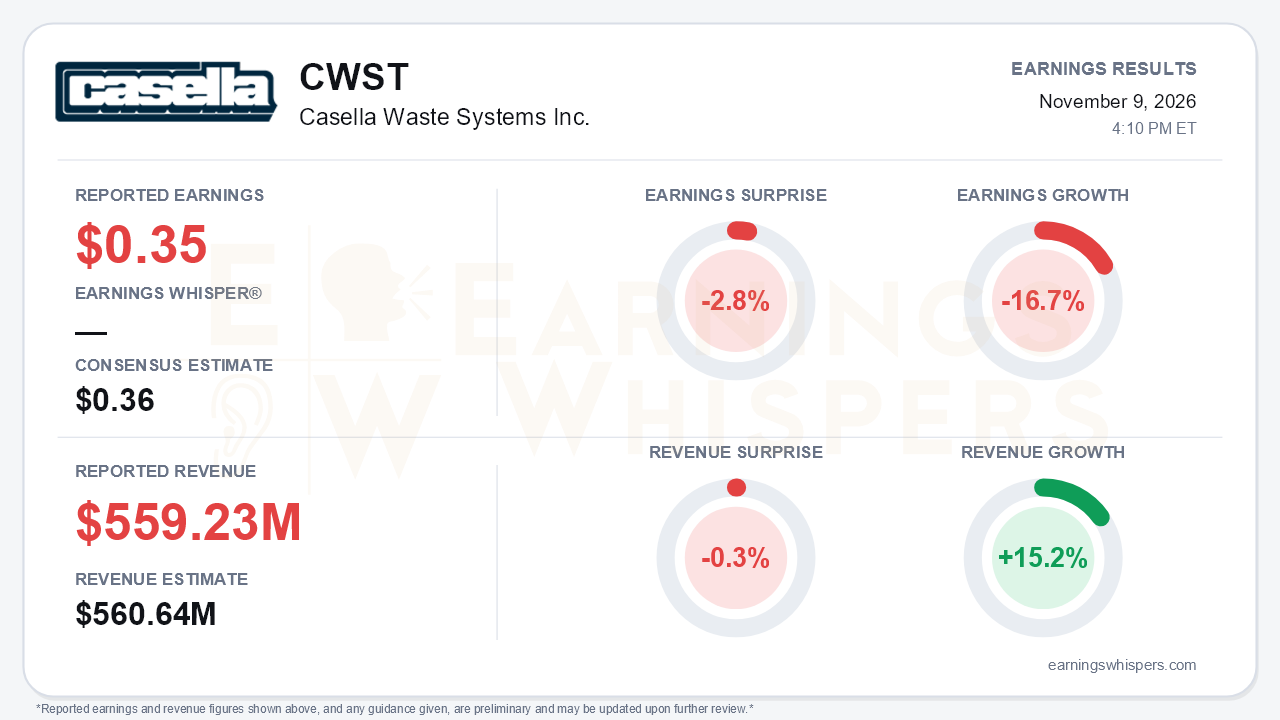
Casella Waste Systems (NASDAQ: CWST) delivered a quarter in which revenue grew strongly but profitability did not keep pace. Adjusted EPS of $0.35 missed the $0.36 consensus by 2.8% and fell 16.7% from a year earlier. Revenue of $559.23 million rose 15.2% but came in 0.3% below the $560.64 million consensus. The misses were small. The direction of earnings matters more. Acquisitions and pricing keep expanding the top line, yet margins compressed for a second straight quarter. Management answered that with an ambitious long-term margin promise rather than a better 2026 number. That is the central tension: a credible multi-year margin story set against near-term execution that keeps slipping.
The quality of the quarter deserves scrutiny.
- **GAAP results:** Casella swung to a net loss of $7.0 million, or $(0.11) per share, from a $10.0 million profit. The main cause was a $13.6 million write-off after abandoning the Granite State landfill development in New Hampshire, plus severance and acquisition costs.
- **Adjusted EBITDA:** It rose 11.4% to $133.5 million, but margin fell 80 basis points to 23.9%. That followed an 80bp decline in Q2. Management attributed the drag to fuel, the Mid-Atlantic region, Resource Solutions and acquisitions, each costing roughly 40-50bp.
- **A flattering accrual:** The margin decline came despite roughly 120bp of help from reversing incentive-compensation accruals. Excluding that one-time benefit, underlying margin erosion was considerably worse. The reset also becomes a 2027 headwind.
- **Cash flow:** Third-quarter adjusted free cash flow fell to $33.0 million from $48.6 million. Nine-month adjusted free cash flow is now down 7%, after running up 10.3% at the half.
- **Balance sheet:** Debt climbed to $1.36 billion from $1.13 billion to fund roughly $440 million of acquisitions. Cash fell to $11.7 million, and interest expense rose about 30%.
The operating picture underneath is mixed rather than weak.
- **Pricing:** Pricing remains the strongest pillar. Solid waste price rose 5.5%, collection price 5.9%, and third-party landfill price 4.6%, up from 4.0% in Q2 and 2.5% in Q4 2025.
- **Volume:** Same-store revenue growth was 6.7%, but collection volume fell 2.1%.
- **A conflicting landfill figure:** The release cites 12.8% landfill volume growth. That figure measures the volume-driven revenue contribution. The call put actual landfill tonnage growth at 5.3%, slowing from 8.4% in Q2. Investors should note the deceleration rather than the headline figure.
- **Mid-Atlantic:** Management candidly admitted the region "fumbled" over the summer and replaced its leadership. It now points to an inflection, with October regional margins up roughly 300bp year over year and 150bp from August.
Guidance reinforced the mixed message.
- **Revenue:** The 2026 revenue range was raised again, to $2.10-$2.11 billion, but mostly because of higher floating fuel fees rather than core demand.
- **Adjusted EBITDA:** The range was only narrowed, to $475-$481 million, with the midpoint unchanged despite continued acquisition activity.
- **GAAP earnings:** Net income guidance moved to a loss of $4-$10 million, from a profit of $0-$6 million.
- **Free cash flow:** The $200-$210 million target was reaffirmed. That implies an unusually heavy fourth quarter after nine months produced $111 million.
The forward catalysts are real but back-weighted.
- **The "303" plan:** It commits to at least 300bp of adjusted EBITDA margin expansion, reaching at least 26% by 2029.
- **Self-help already in place:** About $5 million a year from credit card convenience fees, about $5 million from September G&A cuts, and a revised fuel surcharge that now recovers margin.
- **Preliminary 2027 outlook:** About 5% organic growth, roughly 7% total revenue growth, 50-100bp of margin expansion and about 10% EBITDA growth before new deals.
- **Other positives:** A permit for the Hakes landfill expansion was received, adding about 20 years of capacity. A portfolio review will require business units to reach a 15% operating income margin or face sale or closure.
Bears have legitimate ammunition, however. The North Country landfill now closes at the end of 2026, earlier than the previous end-of-2027 framing, raising transport costs in New Hampshire. The Ontario landfill wind-down is another EBITDA drag. Management itself said most of the plan's margin benefit lands in 2028-2029, not 2027.
The market setup is more constructive than the fundamentals alone would suggest. Shares have risen 10.6% since opening at $89.50 after the August report, to $99.02, and sit about 10% above the 200-day moving average of $89.95. Earnings Whispers price and AVWAP trend readings are positive. Investor sentiment improved from slightly negative (-0.066) to modestly positive (+0.099). That is a meaningful but not dramatic shift, suggesting investors were leaning toward the margin-recovery narrative into the print. With the stock trading well above its longer-term average, the market appears to be pricing in the Mid-Atlantic turnaround and the 2027 outlook before either has been demonstrated in reported margins.
The bottom line is that Casella's top-line machine remains intact, with firm pricing, steady acquisitions and a raised revenue outlook. Earnings quality, however, has deteriorated. Margins are falling despite a one-time accrual benefit, free cash flow has turned negative year to date, leverage is climbing, and GAAP results now show a loss for the year. The 303 plan and October's Mid-Atlantic improvement give investors a credible path forward, but much of the payoff sits two to three years out. Q4 margins, the implied free-cash-flow catch-up and early 2027 execution will determine whether the recent rally was early or right.
Read our earnings preview for Casella Waste Systems Inc.: https://www.earningswhispers.com/article/CWST/22619
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-20 | |
| Oct-13 | |
| Oct-05 | |
| Oct-01 | |
| Sep-29 | |
| Sep-23 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Aug-17 |
