Onsemi Matches The Whisper But Raises The Bar: AI Data Center Growth And Margin Gains Contrast With An Automotive Pullback
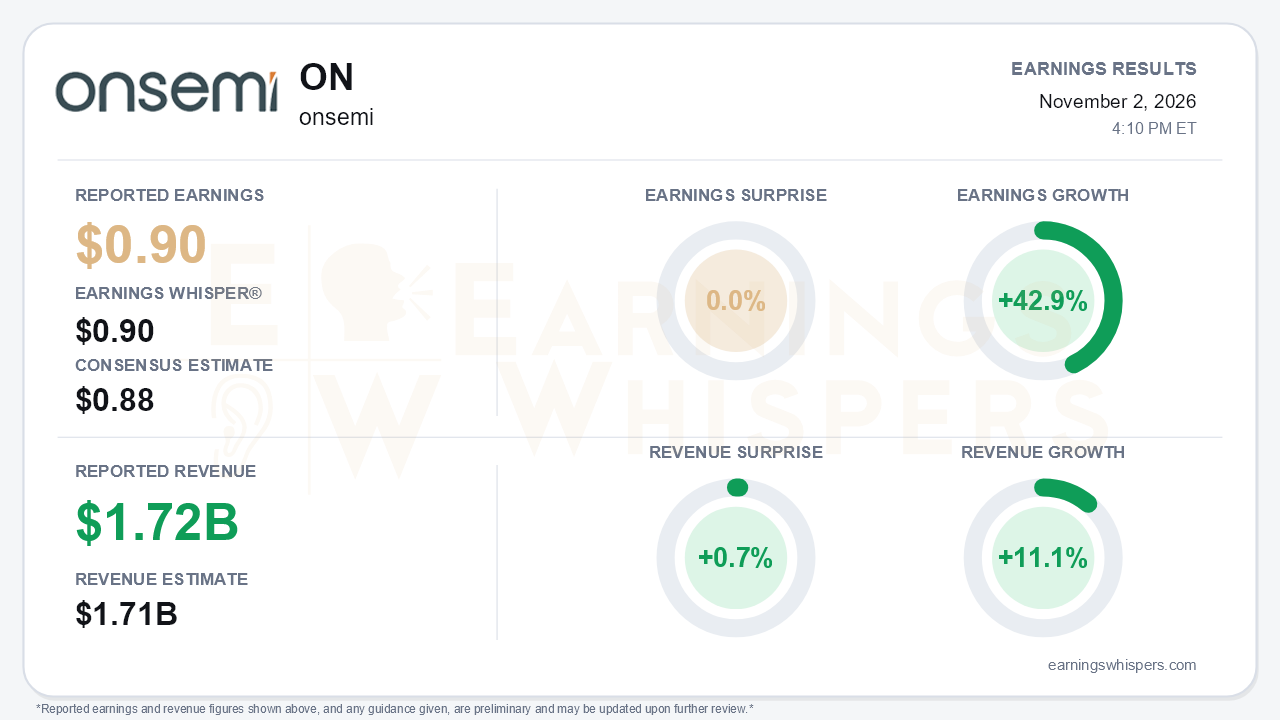
onsemi's third-quarter headline was merely in line. The underlying business, however, moved in the right direction on almost every measure except automotive. Non-GAAP EPS of $0.90 topped the $0.88 consensus but only matched the $0.90 Earnings Whisper number. Revenue of $1.722 billion edged past the $1.71 billion consensus by 0.7%. The more important story is the trajectory. Earnings grew 42.9% year over year on 11.1% revenue growth. Quarterly non-GAAP EPS has now run $0.64, $0.64, $0.74 and $0.90, and fourth-quarter guidance of $0.95 to $1.07 came in above estimates. This was not a blowout print. It was a quarter that pushed the earnings power of the model meaningfully higher.
The quality of the quarter holds up well. Non-GAAP gross margin expanded for a fifth straight quarter to 41.2%, up 190 basis points sequentially and well above the 38.0% of a year ago. Non-GAAP operating margin reached 23.2%, up from 20.8% in Q2.
GAAP results support the adjusted figures. GAAP EPS rose to $0.79 from $0.56 in Q2 and $0.63 a year earlier. Special items shrank to $21.5 million at the operating line, compared with $75.5 million in Q2. GAAP gross margin of 41.4% actually exceeded the non-GAAP figure, helped by a small restructuring-related reversal.
Two caveats temper the per-share gains:
- A lower share count helped: non-GAAP diluted shares fell to 392 million from 408 million a year ago.
- Free cash flow of $489 million, or 28% of revenue, was flattered by unusually light capex of just $27.8 million. Management expects capex intensity to return to roughly 5% of revenue in 2027.
The segment mix explains why investors are paying attention. PSG grew 21% year over year, while AMG and ISG each grew only 2%. AI data center revenue was $180 million, up 39% sequentially and 175% year over year. The full-year AI data center outlook has climbed on every call this year:
- Q1: expected to double.
- Q2: expected to more than double.
- Q3: roughly $620 million, up about 140%.
Management still expects that business to double again in 2027 off the higher base. Industrial was the other upside surprise. It was guided flat for Q3 but grew 10% sequentially to $467 million, and Q4 is guided up low double digits on grid and energy demand. Management also outlined a path to its 53% gross margin target built on utilization, its fab-right initiatives, mix and pricing. The Q4 margin guide of 41.5% to 43.5% implies another step up of roughly 130 basis points at the midpoint.
Automotive is where bears have legitimate ammunition. Auto revenue has slipped from $798 million to $777 million over four quarters. Q3 auto fell 1% sequentially, against a Q2 expectation for low-single-digit growth, and Q4 is guided down high single digits. Management attributes the decline to deliberately shifting constrained supply toward AI data center and industrial customers, deferring auto replenishment orders. It expects a catch-up in Q1 2027. That explanation is plausible, but it also exposes a related constraint: utilization held flat at 83% because specific technology lines are tight. Input-cost inflation is still being offset with price increases. Management also flagged lumpiness in the Q4 'other' category tied to a single customer ramp.
The capital-allocation picture changed materially. The $600 million Ferric acquisition, plus up to $175 million in earnouts, raised the 2030 AI data center target by $500 million to more than $3 billion. The Synaptics deal was restructured to roughly $5.7 billion in cash rather than $7 billion in stock, which management says should make it immediately accretive to non-GAAP EPS. That accretion comes at the cost of leverage. Buybacks collapsed to $20 million from $332 million in Q2 as the company prioritizes deleveraging. Shareholders are trading repurchase support for an accelerated AI power-delivery strategy.
The market had not been rewarding the improving fundamentals heading into the report. As of the October 30 snapshot, shares at $71.67 were:
- down 15.1% since the open following the August report;
- 12.9% below the 200-day moving average;
- 17.5% below the October 6 inter-earnings high of $86.92;
- 8.9% above the September low of $65.80.
Investor sentiment improved from -0.23 to -0.12 but remains negative. That is a skeptical setup rather than a crowded one. The trend readings are mixed, with momentum positive while price and AVWAP trends remain negative.
The bottom line is that onsemi delivered an in-line quarter carrying better-than-in-line implications. The AI data center outlook rose again, margins keep stepping higher, industrial has turned, and guidance points to further EPS expansion. Against that, the automotive pullback, supply constraints, rising acquisition leverage and the loss of buyback support give skeptics real issues to debate. With the stock well off its highs and sentiment still below zero, the bar was not elevated. The burden now shifts to whether Q4 delivers the margin step and whether auto recovers on schedule in early 2027.
Read our earnings preview for onsemi: https://www.earningswhispers.com/article/ON/21417
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 |
