JBS Earnings Preview: Can The US Beef Turnaround Outrun Leverage Above Target?
JBS heads into its third-quarter report with an improving operating story and a stock price that hasn't kept up. Last quarter, management argued that its most troubled business, US beef, had finally turned the corner. The same report also showed net leverage drifting above the company's own comfort zone and a headline loss driven by one-time financial charges. The November 9 release, due after the close, is the first real chance to see whether the beef recovery is durable enough to start repairing the balance sheet.
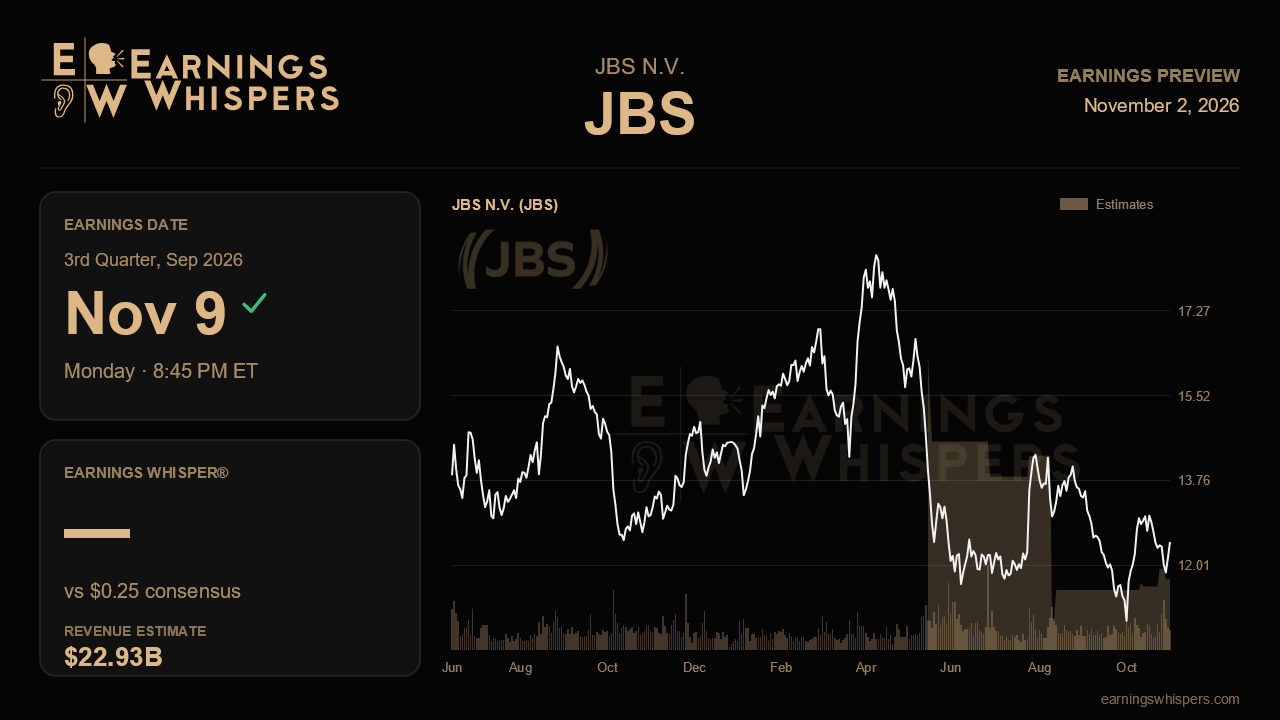
The Street is looking for earnings of $0.25 per share on revenue of about $22.93 billion. That top-line figure sits roughly 4% below the record of nearly $24 billion posted last quarter, so analysts are not counting on more sales momentum. The earnings bar is more interesting. Last quarter's reported loss of $0.09 per share was distorted by roughly $319 million of non-recurring financial expenses and settlements, while adjusted net income came in at $218 million. A return to clean, positive earnings would show that the swing to a loss was noise rather than a deterioration in the business. Without formal guidance to measure against, the consensus effectively assumes a quiet quarter below the line.
US beef remains the swing factor. Its EBITDA margin improved to negative 1.3% from negative 3.9% a year earlier, helped by folding Swift and Packerland into a single business unit and by a push into value-added ground beef. Management's tone shifted from bracing for a worse year to talking about approaching breakeven. The new catalyst is the reopening of the Mexican border to cattle. The first port was scheduled to open in late August, and three ports could eventually restore about 5% of US slaughter, though management did not expect flows to normalize until the second quarter of 2027. This report should therefore show early, partial benefit at best. Another step toward breakeven would validate the narrative. A stall or relapse in beef margins would suggest the integration gains were a one-quarter event.
The other proteins carry their own questions. US pork earned a strong 8.9% margin last quarter, but management called pork demand the softest of the three proteins, with weakness in prepared foods. In US chicken, industry supply grew 4.5%, faster than expected, which pressured big-bird commodity spreads. The roll-off of last year's exceptional chicken profits also helped push leverage higher. In Brazil beef, production for China was set to resume in October, though most of the commercial impact of the quota disruption falls in 2027, and EU restrictions add pressure. If chicken and pork give back more than beef recovers, the consolidated improvement story weakens.
The balance sheet ties it together. Net leverage rose to 3.1 times, above the 2 to 3 times target, after a $1 billion June dividend. Management cut 2026 capital spending by $400 million to $2.0 billion and raised its interest expense estimate to $1.3 billion. It now puts cash-flow-breakeven EBITDA at $5.1 billion. Continued positive free cash flow, after last quarter's $130 million, and any stabilization in leverage would go a long way. Updates on the Danantara joint venture are also relevant, since the $2.5 billion equity injection for a 25% stake in Australia and New Zealand offers a path to deleveraging alongside expansion in Southeast Asia.
The market has been skeptical. Shares have fallen 5.6% since the last report, trailing the S&P 500 by about 3 percentage points. At $12.49, the stock sits below its 200-day moving average of $14.11, near the middle of its post-earnings range of $10.61 to $14.32. Sentiment has warmed slightly, with the bullish reading rising to 42% from 38.5%, but that is a cautious improvement rather than enthusiasm. The central question is whether US beef keeps moving toward breakeven quickly enough to offset softer chicken and pork and bring leverage back inside the target. If it does, the improving narrative holds. If it doesn't, the debt story will overshadow the turnaround.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-23 | |
| Sep-01 | |
| Aug-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 |
JBS, Tyson Stocks Jump on U.S. Plans to Resume Mexican Cattle Imports
JBS +10.34%
The Wall Street Journal
|
| Jun-15 | |
| Jun-12 |
