JBS Misses Badly As A U.S. Beef Recovery Is Overwhelmed By Pork, Chicken And Balance-Sheet Strain
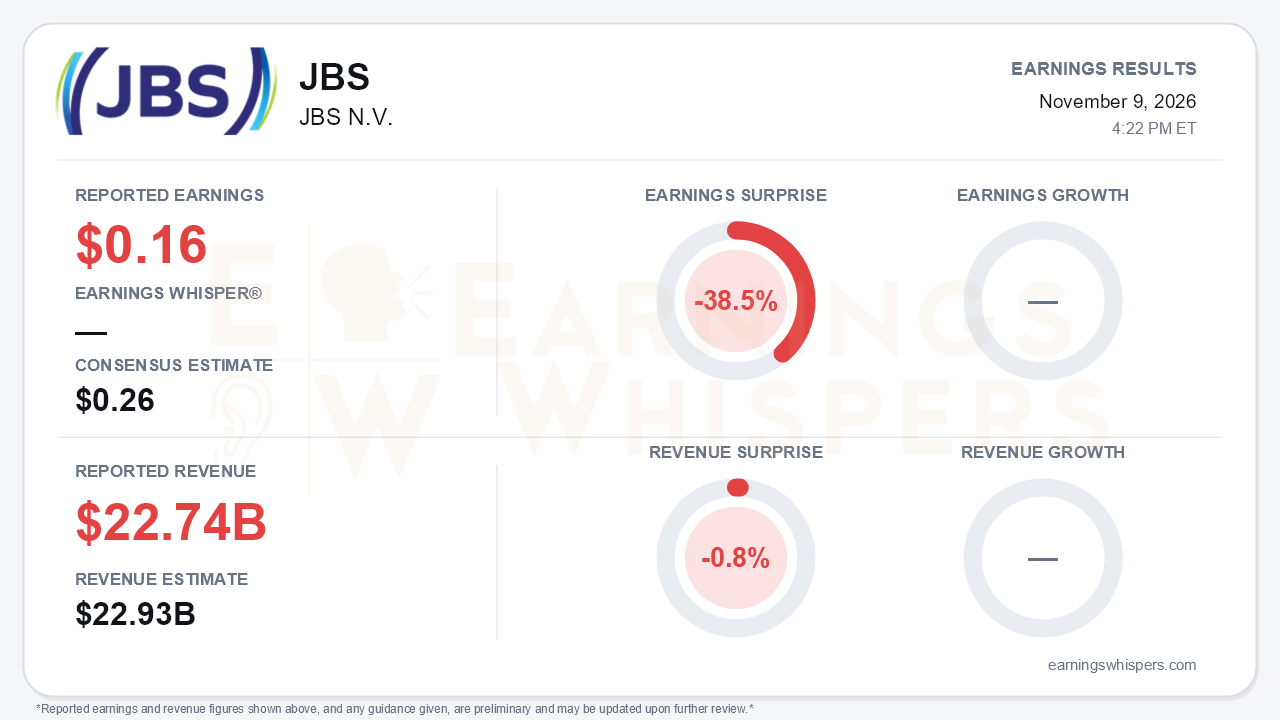
JBS N.V. delivered a clear third-quarter miss. Adjusted EPS of $0.16 fell 38.5% short of the $0.26 consensus and was down from $0.54 a year earlier. Revenue of $22.738 billion missed by 0.8%. Sales were essentially flat, up 1% from the prior year, so the damage came almost entirely from margins. IFRS adjusted EBITDA fell 36% to $1.18 billion, and the margin compressed to 5.2% from 8.1%. The central tension is that the business investors have worried about most, U.S. beef, finally turned the corner just as nearly every other segment weakened at once. The result is a balance sheet that is moving in the wrong direction.
The beat-or-miss question matters less than the breadth of the deterioration.
- **Pilgrim's Pride:** IFRS EBITDA fell 40% to $462 million, and the margin compressed to 9.9% from 16.2%. Cost of sales rose while revenue slipped.
- **JBS USA Pork:** This historically steady unit collapsed. EBITDA was $37 million versus $218 million, the margin was 2.0% versus 9.8%, and it posted an IFRS operating loss. Management blamed global oversupply and inflation-strained U.S. consumers, and the call indicated weakness should persist through the first half of 2027.
- **JBS Brazil:** EBITDA fell 54% after the 2026 China quota was exhausted and cattle costs rose.
- **Australia:** EBITDA dropped 21% on quota completions and record livestock costs.
- **Seara:** IFRS EBITDA edged up 2.5%, but the U.S. GAAP figure declined. Management acknowledged that margins are at their lowest in some time.
The U.S. beef recovery is real but still thin. Monthly margins climbed from -2.9% in July to breakeven in August and +3.9% in September. Segment EBITDA turned positive under U.S. GAAP at $21 million, though it remained slightly negative under IFRS at -$2 million. That improvement followed margins of -2.3% in the first quarter and -1.3% in the second. Management expects a sequentially stronger fourth quarter and supported the outlook with three drivers:
- The reopening of Mexican cattle crossings, worth roughly 1.0 to 1.5 million head a year.
- Industry capacity adjustments.
- Internal integration gains.
For 2027, the company frames U.S. beef market margins in the low single digits plus about 2 points or more from efficiencies and synergies. The CFO noted that each point of North America margin is worth roughly $300 million of EBITDA. That is the credible upside lever in the story, but it remains a management expectation rather than a demonstrated result.
The balance sheet is where bears have the most ammunition.
- **Leverage:** Net leverage rose to 3.54x from 3.1x last quarter and 2.39x at the end of fiscal 2025. Management has now pushed its return to below 3x out to the end of 2027. Earlier in the year the target was 2.5x to 3x by the end of 2026.
- **Cash flow:** Free cash flow was -$167 million versus +$130 million in the second quarter, driven by inventory builds.
- **Raised cost estimates:** The 2026 interest-expense estimate rose to $1.4 billion, and the working-capital consumption estimate grew to -$550 million.
- **Breakeven gap:** Management's free-cash-flow breakeven EBITDA estimate climbed to $5.5 billion. That sits slightly above trailing twelve-month adjusted EBITDA of $5.46 billion.
- **Coverage and returns:** Interest coverage slid to 4.34x from 6.84x, and LTM ROE fell to 8.2% from 23.7%.
Mitigants exist:
- More than 95% fixed-rate debt and no material maturities for five years.
- A revolver expanded to $4.2 billion, lifting liquidity to about $8.2 billion.
- An expected fourth-quarter working-capital release as China 2027-quota beef ships and Seara clears European inventory.
- About $800 million expected from the Australia equity sale to Danantara.
- A planned capex cut of roughly $500 million in 2027.
On the deal front, management chose not to strain the balance sheet. The Flora and Canal Rural acquisitions were paid in shares. The pending proposal to buy the remaining roughly 18% of Pilgrim's Pride, however, keeps capital-allocation questions on the table while leverage is above target. New trade frictions add risk to Seara and Brazilian exports, including a Philippines restriction on Brazilian pork and EU limits on Brazilian poultry.
Investor expectations had already cooled before the print. Earnings Whispers sentiment stayed positive but weakened noticeably, falling from 0.385 to 0.216. The stock has gone nowhere. At $13.12 it is down 0.8% from the open after the August report and sits 6.5% below its 200-day moving average of $14.03. The AVWAP reading remains negative and momentum is neutral, consistent with a market that has been unwilling to pay up for the beef recovery while the rest of the portfolio erodes.
The bottom line is that JBS showed one genuine operating improvement and a lot of slippage around it. U.S. beef's late-quarter momentum and a fourth-quarter rebound in Brazil exports give management a plausible path to sequential improvement. The miss, the pork collapse, negative free cash flow and a leverage target now pushed into 2027 mean that the burden of proof has shifted to the next two quarters.
Read our earnings preview for JBS N.V.: https://www.earningswhispers.com/article/JBS/22641
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-23 | |
| Sep-01 | |
| Aug-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 |
