Natural Gas Services Faces First Full Flat Rock Quarter As Inflation Tests Its Record Margins
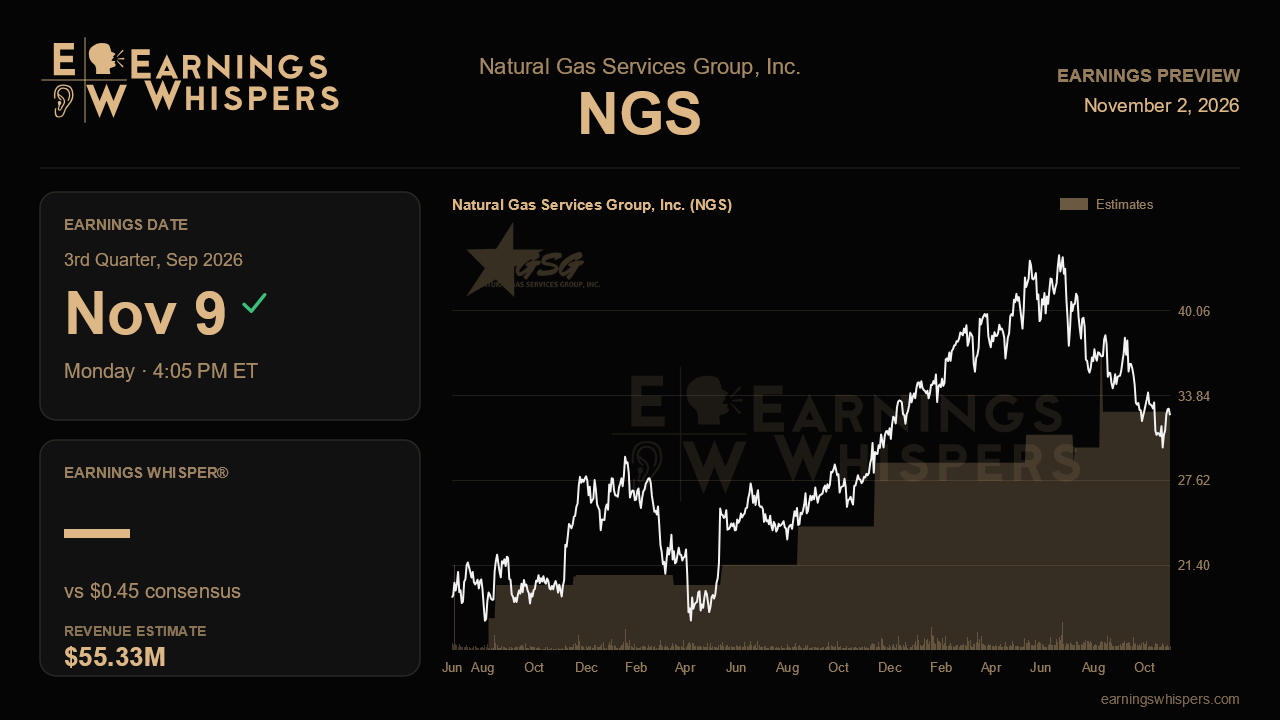
Natural Gas Services Group heads into its third-quarter report with a peculiar disconnect. Management has raised its full-year outlook on three straight calls, closed its largest acquisition, and posted record rental revenue, utilization and EBITDA. Yet the stock has fallen 13% since the last report, trailing the S&P 500 by more than ten percentage points. This quarter is the first full three months with Flat Rock Compression in the numbers, which makes it the cleanest test yet of whether the deal is as accretive as advertised and whether cost inflation is eating into the company's prized rental margins.
The Street is looking for earnings of $0.45 a share on revenue of $55.3 million. That revenue figure implies growth of about 27.5% from a year ago, a strong top-line jump driven largely by the acquired fleet. Earnings, by contrast, are expected to slip roughly 2% from the $0.46 earned in the year-ago quarter and come in a touch below last quarter's adjusted $0.47. That gap is the story in miniature: more horsepower, more revenue, but higher interest costs from deal-related borrowing, heavier depreciation on a larger fleet, and inflation in lubricants, labor and parts are expected to absorb much of the gain on a per-share basis.
Management's full-year adjusted EBITDA target of $103 million to $108 million is the yardstick that matters most. That range kept the organic outlook intact and added roughly six and a half months of Flat Rock, which means the second half has to carry a substantial step-up from the record $25.1 million posted in the second quarter. A third-quarter EBITDA figure that clearly moves toward the high-$20 millions would suggest the range is achievable and perhaps conservative. Anything that leaves the fourth quarter needing heroics would raise doubts about a guide that has only gone one direction this year.
Margins are the swing factor. Rental adjusted gross margin eased to 61.1% last quarter from an unusually strong 63.7%, and management warned that the earlier level was not repeatable while flagging sharply higher lubricant costs tied to refinery constraints. Holding near 61% with Flat Rock fully consolidated would validate the view that pricing power in a tight Permian equipment market can offset inflation. A drop into the high 50s would challenge it. Pricing per horsepower, which has climbed steadily to about $28.06 a month on a pro forma basis, is the counterweight to watch. Utilization, a record 88.3% last quarter, will show whether integrating roughly 87,000 rented Flat Rock horsepower diluted fleet efficiency or not.
There are secondary signposts. Management lifted its organic deployment target to at least 55,000 horsepower and raised growth capex to $60 million to $80 million, so progress on new unit placements matters, as does any update on engine lead times that stretch beyond 100 weeks for the largest units and could crimp growth in early 2027. Leverage rose to 2.77 times after the deal; signs of it beginning to ease would reassure holders worried about the balance sheet. The tax rate should also normalize toward the 25% to 26% guide after a one-time Texas item inflated last quarter's figure, which alone could help reported earnings.
Sentiment has cooled considerably, with bullish readings falling to about 10.5% from 39.4% before the last report, and the stock at $32.40 sits well below its 200-day average of $37.47 and nearer the bottom of its post-earnings range. That lowers the bar somewhat. The central question is whether Flat Rock adds EBITDA at the pace management implied while rental margins hold up against inflation. If both check out, the selloff looks like an overreaction to a business still compounding; if margins crack, the market's skepticism will look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-08 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jul-08 | |
| Jun-15 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-01 | |
| Mar-17 | |
| Mar-16 |
