Natural Gas Services Group Beats On Flatrock's First Full Quarter, But The Implied Q4 Outlook And Higher Leverage Leave Investors Cool
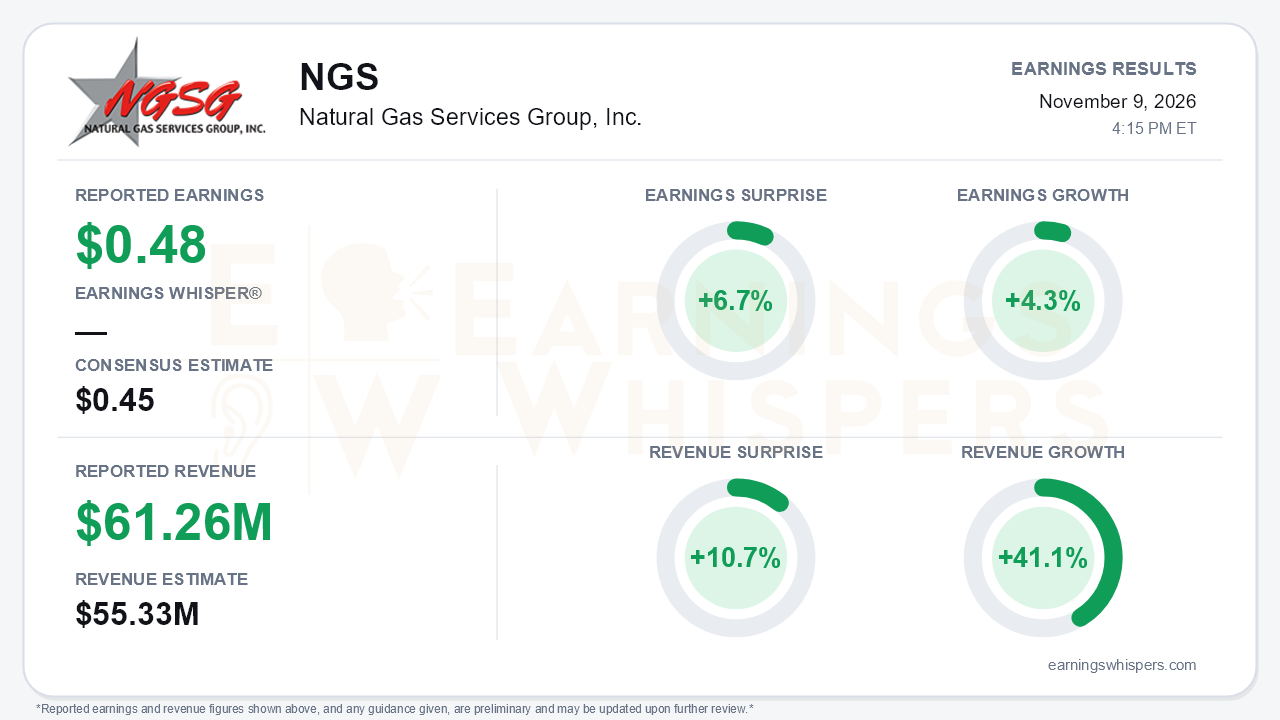
Natural Gas Services Group delivered the first full quarter of Flatrock contribution, and the top line showed it. Adjusted EPS of $0.48 beat the $0.45 consensus by 6.7%. Revenue of $61.26 million topped the $55.33 million estimate by 10.7% and grew 41.1% year over year. Rental revenue reached a record $58.9 million, up 41.9% from a year ago and 19.1% from the second quarter. Adjusted EBITDA rose 42.2% to $29.6 million. The central tension is how little of that growth reached the per-share line. Adjusted EPS grew only 4.3% year over year and barely moved from the second quarter's $0.47. GAAP EPS of $0.43 was actually below the $0.46 reported a year ago.
The quality of the beat is solid operationally, but the gap between EBITDA and earnings deserves scrutiny. The acquisition was funded largely with debt. Interest expense nearly doubled to $6.1 million from $3.4 million, and depreciation and amortization climbed to $13.8 million from $9.2 million as the fleet expanded. SG&A rose to $9.4 million from $5.9 million. Flatrock integration costs of $0.8 million account for the GAAP-to-adjusted difference. That figure was down sharply from $3.3 million in the second quarter, which is why GAAP EPS rebounded sequentially from $0.30. This is a capital-intensive growth model, and the per-share math is lagging the asset growth.
Beneath the headline, the operating trends were constructive:
- Rental adjusted gross margin improved to 62.2% from 61.1% in the second quarter despite inflation.
- Normalized rental revenue per horsepower per month rose to $28.75, up 6.2% year over year and above $28.06 pro forma in the second quarter. That points to continued pricing strength.
- Rented horsepower reached roughly 684,000, up 30% year over year.
- Organic additions of more than 20,000 horsepower in the quarter brought the year-to-date total to about 43,000, keeping the company on track for a 55,000 target that was already raised from 50,000.
The softer spots: utilization slipped slightly to 87.8% from 88.3%, and management acknowledged that lubricant, labor and parts inflation will not all be recovered immediately.
The call preserved a credible growth story beyond 2026. Midstream quoting is at the highest level in company history, a striking change from late 2025, when NGS had no material midstream wins. Management cited large RFPs for the second half of 2027 into 2028 and expressed confidence that 2027 will be a fifth straight year of organic market-share gains. Flatrock is opening cross-selling doors with two large public Midland E&Ps and expanding the company's Eagle Ford density. The pending $4.75 million Tulsa sale, against a roughly $1.5 million carrying value, should produce a gain of about $3 million in the fourth quarter that is excluded from adjusted EBITDA. With that sale, all new-unit fabrication will be outsourced. The company also raised its quarterly dividend to $0.16 and is exploring a 10b5-1 plan to activate its $6 million buyback authorization.
Bears have legitimate ammunition, however. The full-year adjusted EBITDA raise to $105-$108 million lifted only the low end, adding $1 million at the midpoint. Through nine months, adjusted EBITDA totals about $78.9 million, so the guidance implies a fourth quarter of roughly $26-$29 million, at or below the third quarter's $29.6 million. That flattening is consistent with management's inflation caution and the final meaningful integration costs expected in the fourth quarter. Revolver debt stands at $340 million, with leverage at 2.8x versus 2.33x in the first quarter. Management also flagged the possibility that data-center-driven gas demand comes in somewhat below prior expectations after the midterms, and acknowledged that elevated WTI prices are not expected to persist. Growth capex guidance was narrowed to $60-$75 million from $60-$80 million, which management attributed to timing visibility rather than a lower horsepower target.
The market setup is more complicated than the surprise implies. Investor sentiment swung from a solidly positive 0.39 at the prior report to a negative -0.18, a substantial deterioration. Shares are down 22.0% from the $37.25 open after the August report, at $29.07, and sit about 22% below the 200-day moving average of $37.32. The Earnings Whispers trend readings are split. Sequential growth and momentum remain positive, while price and AVWAP trends are negative. That split mirrors the gap between improving operations and a stock the market has been steadily marking down.
The bottom line is that NGS executed well on the integration, pricing and organic growth, and the third quarter was cleaner than the second. However, a debt-funded expansion is producing far more EBITDA growth than per-share earnings growth, and the guidance implies a flat-to-softer fourth quarter. Leverage is near 2.8x, and the 2027 midstream and large-horsepower pipeline is promising but not yet in the numbers. Until that pipeline converts and leverage begins to ease, investors appear unwilling to pay for the growth story despite the beat.
Read our earnings preview for Natural Gas Services Group, Inc.: https://www.earningswhispers.com/article/NGS/22651
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-08 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jul-08 | |
| Jun-15 | |
| May-12 | |
| May-11 | |
| May-11 |
