Lattice Delivers A Blowout Quarter And A First Multi-Year Outlook, But A Stock Near Its Lows Signals Doubts About Durability
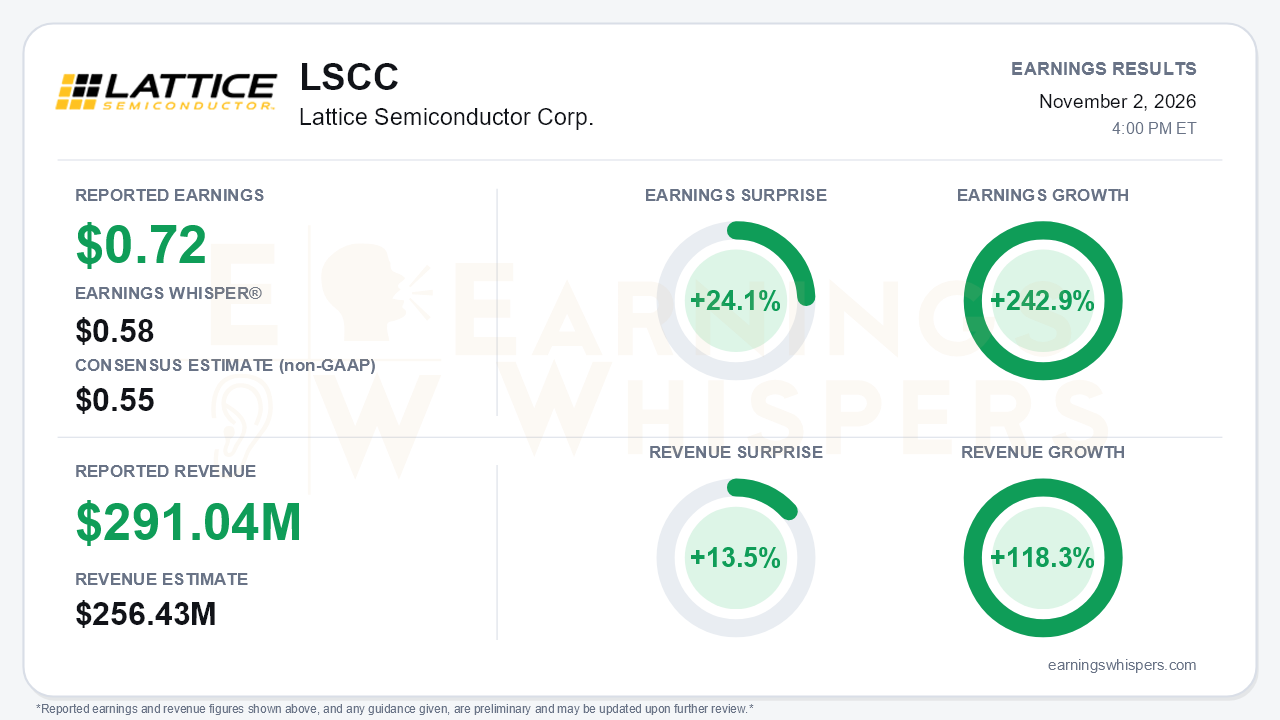
Lattice Semiconductor (NASDAQ: LSCC) delivered one of the stronger beat-and-raise quarters in semiconductors this cycle. Non-GAAP EPS of $0.72 topped the $0.55 consensus by 24.1% and cleared the $0.58 Earnings Whisper number. Revenue of $291.04 million beat the $256.43 million consensus by 13.5% and rose 118.3% year over year. Earnings Whispers puts year-over-year EPS growth at 242.9%; management cited roughly 160% against its own prior-year non-GAAP figure of $0.28. Either way, the earnings expansion was large. Management also gave its first multi-year outlook: 2027 revenue growth of at least 60%, to about $1.6 billion, and a revenue CAGR above 30% over five years. The central tension is that shares entered the report down nearly 30% since the last one. The market has been pricing in fears of a demand peak that management's numbers do not yet show.
The headline growth needs one adjustment. About $39.1 million of revenue came from AMI, the platform-firmware business acquired July 27. Without AMI, FPGA revenue was roughly $252 million, still up about 90%, and that core growth is the real story. Compute and Communications revenue reached $171.9 million, up 132%. That is a sharp acceleration from 83% growth in Q2 and 86% in Q1. Industrial and Embedded grew a more modest 35% to $80.0 million. Non-GAAP operating margin expanded to 41.1% from 38.3% in Q2 and 34.4% in Q1. Adjusted EBITDA margin reached 45%.
GAAP results look much weaker. GAAP EPS fell to $0.08 from $0.14 in Q2. The drop came from:
- $25.9 million of acquisition-related charges;
- $12.9 million of intangible amortization;
- $9.6 million of new interest expense on the AMI debt;
- $50.7 million of stock-based compensation.
Investors who discount heavy non-GAAP add-backs have a fair point here. The gap between GAAP and non-GAAP earnings is now very wide.
The call supported the bullish case. Q3 revenue far exceeded the $245-265 million range guided in August. Gross margin of 70.9% beat the 69.5% guide, and Q4 gross margin is guided to 72%. Q4 guidance calls for:
- revenue of $325-345 million, about 130% year-over-year growth;
- non-GAAP EPS of $0.82-0.86;
- Industrial and Embedded growth accelerating to about 70%.
That implies fiscal 2026 revenue of roughly $1 billion and EPS near $2.50. The year began with an "at least 20%" growth framework. Backlog now extends into 2028, versus "well into 2027" earlier in the year, and is supported by multi-year customer agreements. The FPGA attach rate per server is now "starting with a 4," up from a target of more than three a year ago. Management expects AI servers to rise from about 25% to about 40% of units in 2027.
The risks are clear. Management said it planned the second half of 2027 conservatively, which implies growth will moderate. Supply problems are visible in several places:
- Q3 revenue arrived late in the quarter because of a supply bottleneck.
- Inventory and receivables are building.
- Suppliers are raising costs and charging expedite fees, which Lattice is passing through to customers.
Free cash flow slipped to $77.6 million from $81.3 million as capital spending on test capacity rose. Analysts raised concerns about double ordering and cyclicality, and Altera is pushing into AI-assisted FPGA design tools. The AMI deal left about $869 million of long-term debt, so buybacks take a back seat to repayment. Management did pull forward its target of net leverage below 2x EBITDA by a year, to the end of 2026, after paying down $50 million. On the catalyst side, four joint Lattice-AMI solutions have launched. Security retrofit has reached first production, and tens of customers are in proof-of-concept.
The market had been heading the opposite direction. Shares closed at $92.97 before the report, down 29.7% from the $132.30 opening after the August release. That leaves them 19.6% below the 200-day moving average and just 2.5% above an inter-earnings low set October 30. The quarterly high of $138.61 came on the day after the last report, so the entire post-August rally was given back. Investor sentiment stayed barely positive but weakened meaningfully, falling from 0.20 to 0.02. The Earnings Whispers trend signals are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Lattice answered the near-term demand question decisively. It beat its own guidance by a wide margin, accelerated core compute growth, and gave a 2027 target that extends visibility well past the current quarter. What it could not fully settle is whether this growth is durable or partly the product of supply-constrained, possibly double-ordered AI demand. The conservative second-half 2027 plan and the inventory build leave room for that doubt. With sentiment deflated and shares near their lows, expectations were reset well below the fundamentals going in. Execution against the 2027 framework, rather than another beat, is now the key test.
Read our earnings preview for Lattice Semiconductor Corp.: https://www.earningswhispers.com/article/LSCC/21409
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 6 hours | |
| 11 hours | |
| 16 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Sep-29 |
