Occidental's Midstream Windfall Fades As Deleveraging Story Faces Its First Real Test
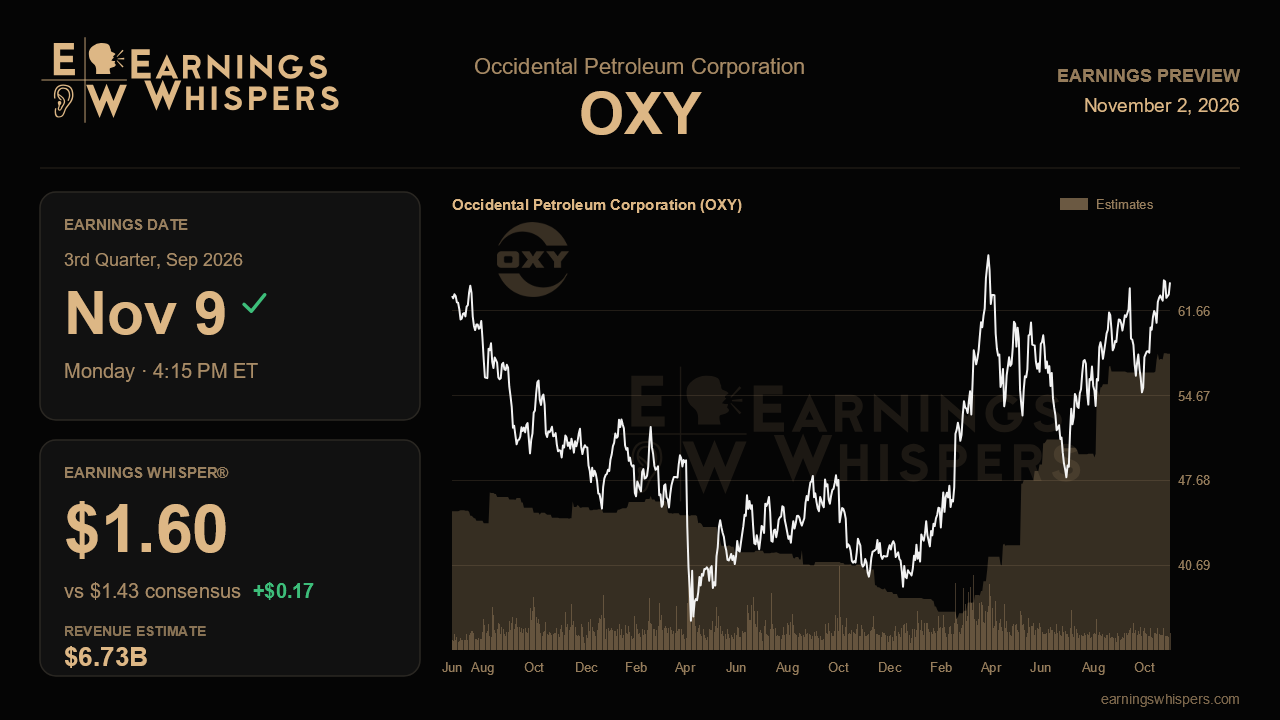
Occidental Petroleum enters its third-quarter report with a peculiar setup: the company just delivered its best free cash flow quarter in nearly four years, yet management spent part of the last call telling investors that one of its biggest recent profit engines is about to cool off. When results arrive after the close on November 9, the question is whether the core upstream business and a leaner balance sheet can carry the story once the unusual midstream gains start to shrink.
The Street is looking for earnings of $1.43 per share on revenue of roughly $6.73 billion. That would be more than double the $0.64 earned a year ago, a gain of about 123%, while revenue is essentially flat versus the prior-year $6.72 billion. The gap between those two growth rates tells the story. Occidental is not selling much more; it is keeping far more of what it sells, helped by sharply lower interest costs and better realizations. The consensus figure is also a steep step down from the $2.40 posted last quarter on $8.33 billion in revenue, which reflects management's own warning about a softer third quarter. The whisper number of $1.60 sits meaningfully above consensus, suggesting that more aggressive investors believe the analysts have over-discounted the midstream fade.
That midstream line is the swing factor. Second-quarter midstream earnings hit a record near $960 million, more than double the guidance midpoint, as the price gap between Waha and the Gulf Coast blew out. Management has raised full-year midstream guidance twice, by $800 million and then another $300 million, but cautioned that roughly 3 billion cubic feet per day of new Permian takeaway capacity, with about 2 more coming by the fourth quarter, should compress that spread. The offset, in theory, is better gas prices for the upstream business. A report that shows upstream realizations genuinely picking up the slack would validate that framing. A midstream decline that arrives without a visible upstream benefit would challenge it.
Costs and volumes deserve close attention too. Domestic operating costs were guided up to $8.75 per barrel of oil equivalent from $7.80 in the second quarter, blamed on Gulf of America maintenance timing and weather, while the full-year $8.10 target was held. Coming in at or below that elevated figure would support the idea that the bump is temporary. Production beat the midpoint by 23,000 barrels per day last quarter, and full-year guidance was raised after an earlier cut, so another solid volume print would show the operating improvement is durable. International output, pressured by Middle East disruptions and sulfur logistics at Alhosn, remains a source of noise.
The bigger long-term narrative is the new plan to lift sustainable annual cash flow by $4 billion by 2030, built on about $900 million in lower sustaining capital and a base decline easing from roughly 25% to 20%. One quarter cannot prove that, but progress on Stratos commissioning ahead of its targeted year-end timing, further debt reduction from the $11.8 billion principal level, and capital spending inside the $5.5 billion to $5.9 billion range would all add credibility.
The market has already leaned in. Shares are up 13.4% since the last report while the S&P 500 slipped 1.9%, and at $64 the stock trades well above its 200-day average near $56 and within about 1.5% of its post-earnings high of $64.96, putting a breakout in view. Sentiment, however, has cooled to 21.3% bullish from 42.5% a quarter ago, an interesting divergence between price and conviction. Ultimately, this report hinges on whether Occidental can show that its cash-flow strength survives the loss of an unusually generous midstream tailwind. If it can, the 2030 plan starts to look like a base case rather than an aspiration.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 9 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-18 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-05 | |
| Oct-04 | |
| Oct-01 |
