Occidental Beats On Execution And Accelerated Debt Paydown, But Earnings Step Down From Record Q2
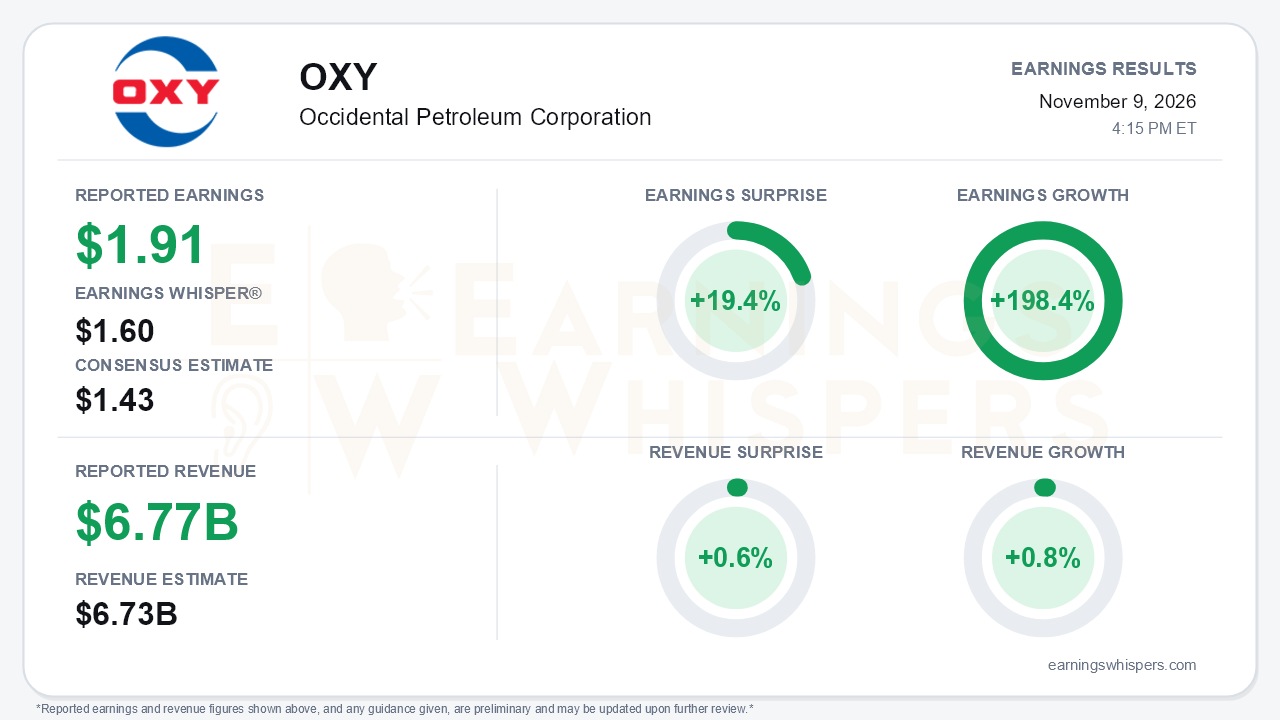
Occidental Petroleum (NYSE: OXY) cleared a low bar with room to spare. The company reported earnings of $1.91 per share for the third quarter, well above the $1.43 consensus and the $1.60 Earnings Whisper number, a 19.4% surprise. Earnings grew 198.4% from a year ago. Revenue of $6.772 billion edged past the $6.73 billion consensus by 0.6% and grew just 0.8% year over year. That gap between near-flat revenue and sharply higher earnings is the first clue to the quarter. Occidental is not growing its top line. It is extracting more from the same revenue base through cost discipline and a rapidly shrinking interest burden. The headline beat was real, but the more consequential development was the balance sheet. Management hit its $10 billion principal debt milestone ahead of schedule and immediately set a new $6 billion target.
The quality of the beat still deserves scrutiny, because the sequential picture moved the wrong way. Adjusted EPS fell to $1.91 from $2.40 in the second quarter. Free cash flow slipped to roughly $2.8 billion from about $3 billion. Most of the swing came from midstream. Adjusted pre-tax income in that segment dropped to $309 million from roughly $960 million as Waha-to-Gulf Coast gas spreads narrowed. Domestic lease operating expense also crept up to $8.54 per BOE from $7.80. Consensus evidently anticipated much of this deceleration, which is why a sharp sequential decline still produced a large beat. Investors should read this as a strong quarter relative to cautious expectations, not as an acceleration in earnings power.
The operating story on the call was better than the earnings trajectory suggests. Production of 1.43 MMBOE/d beat the guidance midpoint by 7 MBOE/d, with U.S. onshore alone 20 MBOE/d ahead. New Mexico set a record of 284 MBOE/d gross operated, and Powder River Basin net output grew more than 70% from the first quarter to 23 MBOE/d. The EOR sidetrack and horizontal program, a small mention earlier in the year, has scaled to about 80 sidetracks. It added 10,000 BOE/d, with 500 more candidates identified. Fourth-quarter production guidance of 1.43-1.47 MMBOE/d sits above the prior quarter's range. Management also reaffirmed its 2027 framework: $5.9 billion of capex, flat BOE volumes, flat-to-up oil, and $700-800 million of sustainable cash flow improvement. Full-year midstream guidance is now about $2 billion, up from a $1.1 billion midpoint in the first quarter. That sits awkwardly beside the third-quarter collapse in the segment. It implies the year's midstream windfall was heavily front-loaded and that the run-rate is now normalizing lower.
The capital-return narrative is the key catalyst. Principal debt has fallen from about $15 billion at the end of 2025 to below $10 billion, with $10.4 billion repaid year to date. Reaching $6 billion would cut the interest run-rate to around $400 million, roughly $1 billion below 2025 levels. Management went further and floated a possible net cash position in 2027 with opportunistic buybacks to follow. That is a far more explicit path than in the second quarter, when it declined to set a post-$10 billion target. The CO2 offtake agreements for 2 MMtpa and Stratos nearing full startup add optionality in carbon management. However, Stratos levelized capture costs rose about 10%.
Bears have legitimate ammunition for the near term. Management guided to lower midstream gas marketing and sulfur income in the fourth quarter, along with higher domestic LOE on CO2 costs and workovers. Gulf of America output, about 110 MBOE/d, was hit by a third-party pipeline constraint and an October hurricane that extends into the fourth quarter. Volumes there may dip in 2027 as capital is front-loaded into Horn Mountain injectors. OxyChem-related tax outflows from discontinued operations also consumed about $455 million in the quarter and $1.4 billion year to date. Those payments are a drag on cash available for debt reduction.
Investor sentiment tells a cooler story than the surprise. Earnings Whispers sentiment fell from 0.43 at the prior report to 0.09, a meaningful deterioration that leaves it only marginally positive. The stock has gone nowhere. At $55.76, shares are down 1.2% from the $56.43 open after the August report and sit about 1.2% below the 200-day moving average of $56.45. The trend readings are mixed, with momentum positive but AVWAP still negative.
The bottom line is that Occidental delivered an execution-and-deleveraging quarter wrapped in a sequential earnings decline. The beat over consensus was large, but the true change in the setup is the accelerated path toward $6 billion of debt and a potential 2027 net cash position with buybacks. The market's flat price action and fading sentiment suggest investors want to see that balance-sheet progress offset softer midstream income and rising costs in the fourth quarter.
Read our earnings preview for Occidental Petroleum Corporation: https://www.earningswhispers.com/article/OXY/22659
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Oct-18 | |
| Oct-14 | |
| Oct-14 |
