PubMatic's AI Pivot Faces Its First Proof Point As Shares Slide Back Toward Lows
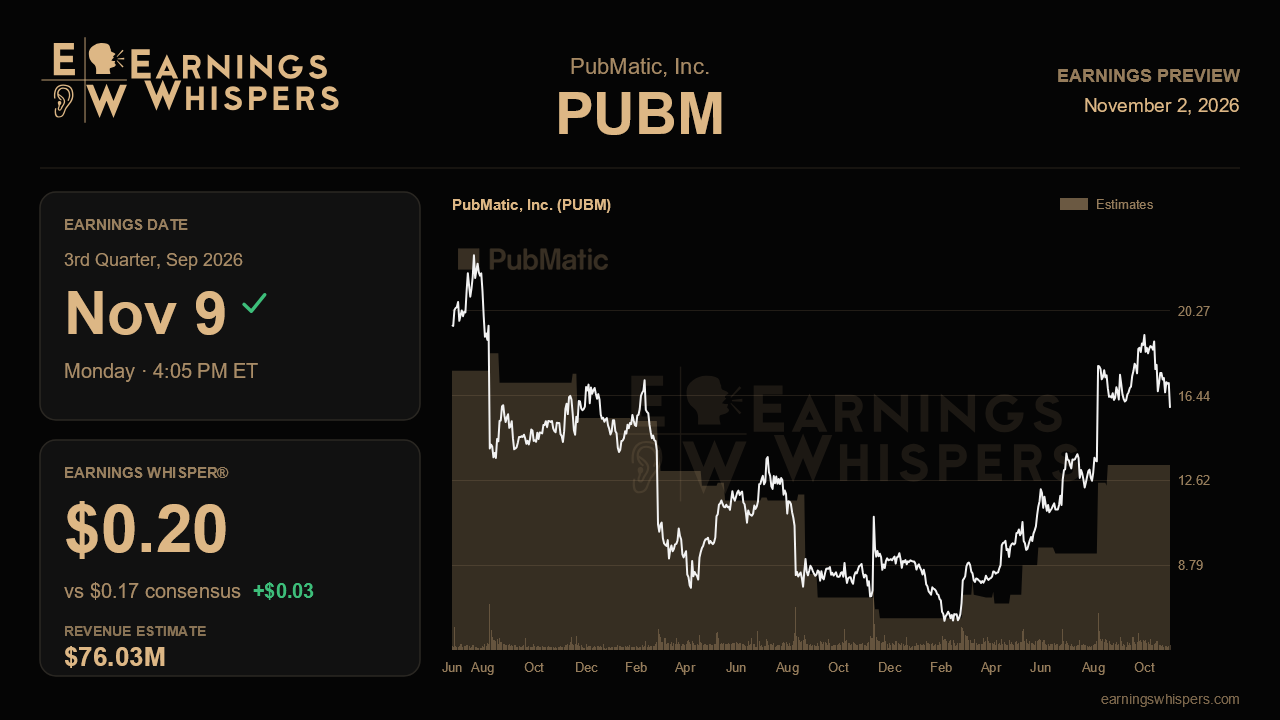
Three months ago PubMatic told investors its long defensive stretch was over. Revenue growth had snapped back to double digits ahead of schedule, the legacy demand-side platform headwind that dogged results for most of a year was fully lapped, and management sounded more confident about monetizing agentic AI than at any point in the turnaround. The stock initially loved it, then gave much of the move back. That leaves the third-quarter report, due after the close on November 9, as the first real test of whether the offense-minded story can hold up under a full quarter of scrutiny.
The Street is looking for earnings of $0.17 per share on revenue of $76.0 million, which would be roughly 12% growth from the $68.0 million posted a year ago. That revenue figure lands exactly at the midpoint of management's $75 million to $77 million guidance range, and it is worth noting how far analysts have moved. When the guide was issued, consensus sat near $71.4 million, so the Street has essentially adopted the company's outlook wholesale. The Earnings Whisper of $0.20 sits modestly above consensus, suggesting some expectation that operating leverage will show up again. A result near the midpoint would confirm the reacceleration but would not, by itself, be much of a surprise.
The more important evidence lies beneath the headline. Management pointed to second-half acceleration, so the fourth-quarter outlook may matter more than the third-quarter print. Investors should want to see the momentum drivers holding firm: mobile app growth jumped to roughly 40% last quarter from about 25%, emerging revenues reached about 15% of the total after nearly doubling, and mid-market DSP spend kept growing around 25%. Agentic activity is the newest and least proven piece. Campaigns climbed to more than 80 from 30 a quarter earlier, and AI-powered deals topped 4,000, but the company still describes adoption as early. Another step up in those counts, alongside early signs of revenue from Decision Fabric, the Sony Pictures Entertainment partnership and the Creator Marketplace, would validate the claim that these are additive catalysts rather than press-release material. A stall would suggest the narrative is running ahead of the numbers.
Profitability is the other swing factor. Adjusted EBITDA margin expanded to 25% from 20% a year earlier and free cash flow rose 47%, yet capital spending guidance has climbed repeatedly, now to $20 million to $25 million for the year to fund NVIDIA-powered AI workloads. Management argues the payback is under 12 months. Continued margin expansion despite that spending would support the argument; any sign that capex is outrunning revenue would challenge it. Softness in food and drink, arts and entertainment, and travel advertising also bears watching, as does any update on the search to replace retiring CFO Steve Pantelick, though his transition runs into early 2027.
The tape tells a story of fading enthusiasm rather than outright doubt. Shares are down 8.5% since the last report, trailing the S&P 500 by about 6.5 points, and at $15.89 they sit just above the $15.64 post-earnings low, well off the $19.48 high. Still, the stock trades comfortably above its 200-day moving average of $12.09 and far above the prior quarter's range, so the reset has trimmed rather than erased the gains. Sentiment has improved notably, with bearishness easing to a slight lean from a much more skeptical reading ahead of last quarter.
The central question is whether PubMatic can show that its reacceleration is broadening, with AI and agentic initiatives starting to carry measurable weight while margins absorb heavier investment. Hitting the midpoint keeps the story intact; a firm fourth-quarter outlook and tangible agentic traction are what would revive it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-15 | |
| Oct-06 | |
| Oct-05 | |
| Sep-18 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 |
