PubMatic's Third Straight Revenue Acceleration And A Doubling Of EBITDA Beat Estimates, But Q4 Guidance Implies A Slight Growth Slowdown
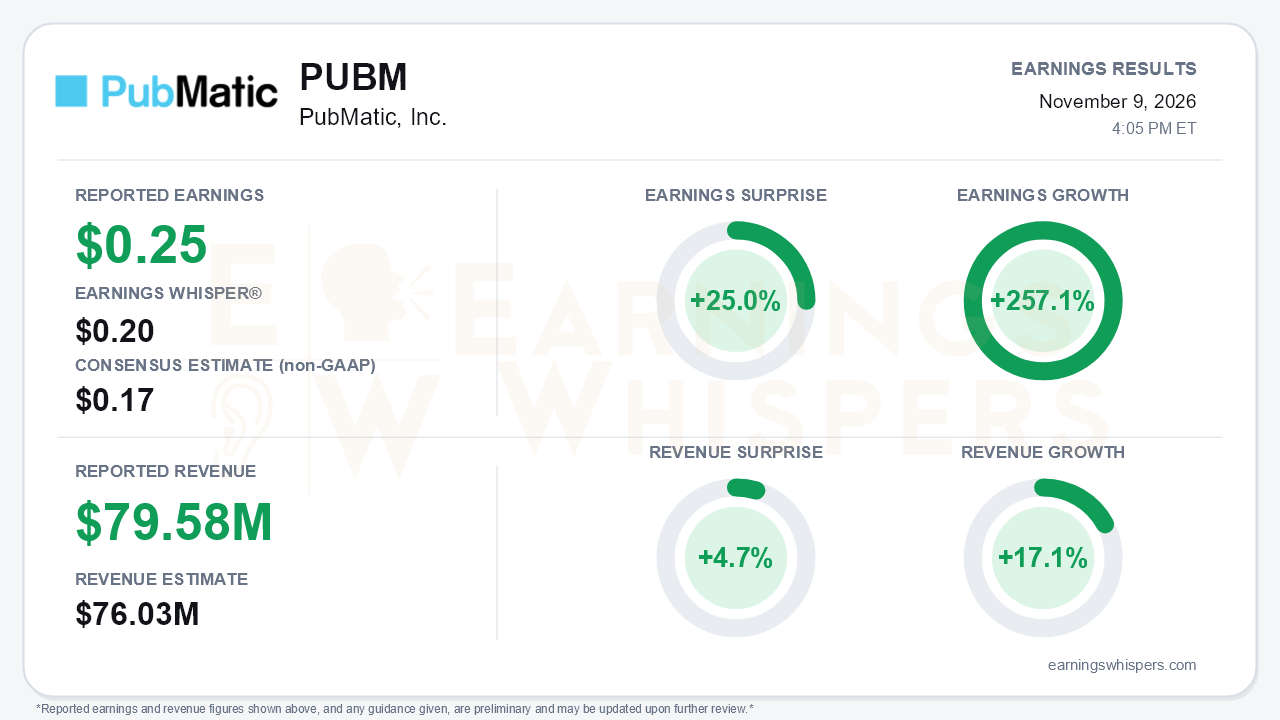
PubMatic delivered the kind of quarter turnaround skeptics were not positioned for. Non-GAAP earnings of $0.25 per share topped the $0.17 consensus by 25.0% and cleared the $0.20 Earnings Whisper number. Earnings grew 257.1% from the $0.03 earned a year earlier. Revenue of $79.58 million beat the $76.03 million consensus by 4.7% and grew 17.1% year over year. That was the third consecutive quarter of acceleration, up from 11% in Q2. It also came in well above the company's own $75-77 million guide. The central takeaway is that PubMatic's mix shift toward higher-value channels has started producing both faster growth and dramatically higher profitability at the same time.
The bottom-line improvement was real on a GAAP basis, not just a non-GAAP one. GAAP net income was $5.5 million, or $0.11 per diluted share, versus a $6.5 million loss a year ago. Operating income swung to $8.7 million from an $8.4 million loss. Adjusted EBITDA more than doubled to $26.0 million, a 33% margin. That compares with a 25% margin in Q2, 16% a year ago and a $17-19 million guide. Gross margin rose to roughly 70% from 63%.
The quality of the beat does deserve some scrutiny, however:
- About two points of the gross-margin gain came from extending server useful lives from three to five years. That is an accounting benefit that fades over time.
- Operating expenses fell 8% year over year partly because hiring slipped into Q4, so costs are set to ramp.
- Free cash flow of $17.6 million improved from $13.7 million in Q2 but trailed the $22.8 million of a year ago. Equipment purchases roughly doubled.
The operating detail is where the quarter looks strongest. Growth in nearly every strategic line stepped up sharply from Q2:
- **CTV:** grew more than 30% globally, versus 13% in Q2, and more than 40% in the Americas, versus 25%. CTV is now about 21% of revenue.
- **Mobile app:** grew nearly 40% and reached about 27% of revenue.
- **Emerging revenues:** more than doubled to roughly 18% of revenue, up from 15% in Q2 and 14% in Q1.
- **Activate direct buying:** grew more than 8x, an acceleration from more than 2x in Q2.
- **Mid-market DSP spend:** rose more than 40%, versus 25% in Q2.
Altogether, channels representing nearly two-thirds of revenue are growing above 50%. The agentic push is also gaining real traction. Fully autonomous campaigns exceeded 120, up from 80 a quarter ago and including all five holding companies, and AI-powered deals reached 14,000, up from 4,000. Efficiency gains reinforce the story: monetized impressions rose 15% while impressions processed fell 8%.
Guidance preserved a credible growth story but is not without caveats. Q4 revenue is guided to $91-93 million, which is 15% growth at the midpoint and above estimates. Full-year guidance calls for $312-314 million in revenue (+11%) and $79-81 million in adjusted EBITDA (+30%). That implies second-half growth of roughly 16% after a first half near 5%. Still, the 15% Q4 midpoint represents a modest step down from Q3's 17%, even though political advertising is expected to contribute 7-8% of Q4 revenue. Management described the outlook as prudent, citing a post-election pause in ad pacing.
Bears have legitimate ammunition on several fronts:
- The political revenue sets up a tougher 2027 comparison.
- Capital expenditures were raised for the third time this year, to $24-28 million, as GPU investment grows.
- The legacy DSP relationship is stable but not expected to grow.
- Business and food-and-drink verticals remain soft.
- Management cites low-single-digit revenue exposure to Safari/iOS WebKit changes.
- The CFO succession is still unresolved.
On the catalyst side, management highlighted a partnership with OpenAI to power ChatGPT ads, which opens a new category of AI-platform inventory. Potential Google ad tech remedies offer further upside that is excluded from guidance. The board also added $150 million to the buyback, bringing capacity to about $198 million through 2028. That is backed by $144.5 million in cash and securities and no debt.
The market setup is more complicated than the surprise implies. Investor sentiment was negative heading into the prior report, at -0.33, so expectations had been subdued. Shares opened at $17.36 after the August report and climbed to a 52-week high of $19.48 on October 2. They then slid roughly 21% to an inter-earnings low of $15.40 on November 2, just a week before this report. The stock therefore entered the release near the bottom of its range, though still comfortably above its 200-day moving average of $12.36. Momentum and AVWAP trend readings remain positive, while the price trend is neutral. That is consistent with a longer-term uptrend that lost steam into the print.
The bottom line is that PubMatic answered the central question of whether its mix shift could translate into accelerating, profitable growth, and the answer was emphatically yes. Revenue accelerated again, EBITDA margins doubled and every high-value channel sped up. The OpenAI deal adds a meaningful new avenue. Investors should nonetheless discount part of the margin gain as accounting-driven, expect Q4 cost and capex pressure, and keep an eye on the political-driven 2027 comparison. The modest deceleration embedded in the Q4 guide also bears watching.
Read our earnings preview for PubMatic, Inc.: https://www.earningswhispers.com/article/PUBM/22663
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-15 | |
| Oct-06 | |
| Oct-05 | |
| Sep-18 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 |
