Plug Power's Turnaround Faces A Credibility Test As Shares Sink Toward Lows
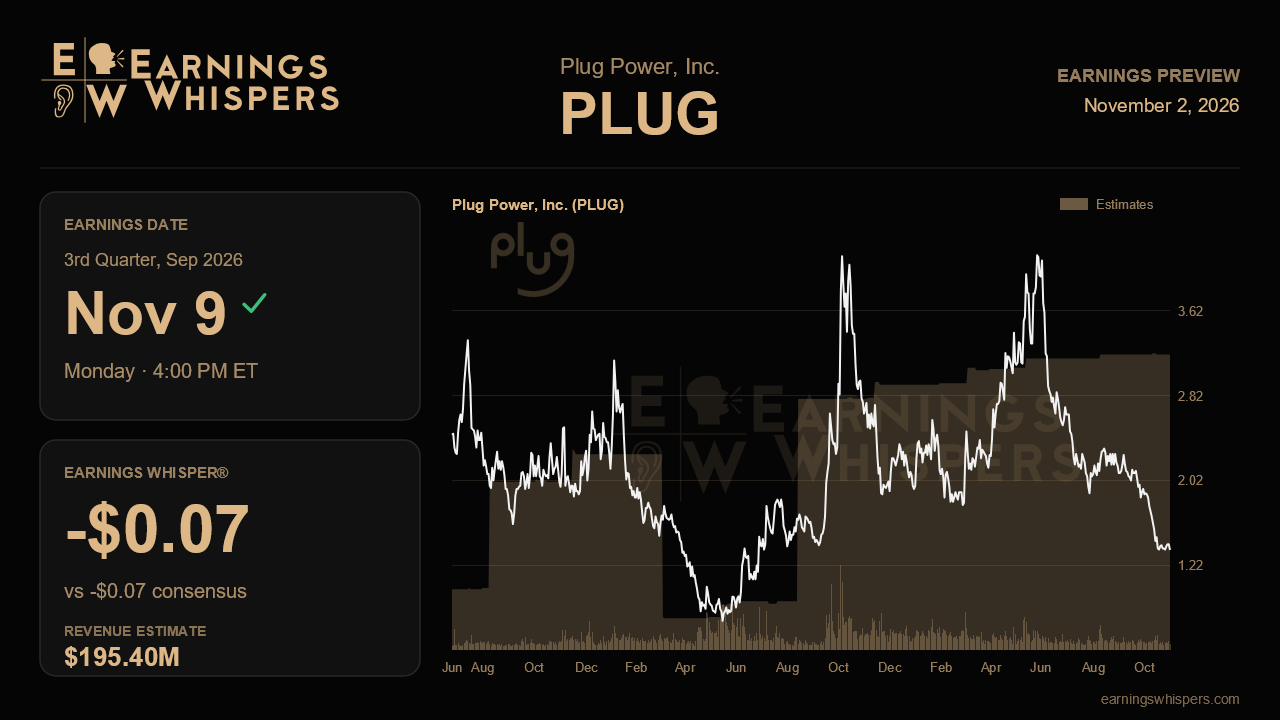
Plug Power heads into its third-quarter report with an awkward contradiction. Last quarter management delivered its most upbeat update in a year, raising full-year revenue guidance, pushing gross margin to roughly breakeven and cutting cash burn sharply. The market has since cut the stock nearly in half. That gap between narrative and price makes the November 9 release less about the headline numbers and more about whether the turnaround is as durable as management claimed.
The Street is looking for a loss of 7 cents a share on revenue of about $195.4 million. The Earnings Whisper matches consensus, so there is no hidden bar to clear. A 7-cent loss would equal last quarter's adjusted result and improve on the 12-cent loss of a year ago, while revenue growth of roughly 10% would be solid but not spectacular. That growth rate is worth a closer look. Management lifted its fiscal 2026 growth target to 15% to 16% from 13% to 15%, and a third quarter running near 10% implies the year leans heavily on the fourth quarter. Any reaffirmation of the raised range therefore carries an implicit promise of a strong finish, and investors should press for evidence that the backlog supports it.
Margins are the heart of the story. Gross margin improved to about negative 0.9% last quarter from negative 13% in the first quarter and negative 30.7% a year earlier, and management framed the gains as structural. Validating that claim means holding near breakeven or crossing into positive territory. Fuel margin is the swing factor: it improved dramatically year over year to negative 48% but stalled sequentially, so further progress there would show cost work still has room to run. The fourth-quarter goal of positive EBITDA, which management described as well within reach, depends on this. Operating expenses also need scrutiny, since last quarter's $62 million figure was flattered by a $37 million one-time contract recovery. A clean quarter near the targeted $75 million run rate is the honest baseline.
Demand signals should help. Material handling was the standout, with 1,666 GenDrive units deployed versus 739 a year ago and service revenue up 82%. Management also flagged a refresh opportunity of more than 20,000 units over three years from its two largest customers, and any timing detail would make that figure more tangible. On electrolyzers, the company finally converted pipeline talk into final investment decisions, including 30 megawatts for Carlton Power in the UK and 50 megawatts for Orica in Australia, plus a 275-megawatt engineering study in Quebec. Investors should want to see these orders flowing into revenue schedules rather than simply being repeated.
Cash remains the pressure point. Net cash use fell to $61 million last quarter, roughly 58% lower sequentially, and keeping burn at or below that level matters for a company trading at $1.37. The $275 million asset monetization program is part of that equation, and the Texas review of data center construction adds uncertainty to the Graham site sale to Stream, though $52 million has already been collected. An update on closing the remainder would ease a real concern. GAAP results may also look different this time, since last quarter's $104 million mark-to-market charge on convertibles and warrants stemmed from a rising stock price, and the steep decline could swing that line the other way.
Sentiment has soured, with the bearish tilt deepening from last quarter, and the stock sits far below its 200-day average of $2.40 and just above its post-earnings low of $1.34. Expectations for the share price are clearly depressed even if operating estimates are not. The central question is simple: can Plug show that near-breakeven gross margin and shrinking burn are a new floor rather than a high-water mark? If so, the selloff looks overdone. If margins slip or the fourth-quarter EBITDA goal softens, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-29 |
