Plug Power Misses On Adjusted EPS As Record-Low Cash Burn Collides With A Heavy Q4 Revenue Hurdle
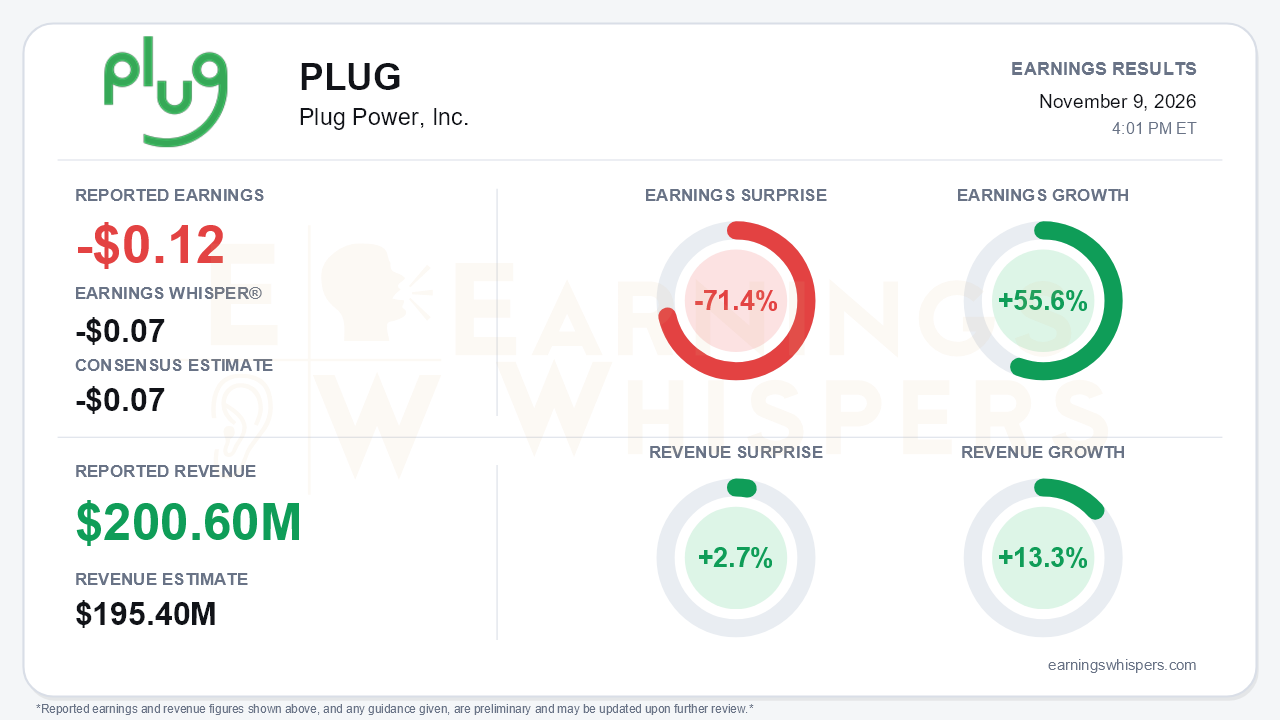
Plug Power's third quarter splits cleanly in two. On an adjusted basis the company lost $0.12 per share, worse than both the consensus estimate and the Earnings Whisper number of -$0.07, a 71.4% negative surprise. Revenue of $200.6 million beat the $195.4 million consensus by 2.7%. The year-over-year view is much better: earnings improved 55.6% and revenue grew 13.3%. Net cash usage also fell to a record-low of roughly $28 million. That is the central tension. The cost-cutting story is working, but the bottom-line miss and a fragile cash position leave little room for error heading into a fourth quarter that has to carry the year.
The headline GAAP number needs context. Plug reported GAAP basic EPS of $0.07 and net income of $99.8 million. That result rests on about $192 million of non-cash mark-to-market gains on convertible debt and warrant liabilities. Management itself acknowledged those gains were the primary reason EPS was positive, and they account for roughly $0.12 per share. Strip them out and the quarter was a loss. Operating expenses also need a closer look. The roughly $70 million total, down from $229 million a year ago, includes a $25.8 million gain on asset sales alongside $16.6 million in impairments. The year-over-year gross margin improvement is real. Gross margin moved from about -68% to about -3%, helped by much smaller inventory charges and a $10.4 million loss-contract benefit. Even so, Plug still sold product at a loss.
The call showed a business improving on some lines and slipping on others. Revenue has climbed steadily from $163.5 million in Q1 to $178.3 million in Q2 and $201 million in Q3.
- **Improving lines:** Service margin reached 31%, up from 27% in Q2 and -2% a year ago. PPA margin improved to -16% from about -30%.
- **Slipping lines:** Consolidated gross margin weakened to -2.7% from -0.9% in Q2, which management tied to electrolyzer scale-up costs. Fuel margin, while far better than last year's -79%, slipped to -52% from -48% after unplanned plant outages forced external hydrogen purchases.
- **Deployments:** GenDrive deployments of 1,136 units more than doubled year over year but fell from 1,666 in Q2.
- **Electrolyzers:** This is the bigger reversal. Electrolyzer revenue fell about $40 million year over year, and the segment is now expected to finish 2026 slightly down. That undercuts the earlier framing of electrolyzers as a growth driver.
The catalysts are meaningful but mostly future-dated:
- **Arcadia eFuels:** A 280 MW electrolyzer agreement for Project Endor in Denmark, plus preferred-supplier status on more than 1 GW of potential projects. The release itself cautions that some Arcadia agreements are non-binding or conditional.
- **Walmart:** A GenDrive refresh of roughly 2,000 to 2,500 units starts in Q4.
- **Product and customers:** Next-generation GenDrive is expected in early 2027, and management cited four to five potential new material handling customers.
The risks are more immediate:
- **Q4 revenue hurdle:** Reaffirmed, not raised, guidance for 15% to 16% revenue growth implies roughly $280 million in Q4. That is about a 40% sequential step-up, and management conceded some commercial items still need to close.
- **Asset monetization:** The Stream data center program, once pitched at more than $275 million, has stalled at about $51 million received because of regulatory and permitting issues. No proceeds are in the Q4 forecast.
- **Liquidity:** Unrestricted cash fell to $134 million from $162 million in Q2 and $223 million in Q1. Restricted cash run-off is now cited at about $40 million a quarter, down from about $50 million.
The quality of the cash improvement also deserves scrutiny. Net cash usage measures only the change in unrestricted cash. Year-to-date operating cash outflow was still $320.5 million, partly offset by asset-sale proceeds, a $36 million investment tax credit sale and restricted-cash drawdowns. Management expects Q4 cash usage to be roughly flat and still targets positive EBITDAS in the quarter.
The market had already turned hard against the stock before the report. Shares stood at $1.45 heading into the release, down 41.5% from the $2.48 open after the August report. They were about 39% below the $2.38 200-day moving average and just 11.5% above the $1.30 52-week low set on November 2. Investor sentiment, already slightly negative, became modestly more negative, sliding from -0.076 to -0.116. That is a meaningful but not dramatic deterioration. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative. Those readings reflect improving operating numbers against a chart still dominated by sellers.
Management's tone also shifted, from the 'never more confident' framing of the Q2 call to a steadier, execution-focused message. That fits a quarter in which several earlier promises, including Stream proceeds and electrolyzer growth, were walked back even as cost discipline delivered.
The bottom line is that Plug's operational turnaround is visible in service margins, opex and cash burn, but the adjusted EPS miss, a sequential gross margin slip, stalled asset monetization and a steep Q4 revenue requirement give bears legitimate ammunition. Turnaround believers may find the Arcadia win and Walmart refresh encouraging. Still, with $134 million of unrestricted cash and the stock near its lows, Plug needs to deliver the fourth quarter it has promised, not just book more agreements.
Read our earnings preview for Plug Power, Inc.: https://www.earningswhispers.com/article/PLUG/22661
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 |
