Repay's First Full Quarter With Kubra Puts Organic Growth Promise To The Test
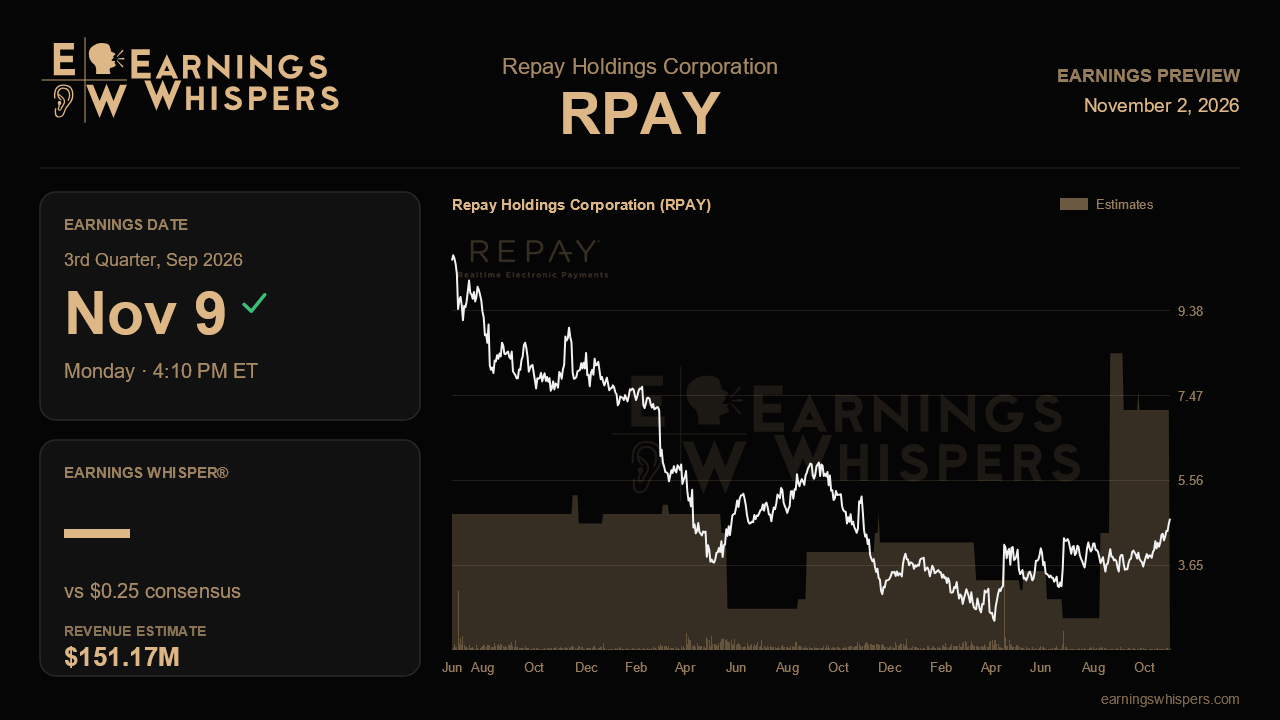
Repay Holdings heads into its third-quarter report with a stock that has already rallied and a story that is still half-proven. The Kubra acquisition, which closed June 1, roughly doubled the company's revenue base. Management used the last call to sell a more confident, expansive vision than the defensive tone of the spring. What it did not deliver was a clean read on how the combined business actually performs. This quarter is the first with Kubra in the numbers for a full three months, so the November 9 release is the first real look at the new Repay.
Wall Street expects earnings of $0.25 a share on revenue of $151.2 million. That revenue figure would be up about 94.5% from $77.7 million a year ago, but it is almost entirely an acquisition effect rather than a sudden surge in demand. The EPS bar sits well above last quarter's $0.14 and the year-ago $0.17, which assumes Kubra's contribution and early synergies flow through despite heavier interest costs. Management reaffirmed full-year revenue guidance of $490 million to $500 million, and the $495 million consensus sits right at the midpoint. So the Street is neither stretching nor hedging. Repay reported about $181.5 million through the first half. If it hits the third-quarter estimate, the fourth quarter would need roughly $162 million to land in the middle of the range, which makes this quarter's trajectory an important checkpoint.
The more revealing numbers sit beneath the headline. Management said consumer organic growth improved to about 4% excluding political volume. It also argued that enterprise backlog clients going live in July should push that segment to double-digit organic growth in the second half. This report is the first chance to see whether that acceleration is real. Business payments, which grew about 19% on a normalized basis last quarter, also need to hold their momentum. That matters all the more because Visa's interchange changes remain a drag on the accounts-receivable side. Continued growth in the supplier network, which reached 731,000 vendors, and in software partners would suggest the B2B flywheel is still turning. Kubra's own mid-single-digit growth means stronger legacy Repay growth is essential to keep the blended profile attractive.
Margins are the other swing factor. Gross margin fell to 70% from the mid-70s as Kubra's print, mail and professional services work entered the mix. Management framed this as mix rather than pricing pressure, so a stable margin around that level would support the explanation, while further slippage would invite harder questions. Adjusted EBITDA guidance of $168.5 million to $176 million implies roughly a 35% margin. Synergy progress is the lever to watch: $4.5 million in annualized run-rate savings exited the second quarter, against targets of more than $8 million by year-end. Cash flow deserves scrutiny too. Free cash flow conversion guidance was cut to 30%, and last quarter's 75% print reflected working-capital timing. With leverage near 3.7 times and a $500 million term loan carrying a steep spread, any early evidence of deleveraging toward the sub-3x goal would count for a lot.
The market has already given Repay some benefit of the doubt. Shares have gained about 15% since the last report while the S&P 500 slipped, and at $4.58 the stock sits well above its 200-day average. It is also pressing against its post-earnings high of $4.60, so the report could decide whether it breaks out or stalls. Sentiment has edged from slightly bullish to slightly bearish, a small shift, but one that hints at some caution after the run.
In the end, the question is whether Repay's improvement is more than arithmetic. A quarter showing double-digit consumer organic growth, steady margins and synergies ahead of plan would validate the turnaround story heading into the December 7 Investor Day. A print that leans entirely on Kubra's added revenue while organic growth and cash conversion lag would suggest the rally got ahead of the evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-26 | |
| Oct-13 | |
| Sep-23 | |
| Sep-03 | |
| Aug-26 | |
| Aug-19 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 | |
| Jul-28 | |
| Jul-27 | |
| Jul-23 | |
| Jul-16 |
