Repay's Political-Media Windfall Props Up Guidance As Core Consumer Growth Stalls And The Normalized Outlook Is Cut
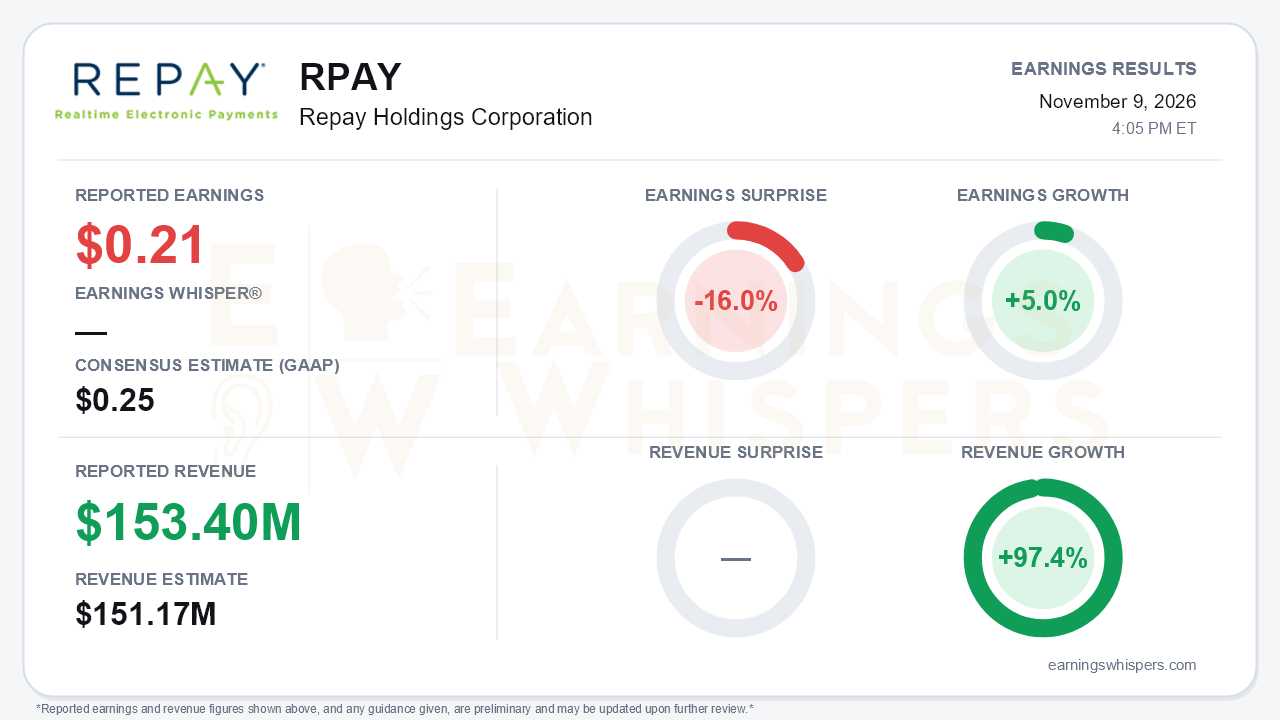
Repay Holdings Corporation (NASDAQ: RPAY) reported third-quarter earnings of $0.21 per share, missing the $0.25 consensus by 16.0%, while revenue of $153.4 million topped the $151.17 million estimate by 1.5%. Earnings grew 5.0% year over year and revenue jumped 97.4%, mostly because of the KUBRA acquisition. The basis matters here. The company's own adjusted net income per share was $0.25 versus $0.21 a year ago, and on a GAAP basis Repay lost $0.11 per share. Investors will therefore see different headline comparisons depending on the measure. The more consequential issue is that the reaffirmed full-year revenue, organic growth and EBITDA targets now rest on a cyclical political windfall rather than the core business management had promised would accelerate. That is the central tension of the quarter.
The composition of growth deserves scrutiny. Organic revenue rose 14%, but 9 points came from political media spending. Normalized organic growth was about 5%, roughly in line with the ~4% of the first two quarters. Consumer Payments, the company's largest franchise, grew organically just 0.3%. Business Payments did the heavy lifting, up 99% reported and 40% excluding political revenue, versus 19% ex-political in Q2. That included a $3 million first contribution from a new bank reseller channel. Adjusted EBITDA climbed 63% to $50.9 million. Margins, however, moved the wrong way on KUBRA mix: gross margin fell to 65% from 74% a year ago and 70% in Q2, and adjusted EBITDA margin slipped to roughly 33% from about 36% last quarter. Below the operating line, interest expense rose to $15.5 million from $3.1 million on acquisition debt, which explains why a 97% revenue increase still produced a wider GAAP net loss of $10.4 million.
The call marked a clear shift in tone, from confident acceleration to repositioning. On the Q1 and Q2 calls, management had pointed to double-digit second-half consumer growth driven by booked clients. That has not materialized. The company cited weak pull-through from its 2025 and 2026 bookings cohorts, a rationalized pipeline, and sales-team turnover under new consumer leadership. Q4 consumer growth is now guided to low single digits, with recovery pushed into 2027. As a result, normalized organic growth guidance was cut to 5%-6% from 7%-9%. The CEO acknowledged consumer results 'did not meet our expectations' and described 'deliberate initiatives to improve competitive positioning.'
There are genuine offsets, and the call preserved a credible secondary growth story:
- **KUBRA:** pro forma growth accelerated to about 8% from roughly 6% in Q2, and the exit-2026 synergy run-rate target rose to $11 million from $8 million.
- **Bank reseller channel:** the partnership with a large global fintech has 52 banks consented (96% of plan) and is expected to contribute $6-7 million this year at roughly 40% margins.
- **Political media:** the full-year forecast doubled to $16-18 million from $8-10 million, and October activity exceeded the 2024 presidential peak.
The value of these drivers varies. The political lift will not recur in 2027, and the bank channel's value depends on actually signing and migrating banks.
Cash flow is where bears have the most ammunition. Free cash flow swung to negative $21.1 million from positive $27.4 million in Q2. The drivers were the $14 million channel investment, working-capital timing tied to political media and KUBRA receivables, and capitalized software spending that nearly tripled year over year to $30.3 million. Management expects the working-capital drag to reverse by year-end. Even so, it cut full-year free cash flow conversion guidance to 20%-25% from 30%, and adjusted conversion to 25%-30% from 35%. Net leverage ticked up to 3.8x from 3.7x. Management still targets below 3.0x by year-end 2027, but that path now leans on a consumer recovery that has just been deferred.
The market setup is more complicated than the revenue beat implies. Shares had run up 10.6% since the open after the August report, to $4.40. That left them about 22% above the 200-day moving average and only 8.4% below a 52-week high of $4.81 set just days before the release, with the Earnings Whispers trend readings broadly positive heading in. Investor sentiment moved the other way, slipping from roughly neutral to modestly negative (+0.02 to -0.14). The stock therefore entered the print near the top of its range while investors were already turning more cautious, leaving little cushion for a quarter that cut normalized growth and cash-conversion targets.
The bottom line is that Repay held its headline guidance only because political advertising and a strong Business Payments segment covered for a stalled consumer core. Investors are being asked to trust a 2027 recovery while leverage remains elevated and free cash flow has turned negative. The December 7 Investor Day now carries real weight. Management needs a longer-term framework that shows consumer growth can rebuild once the election-cycle tailwind fades.
Read our earnings preview for Repay Holdings Corporation: https://www.earningswhispers.com/article/RPAY/22669
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-26 | |
| Oct-13 | |
| Sep-23 | |
| Sep-03 | |
| Aug-26 | |
| Aug-19 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 | |
| Jul-28 |
